News
Sri Lanka wouldn’t have been in crisis if CBSL had floated rupee in April last year –Dr. Wijewardena

By Shamindra Ferdinando
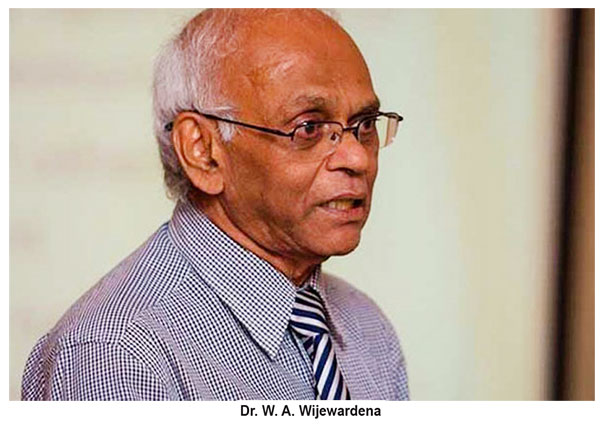
Former Deputy Governor of the Central Bank, Dr. W. A. Wijewardena says the country wouldn’t have been in the current predicament had the Monetary Board floated the Rupee in April 2021, six months before Ajith Nivard Cabraal succeeded Prof. W.D. Lakshman.
Consultant on banking, finance and economics, Dr. Wijewardena said so when The Island sought clarification regarding declaration on ‘Hiru’ on Sunday (13) that the incumbent government since Dec 2019 squandered as much as USD 5,500 mn trying to prevent the depreciation of Rupee. Dr. Wijewardena explained how the failure on the part of the Monetary Board to take remedial measures at the required time caused a catastrophe.
Dr. Wijewardena pointed out that Cabraal, who succeeded Prof. Lakshman, too, failed to address the issue. Cabraal quit his SLPP National List seat to receive the Governor’s post on Sept 15, 2021. Cabraal served as State Minister of Money and Capital Market and State Enterprise Reforms at the time of his resignation.
The retired CB Deputy Governor emphasised that the much touted ‘road map for economic recovery’ that had been announced on Oct. 1, 2021, didn’t recommend depreciation of the Rupee. The outspoken former CBSL official said that the depreciation of the Rupee/floating of the Rupee hadn’t been among the remedial measures announced by the incumbent governor.
The much-delayed decision to float the Rupee in the second week of March this year should be examined against the backdrop of the overall failure of the so-called ‘road map for economic recovery’ to achieve its targets within six months, Dr. Wijewardena told The Island.
Responding to Hiru interviewer, Dr. Wijewardena said that though CBSL expected the country to receive as much as the USD 10.5 mn during Oct-Dec, 2021 period, it didn’t materialise. Alleging that the timing of the floating of the Rupee had been unnecessarily delayed, Dr. Wijewardena asserted that the consequences could be quite devastating. The veteran banker compared the cash-strapped Sri Lanka economy with an uncontrolled kite.
Dr. Wijewardena cited the pathetic failure on the part of the entire banking system to meet USD 16 mn requirement to pay for a crude oil carrier underscored the crisis the country faced. Responding to The Island queries, Dr. Wijewardena questioned the culpability of the Monetary Board as regards the handling of the economy.
The current five-member Monetary Board consists of the Governor Cabraal (ex-officio), Treasury Secretary S.R. Attygalle (ex-officio), Sanjeewa Jayawardena, PC, Dr. Mrs. Ranee Jayamaha and Samantha Kumarasinghe. Mrs. Jayamaha, an ex-Deputy Governor, CBSL and Multichemi International Ltd Chairman Kumarasinghe joined the Monetary Board in late June 2020 whereas Jayawardena received his appointment in Feb 2020.
The Monetary Board couldn’t absolve itself of the responsibility for the current crisis, Dr. Wijewardena said, urging the government to review the entire situation without further delay.
Basil Rajapaksa replaced Mahinda Rajapaksa as the Finance Minister in July last year.
According to Dr. Wijewardena, the banking system experienced a critical shortage of Rupees in addition to the foreign currency crisis. Dr. Wijewardena estimated that the current Rupee shortage at Rs 700 bn.
Dr. Wijewardena urged the CBSL to immediately increase bank interest rates from 7.5 percent to at least 15 as an initial measure to address the crisis. Dr. Wijewardena, who had served the CBSL for over 40 years emphasized that the recent decision to increase interest rates from 6.5 % to 7.5% was not adequate at all.
Sri Lanka couldn’t address the developing crisis by securing limited funds from India, China and Bangladesh. Instead, the assistance of the International Monetary Fund (IMF) should be secured, the veteran banker pointed out, adding that those who dismissed repeated calls to seek IMF help to restructure Sri Lanka’s debt should accept responsibility for the pathetic state of affairs today.
He compared a country’s foreign reserves with that of savings of an individual. “Savings are utilized in an emergency,” Dr. Wijewardena said, pointing out the absurdity in using foreign reserves to protect/prop up local currency. The ex-banker recalled how the Thai government moved court against the Governor of its Central bank Rerngchai Marakanond for spending USD 4.6 bn or 2.5 bn Pounds to prop up Baht during 1990s financial crisis. The Bangkok Civil Court in May 2005 directed Marakanond to reimburse the Bank of Thailand within a month, Dr. Wijewardena said. Although, the Supreme Court cleared him a decade later, the case established culpability of a decision maker/ decision makers in such a situation.
As the Parliament is accountable for public finance and enactment of laws, the responsibility of the House, too, should be examined, Dr. Wijewardena said.



[Prime Minister’s Media Division]
[Prime Minister’s Media Division]


… warn of dire consequences
A group of trade unions and civil society groups has requested President Anura Kumara Dissanayake to abandon his government’s controversial plan for the proposed tripartite management of the EPF.
The group has told the President: “We strongly object to the government’s plan to transfer the EPF to a tripartite board—jointly promoted by the Employers’ Federation of Ceylon (EFC), International Monetary Fund (IMF) and the International Labour Organisation (ILO)—and to increase the investments of those funds within private equity and debt markets.
“While the EFC and the government jointly project this plan as a ‘modern governance framework’, it poses a serious threat to the EPF’s financial stability, fiduciary conduct, and returns to workers’ life savings, with severe consequences for broader macroeconomic stability. Rather than replacing the corruption existing in the public sector, this tripartite framework paves the way for a corporate takeover of the EPF. Through this, the fund is exposed to unlawful business practices such as insider trading using internal information of EPF investments, conflicts of interest and corporate bailouts of unstable private companies.
“Sri Lanka’s corporate sector has a tremendously negative track record, which you alluded to during your victorious election campaign in 2024. This was recently unravelled by the multi-billion-dollar illicit capital flight through trade misinvoicing, which your administration is now actively working to curb in the imports sector.
“The recent banking sector fraud exceeds Rs. 13 billion; widespread corporate tax evasion destabilised the fiscal position (Sri Lanka Auditor General’s Department Annual Reports) and consequently inflated the tax burden on the general public. The EFC has found it convenient to remain silent about these crimes, possibly assuming that their silence would preserve their social standing. Considering this inherent corruption within Sri Lanka’s corporate sector and its disregard to the living standards of the general public, there is no realistic basis to integrate corporate interests to actively manage the EPF. The corporate sector of Sri Lanka has not developed sufficiently on technical and ethical grounds to safely entrust the largest retirement savings pool in the country. The EPF is a captive fund that has no mechanism for the owners to divest if the management is corrupt. This further increases the possibility of corporate fraud when the management of the fund is jointly held with the corporate sector.
“Furthermore, during the recent public discussion with trade unions, Deputy Minister of Finance Dr. Anila Jayantha pointed out that the domestic debt restructuring (DDR) would inflict a loss of Rs. 600 billion to the EPF. Our independent calculations—formally submitted as an affidavit to the Supreme Court approved by the Federation of University Teachers’ Associations in 2024—reveal that nominal loss alone is Rs. 634.4 billion. When factoring in foreclosed reinvestment returns, the true loss skyrockets to Rs. 1,711 billion, wiping out 48% of the fund’s projected gross income for the 2023 – 2028 period. Under the pretext of safeguarding the banking system, this colossal robbery preserved high yields on government bonds held by commercial banks and high-net-worth individuals, subsequently reaping them astronomical profits. Now, the exact same plunder is rearing its head again disguised as a tripartite committee.”
“The main arguments supporting our resistance and viable alternatives for optimising EPF management directly under the Central Bank of Sri Lanka (CBSL), are outlined below.
“Objections to the government’s tripartite proposal:
1. The “International best practice and conflict of interest fallacies”
The government holds that tripartite management of pension funds is the “international best practice” and that there is a “conflict of interest” in CBSL managing the EPF. They are key pillars justifying government’s tripartite proposal.
These two positions are shockingly misleading given that four of the five largest pension funds in the world, in Norway, Japan, the U.S., and Singapore, are managed directly by state bodies or central banks. Therefore, ‘international best practice’ in pension fund management is the exact opposite of what the government and the IMF are proposing. We hence reject these baseless positions.
2. Corporate captivity and bailouts
It is clear that the EFC is desperately pushing for this proposal at a time of global uncertainty, to cushion the effects of the crisis and maximise gains. Under corporate influence within the proposed tripartite board, the private conglomerates can use the multi-trillion-rupee EPF to continue their unstable commercial operations without having to risk their own capital or savings to do so. This will severely erode the financial stability of the EPF and its returns.
3. Risk of front running
“Because the EPF is a colossal fund, its investment decisions can alter asset prices. This creates immense monetary value for the information generated by its investment decisions. Corporate representatives on the proposed tripartite board will be perfectly positioned to use this information to trade ahead of the EPF (front-running), buying assets cheaply and dumping them onto the EPF at inflated prices for guaranteed corporate gain, resulting in a reduction of returns to the EPF.
4. Unavoidable loopholes
“Presence of a separate group of investment analysts, trade union representatives and government officials within the proposed tripartite structure cannot prevent pre-market corporate access to EPF’s investment decisions. Investment proposals made by the analysts has to be first approved by the proposed tripartite committee, making it impossible to prevent corporate access to insider information on EPF investments.”

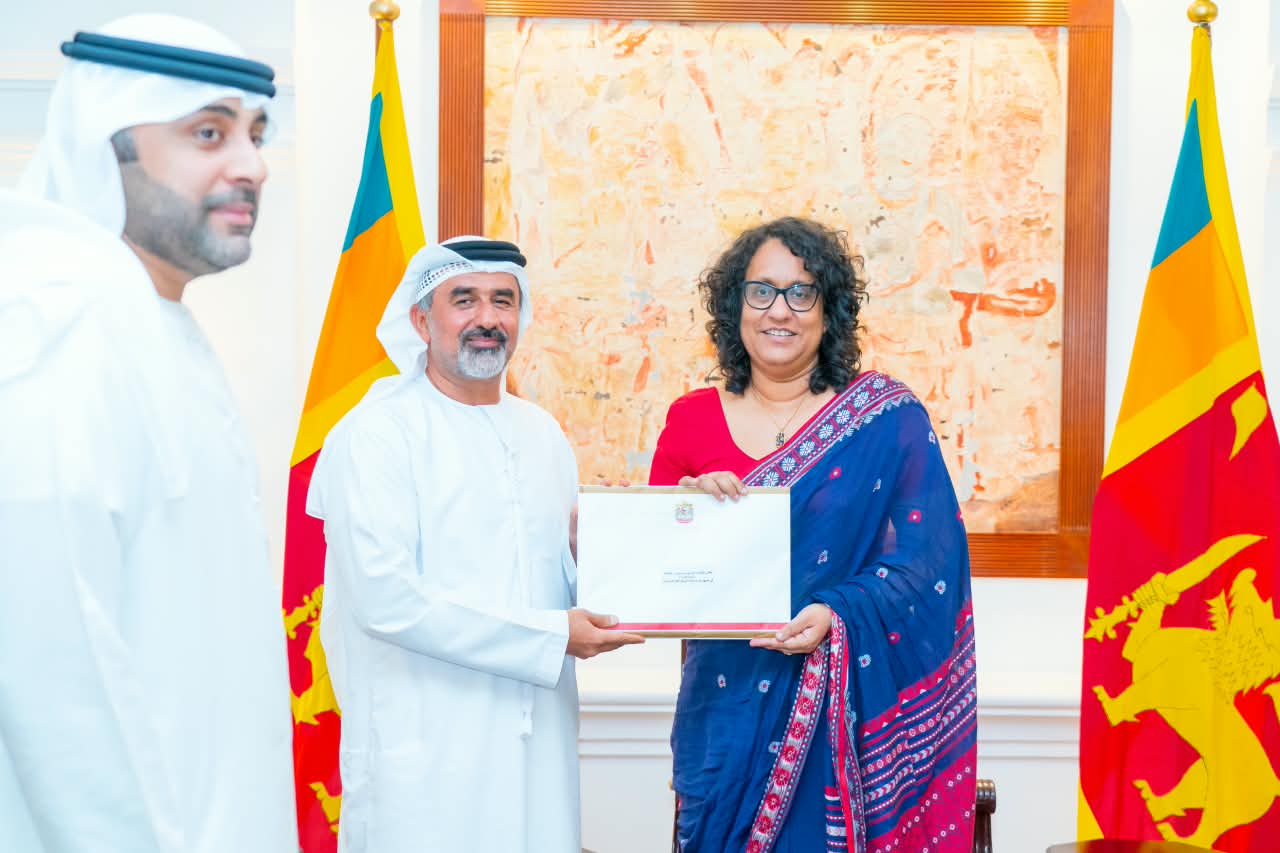
Ambassador of the UAE to Sri Lanka meets with the Prime Minister

EU rejects Trump’s diesel demand amid Iran war shortages

Sineth Jayawardena, Vijayakanth Viyaskanth in Sri Lanka squad for Pakistan T20Is

Bronze at stake as Bangladesh, Sri Lanka look to bring cheer to Asian Games contingents

Wanderers to host 2027 men’s ODI World Cup final as well as India vs Pakistan

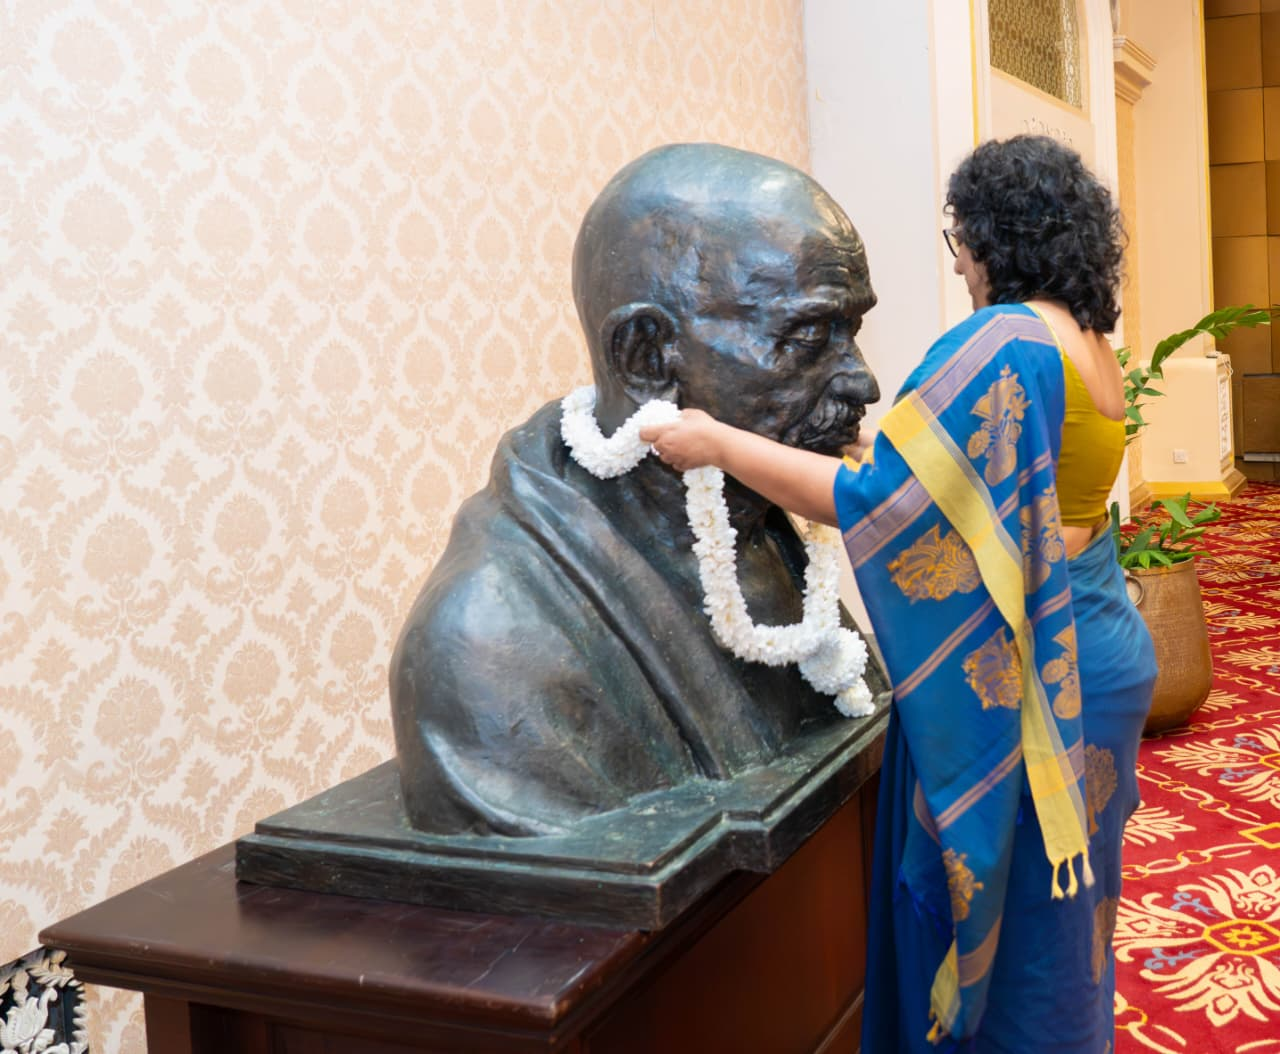
Prime Minister joins Gandhi Jayanti Commemoration

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Editorial7 days ago
Birth of a bad law
-
 News5 days ago
Police remove Thileepan statue in Jaffna
-
 News7 days ago
TIN mandatory for key transactions from Nov. 1
-
 Features5 days ago
The 22nd Amendment, constitutional recovery and illiberal slippage
-
 Features5 days ago
Of foreigners as CEOs of Lankan ventures
-
 News5 days ago
Sajith rejects Jt. Opp. protest sabotage claim; SJB TU chief demands remedial action
-

 Latest News2 days ago
Gold winner Tharanga gets brand-new Honda Vezel from SLAAJ
-
 Features4 days ago
Thailand’s biggest new global star …