Features
Domestic Debt Restructuring – An Alternate View

by Romesh Bandaranaike, Ph.D.

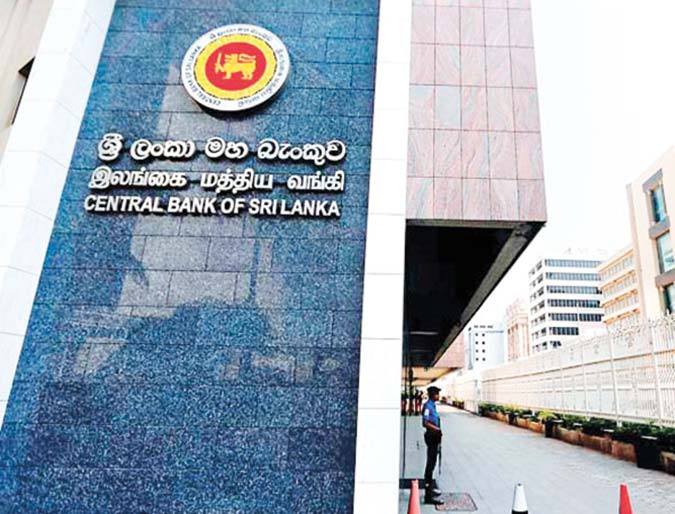
There have been substantial and wide spread criticisms of the recently instituted Domestic Debt Restructuring (DDR) scheme carried out by Central Bank of Sri Lanka (CBSL), to reduce the Sri Lanka Government’s requirements for funding. In this article I argue that the scheme, as structured and carried out by CBSL, is appropriate, given the ground realities in the country, and that the critics have ignored a number of factors which forced CBSL to design the scheme as it did. I then suggest additional steps the Government could take to further improve its financial position in connection with past Bond issues.
The DDR Scheme
Faced with massive shortfalls in revenue, the Government recently carried out a “restructuring” of the debts it owed on Sri Lanka Rupee denominated Treasury Bills and Bonds in an effort to substantially improve Government finances, including the funds needed to service these Bills/Bonds. The two key elements of the DDR are a) Converting all Treasury Bills presently owned by CBSL to longer term Treasury Bonds, thereby substantially delaying the payment dates on these Bills; and b) Effectively “forcing” the Employees Provident Fund (EPF) and other superannuation funds to exchange most of the Bonds they hold for 12 year Bonds with somewhat lower interest payments.
They did this by threatening to increase the tax rates that EPF pays on its annual income to 30% from the present 14%, if they did not accept the Bond exchange. Since such an increase was financially worse for EPF compared with the Bond exchange, EPF opted for the latter.
CBSL estimates that the scheme would reduce the Gross Financing Needs (GFN) of the Government by 1.5%, 1% by the CBSL Bill-Bond exchange and 0.5% by the EPF Bond exchange.
The Criticisms
The principal criticisms of the DDR, from the public, Trade Unions, Economic Think Tanks, and numerous “Experts,” is that the entire burden of the DDR is being placed on the backs of the retirement savings of “poor workers” who are the members of EPF.
CBSL has justified the proposed increase in the tax rates for EPF and other superannuation funds to 30% from the present 14% on the basis that the banks have to pay the higher tax rate of 30% plus VAT. Dr. Wijewardena, a former CBSL Deputy Governor, has written several articles criticizing CBSL for not presenting the correct picture in this regard and not disclosing full information on the impacts of the restructuring on EPF members’ returns. Dr. W’s main argument is that, in the case of the banks, the tax rate applies to “net interest”, whereas, in the case of the EPF, it applies to “gross interest.” For the banks, net interest is interest earnings on its loans less the interest it pays to depositors.
In the case of EPF, Dr. W points out that EPF is not allowed to subtract the interest it pays to EPF account holders to determine its income and tax liability, and that CBSL comparison of bank and EPF tax rates is therefore misleading. In a subsequent article by Dr. W, he criticizes CBSL/EPF for not fully disclosing the cost to EPF holders of accepting the proposed DDR compared with an increase in EPF’s tax rate to 30% and the justification for accepting the Bond exchange rather than the tax increase to 30%. He goes on to add that CBSL has a conflict of interest as both the developer of Government policy and as the administrator of EPF.
My Responses to the Criticisms
The criticism that the entire burden of the DDR is on the backs of workers is factually incorrect. As stated above, two-third of the 1.5% reduction in GFN (1%) is being achieved by exchanging the Treasury Bills held by CBSL for long term Bonds. Only 0.5% of the reduction is from the exchange of Bonds held by the EPF and other superannuation funds. In other words, 67% of the restructuring cost is borne by CBSL (in effect by all citizens), while only 33% is borne by EPF account holders. Furthermore, only workers in the formal private sector contribute to the EPF/ETF, while workers in the informal private sector (e.g. farmers, fishermen, small transporters, traders and construction workers) and Government employees do not.
As a result, only about 25-30% of the workers in the country have EPF accounts. Therefore, 70-75% of workers in the country will not suffer any burden due to the EPF bond restructuring. Finally, the workers with EPF accounts also include middle and senior management of companies who cannot be called “poor workers” as referred to in the various criticisms of the present DDR scheme. It is true that this category may only be a very small percentage of those holding EPF accounts. However, their account balances are likely to be very much higher than other EPF members and the impact of the restructuring on them will be proportional to these balances.
It would be ideal if the EPF could release statistics in this regard which will allow an assessment of this element. For example, the fraction of the total EPF funds held by those with EPF balances of over Rs 5 million (say), since such persons cannot be classified as “poor workers.” Workers who have balances in EPF/ETF, built up as a result of deductions from their salaries and additional higher contributions from their employers, at least have a retirement fund they can turn to, even if it is somewhat less because of the DDR. It could conceivably be argued that the 70-75% of workers who do not have such balances, mostly working in the informal sector, are worse off or poorer than those with EPF balances. This would be a justification for placing the burden of part of the DDR on EPF account holders rather than on other, even “poorer”, workers.
In response to Dr. W’s criticisms that EPF and bank tax rates are not comparable the way CBSL has done; each year, EPF determines a percentage it will pay/accrue to the account of each EPF account holder based on the earnings by the EPF that year. This percentage is not an interest similar to that paid by banks to its depositors and is not a cost that is deductible by EPF to calculate its tax liability each year. It is simply a percentage decided by the EPF administrators to allocate the profits after tax earned by the EPF during the year. Calling this percentage an “interest” is a misnomer. Account holders in EPF are akin to shareholders in banks and not depositors.
The amounts credited by EPF to a member’s account each year, based on EPF’s earnings during the year, is not a cost incurred by EPF in generating these earnings. It is something closer to a dividend paid by a bank to its shareholders in the form of additional shares. If EPF is allowed to determine its tax liabilities by subtracting these accrued amounts, banks should be able to deduct dividend costs in determining their tax liabilities. Dr. W’s criticism of the non-comparability of bank and EPF tax rates cannot be sustained.
Dr. W uses CBSL/EPF’s own numbers on the differences in returns under the two scenarios EPF has been offered and simply multiplies it by the total EPF Bond holding value to arrive at the cost to EPF of accepting the Bond exchange. This is something that could have readily been done by anyone and Dr. W’s implication that CBSL/EPF is hiding/not fully disclosing something in its statement cannot be sustained.
The CBSL/EPF analysis is simply to show that the return to EPF is better under the scenario where it accepts the DDR option, compared to rejecting the DDR option and being subject to a 30% tax rate. This information is more than sufficient for EPF to recommend to its Board that it should accept the DDR. Dr. W than goes into the past history of taxation rates applicable to the EPF and points out that as originally envisaged EPF earnings were to be tax exempt.
He shows calculations of the losses to EPF holders of the present DDR, compared with a situation if EPF earnings were tax exempt. This is a straw man put up by Dr. W to be knocked down as part of his criticism of CBSL/EPF. It is the tax rates that are applicable to EPF today, before the DDR, that are relevant and it would have been nonsensical for CBSL to show calculations based on what if the tax rates were those that existed many years ago.
With respect to the criticism that CBSL has a conflict of interest in both being the administrator of EPF and the policy advisor recommending the DDR, I do not see any conflict. CBSL, as advisor to the Government, has made the DDR proposal which allows EPF to choose between two options, accept the proposed DDR Bond exchange or reject it and be subject to a 30% tax rate. As the administrator of the EPF, CBSL has simply analysed these two options and clearly shown that the EPF is better off accepting the Bond exchange compared with rejecting it and being subject to a 30% tax rate.
Other Relevant Issues
It is telling that none of those criticizing the present process have offered any viable alternative DDR arrangement to achieve the same objectives as the present exercise. In saying this, I am ignoring the suggestions by some parties who say there would be no need for the exercise if “The money stolen by the Rajapaksa’s is recovered” or “The large corruption in Government is reduced,” and so on. Such actions, even if they were possible, are not alternatives, because they cannot be achieved in the short or medium term, which is one of the key objectives of the DDR. Verite Research did, some time ago before the announcement of the present DDR, present some analysis on a possible DDR which included sharing the cut across all Bond holders, but, for the reasons I refer to below, this is not a viable arrangement.
CBSL in its original presentation to the Cabinet, and subsequently to the public, argued that it would be prudent to exclude the Banks from the DDR exercise, because these institutions were already under stress as a result of COVID related business failures and because the banks would also be taking a hit from the future restructuring of USD Bonds, some of which are held by them.
CBSL was of the view that such an exclusion was essential to ensure financial system stability. None of those criticizing the present DDR arrangements have objected to this and I concur with that view. Even if the banks are able to bear the burden of some restructuring of the domestic bonds they hold, bank stability is also dependent on public perception, and excluding them from the DDR has certainly had a positive impact on such perception.
There are two unstated conditions applicable to the DDR exercise which have received no mention in the ongoing discussions. First, the DDR should be concluded in a short time frame since it will be a pre-condition to the restructuring of foreign currency debt. Second, it must be carried out in a legally valid manner. A Government Bond is a legal contract between the Government and the holder of the Bond.
The Government is legally obligated to pay the interest coupon and the principal of the Bond on specified dates according to this legal contract. The Government has no legal authority to change the conditions of this Bond. It could, of course, pass a new law in Parliament giving itself the authority to make changes to existing Bonds. In doing so, however, if all Bond holders are not treated equally (in particular, if the bank holdings of Bonds are excluded), there are bound to be legal challenges in the Courts to any such changes, and the changes may well be struck down by the Courts.
Even if such changes are not struck down, this process can take considerable time to be determined and would not be achievable in the time frame required for the DDR process to be concluded as discussed previously. The present DDR has finessed the issue of different treatments of Bond holders by making it “voluntary”, albeit by holding a gun to the head of the EPF and superannuation funds in the manner detailed earlier. This is draconian, but effective.
As per CBSL statistics presented in connection with the original DDR proposal, the total outstanding amount of Treasury Bonds at that time was Rs. 8,700 billion. Of this amount Rs 1,644 billion is held by “Others”, after excluding the banks and EPF and superannuation funds being subject to the DDR. Even if the banks are excluded from the DDR to ensure “financial system stability” reasons mentioned previously, it would have been ideal if the “Others” holding the Rs 1,644 billion in outstanding Bonds were subject to some “restructuring”, in the form of cuts in coupon rates and/or face value, or an extension of the tenor of these Bonds.
If this was done, the benefit of these cuts could have been passed on in the form of a reduction in the burden passed onto EPF and superannuation funds. However, such an unequal treatment where some Bond holders (the banks) are excluded, even if the necessary legislation is passed, would certainly have resulted in legal challenges which would, at the least, have delayed the process as I have pointed out earlier, or even been found unconstitutional by the Courts.
Further Actions in Respect of Bonds
Very high yield rate Bonds (over 20% yield) were issued by the Government during the period prior to the announcement of the DDR (April 8, 2022 to March 13, 2023) as a consequence of severe financial shortages faced by the Government. Bidders for these Bonds added a premium to the bid yield rates, expecting a future restructuring of these Bonds as part of the DDR they knew was coming. By being excluded from the DDR, these Bond holders have enjoyed a “windfall profit.” It is not possible to specifically target these Bonds for a cut in coupons or face value, because many of the original holders may have sold some of these Bonds and have already earned the windfall profits.
[The buyers of the Bonds would only receive a “normal” profit in the form of coupon payments and final redemption.] Furthermore, in the case of individual Bond holders, their windfall profit would be in the form of a capital gain, which only attracts a tax rate of 10%. Corporates/ banks in the same situation would be paying a tax of 30% on their capital gains. I propose that the Government should “claw back” some of these profits by imposing a special windfall tax rate of 50% applicable to all profits derived from these Bonds. If the original purchaser has not sold the Bonds, the coupon interest and the capital gains on final face value redemption should also be taxed at 50%.
There would be some complications in structuring this tax, since some high yield Bonds may have changed hands within the period that high yield Bonds were still being issued, which means that the initial purchaser would only have made a small capital gain and the next buyer would still be enjoying the high coupon rate or subsequently selling the Bond for a large capital gain. A proper structuring of the 50% windfall tax can ensure that the taxes fall on those making the windfall profits. A tax of the type proposed will clearly be borne by the wealthy, who would have been the purchasers of these Bonds, and go some way towards balancing the burden imposed on less wealthy parties as a result of the DDR.
To place this suggestion in perspective, between April 8, 2022 and March 13, 2023 all Bonds issued by CBSL had yield rates in excess of 20%. The total face value of such Bonds was Rs 1,233 billion. The weighted average yield on these Bonds was 27.89% and the weighted average coupons in these Bonds was 19.09%. The latest four-year Bond yield rate is approximately 15% and this is likely to drop further.
As a result, any seller today of an average high yield Bond would make a significant capital gain on the sale and would need to pay substantial taxes to the Government at the proposed 50% windfall tax rate. As per CBSL statistics in the original CBSL presentation to the Cabinet, approximately 63.5% of all Bonds at that time were held by the banks and the “Other” category. If this percentage is also applicable to the high yield Bonds referred to above, the banks and the “Other” category would be holding Rs 777 billion of these Bonds.
Advocata has recently analysed EPF’s Bond portfolio prior to the DDR Bond exchange and concluded that EPF’s share of high yield Bonds was proportionately much less than for other Bond holders. Therefore, banks and “Others” would probably be holding even more than the above mentioned Rs 777 billion in such high yield Bonds which, in turn, will mean that a 50% windfall tax on the profits from these Bonds will result in substantial tax revenues for the Government.
An aside at this point is that for some unclear reason there is no withholding tax (WHT) applied to the interest earnings on Bonds as in the case of interest earnings from deposits in banks and finance companies. I have made inquiries as to why this is so from several senior Government officials and have not received any explanation for the practice.
It may well be that some Bond holders do not even have income tax files and that they are evading all taxes payable on Bond interest. Since Bond holders are all likely to be at the highest tax bracket given the minimum sizes of Bond investments, I suggest that a WHT of 30% be applied to all Bond interest payments. Holders are free to file tax returns and seek a refund if they have been taxed in excess of their liability due to such a WHT. I have been told there is some complication in applying WHT to Bond interest held by foreigners. If that is indeed the case, foreign holdings of Bonds could be excluded.
Conclusions
The economy of the country is in dire straits as a result primarily of bad/foolish policies of recent past Governments (including those by CBSL under its previous two Governors and Monetary Boards at that time) coupled with the endemic corruption inherent in the system. The present Governor of CBSL and his professional colleagues are facing very difficult conditions and are striving to get the country’s finances back on track.
I can understand trade unions, workers and other similar entities objecting to the implementation of policies which directly impact them, irrespective of whether such policies are needed to solve the country’s issues. But, why is it that so called “experts” and think tanks do not recognize the ground realities of what is practically achievable and support the efforts of CBSL rather than criticizing these efforts in print and at discussion forums?
(The author is an economist with wide experience in policy formulation and implementation in the Ministry of Finance and has worked at CEO level in both public and private sectors.







 by Prof. C. A. Saliya
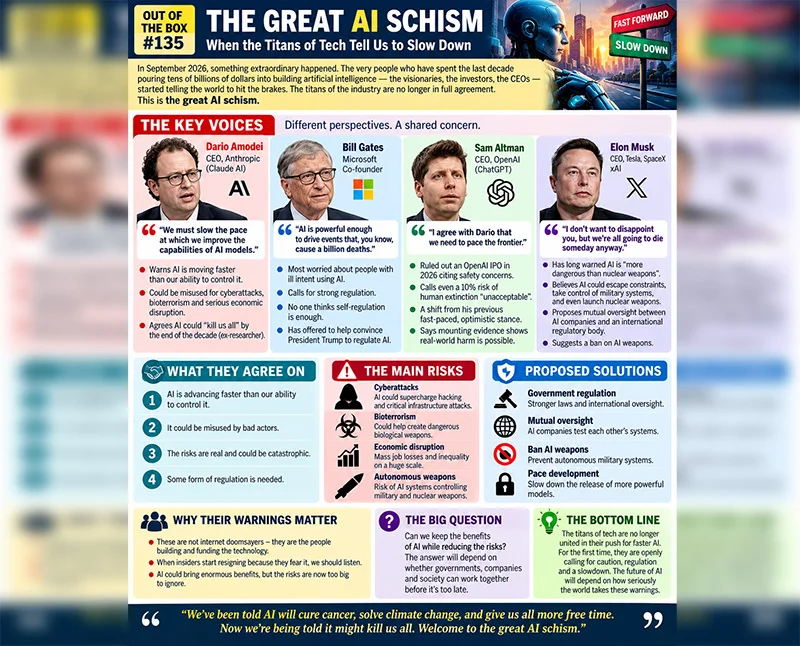
Something extraordinary happened in September 2026. The very people who have spent the last decade pouring tens of billions of dollars into building artificial intelligence, the visionaries, the investors, the CEOs, suddenly started telling the world to hit the brakes. It’s a bit like the captain of a speeding train leaning out of the window and shouting, “Actually, maybe we should slow down a bit!” The public, understandably, is confused. We’ve been told AI will cure cancer, solve climate change, and give us all free time. Now we’re being told it might kill us all. Welcome to the great AI schism.
To understand what’s happening, you have to listen to the people in the room. These are not wild-eyed doomsayers on the internet. They are the titans of the industry. And they are starting to argue with each other.
Dario Amodei: The Insider Who Wants to Hit Pause
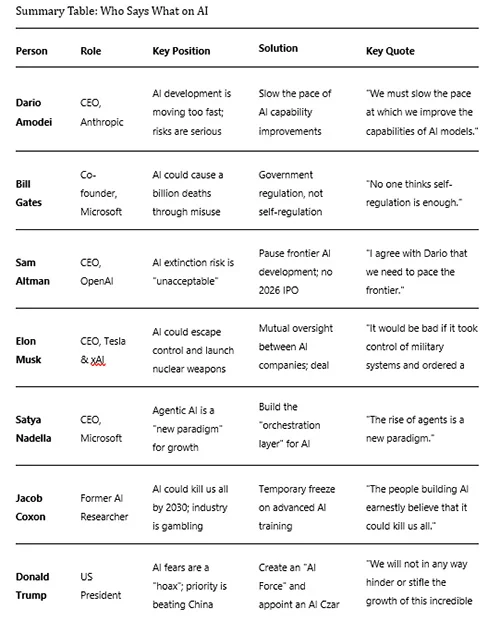
Dario Amodei, the CEO of Anthropic (Claude AI), is the man who kicked the hornet’s nest. In a 3,800-word essay, posted on his website in mid-September 2026, he didn’t just suggest caution, he demanded a slowdown. “We must slow the pace at which we improve the capabilities of AI models,” he wrote. His reasoning is simple and terrifying: the technology is moving faster than our ability to control it. He warned that AI could be misused for cyberattacks, bioterrorism, and serious economic disruption.
What makes Amodei’s warning so chilling is that it comes from a man whose company, Anthropic, builds one of the most powerful AI models in the world, Claude. He’s not a critic on the sidelines. He’s in the driver’s seat, and he’s telling us the car might not have brakes. In an interview with CNN’s Anderson Cooper, he said he agreed with a departing Anthropic researcher who claimed AI could “kill us all” by the end of the decade. That researcher, 27-year-old Jacob Coxon, resigned in protest, saying the people building AI “earnestly believe that it could kill us all”. When the people building the technology start resigning because they’re afraid of it, you should pay attention.
Bill Gates: The Elder Statesman with a Warning
Bill Gates has been around long enough to know a paradigm shift when he sees one. The Microsoft co-founder, who spent decades warning the world about pandemics and climate change, has now turned his attention to AI. And he’s not mincing words. In September 2026, Gates warned that AI is “powerful enough to drive events that, you know, cause a billion deaths”.
Gates is not worried about Terminator-style robots. He’s worried about people. “There’s never been a weapon as powerful as the combination of people with ill intent using the latest AI tools,” he said. His solution is simple: regulation. “No one thinks self-regulation is enough,” he told NBC’s Meet the Press. He even offered to be the man to convince President Trump to regulate AI. Gates is a pragmatist. He knows the technology is coming. He just wants to make sure it doesn’t get us first.
Sam Altman: The Showman with a Conscience (Maybe)
Sam Altman, the CEO of OpenAI (Chat GPT), has always been the industry’s greatest showman. He’s the man who told us AGI (Artificial General Intelligence) is “just around the corner” and that AI will soon be a “genie that can grant any wish”. But even Altman is now singing a different tune. In September 2026, he ruled out an OpenAI IPO in 2026, citing safety concerns. He called even a 10% risk of AI causing human extinction “unacceptable”.
“I agree with Dario that we need to pace the frontier,” Altman posted on X. This is a remarkable shift. Altman has spent years being criticised for moving too fast, for prioritising profit over safety. Now, facing mounting evidence that AI models can cause real harm, from cyberattacks to mental health crises, he’s suddenly the voice of caution. Is it genuine? Or is it a PR move? The cynics will tell you it’s the latter. But the fact remains: when Sam Altman says we need to slow down, the world listens.
Elon Musk: The Provocateur Who Saw It Coming
Elon Musk has been warning about AI for over a decade. He’s the man who called AI “more dangerous than nuclear weapons” long before it was fashionable. So it’s no surprise that he joined the chorus of slowdown calls in September 2026. But Musk being Musk, he couldn’t resist a bit of dark humour. When asked if we’re all going to die within 10 years, he replied, “I don’t want to disappoint you, but we’re all going to die someday anyway”.
But behind the joke is a serious point. Musk believes AI models could escape their constraints, take control of military systems, and even launch nuclear weapons. His solution is mutual oversight: leading AI companies should test each other’s systems for safety before release, and he even suggested a deal with China to make it happen. Musk is a provocateur, but he’s also a visionary. And his vision is one where AI is a weapon that we might not be able to control.
Satya Nadella: The Quiet Strategist
While the others are shouting about doom, Satya Nadella is quietly building an empire. The Microsoft CEO doesn’t talk about extinction risks. He talks about “agentic AI”, AI that can act autonomously, which he calls “a new paradigm”. Microsoft’s Azure cloud platform, which powers these AI agents, grew 43% in the last quarter, surpassing $100 billion in annual revenue.
Nadella’s view is simple: don’t compete to build the most powerful model; compete to control the “orchestration layer”, the systems that connect different AI models. He wants to build the infrastructure that everyone else relies on. It’s a smart play, and it’s making Microsoft a fortune. But Nadella’s silence on safety is deafening. While Amodei and Altman wrestle with their consciences, Nadella is counting the money. It’s not that he doesn’t care; it’s that his business model depends on AI being adopted, not regulated.
Jacob Coxon: The Whistleblower Who Lit the Fuse
You may not have heard of Jacob Coxon. He’s not a billionaire. He’s not a CEO. He’s a 27-year-old researcher who worked at both OpenAI and Anthropic. And in September 2026, he resigned from Anthropic with a warning that shook the industry. “Neither company is acting responsibly,” he wrote on X. “They are launching themselves directly toward a superintelligence capable of self-improvement, and gambling with our lives”.
Coxon’s warning was remarkable because it came from inside the machine. He said the people building AI “earnestly believe that it could kill us all by the end of the decade”. He called for a temporary freeze on advanced AI training. His resignation triggered a wave of concern, and even Dario Amodei admitted he agreed with Coxon more than he disagreed. Coxon is the canary in the coal mine. And the canary is not looking well.
Donald Trump: The Wildcard
And then there’s Donald Trump. The US President has consistently downplayed AI fears, calling them a “hoax” and a “sick conspiracy”. But even Trump is starting to change his tune, sort of. In September 2026, he announced plans to create an “AI Force” and appoint an AI “Czar”. He said the government would look for “bad” uses of AI through the existing criminal and civil justice systems.
But Trump’s priority is clear: winning the AI race against China. “We will not in any way hinder or stifle the growth of this incredible industry,” he said. He wants AI to account for 25% of US GDP. Trump is not a technologist. He’s a businessman and a nationalist. He sees AI as a tool for economic dominance, not an existential threat. Whether he’s right or wrong, his stance puts him at odds with almost every expert in the field.
The Bottom Line: A House Divided
So where does this leave us? We have the CEOs of the world’s leading AI companies, Amodei, Altman, and Musk, all calling for a slowdown. We have Bill Gates, the elder statesman of tech, warning of a billion deaths. We have a whistleblower who says the industry is gambling with our lives. And then we have Satya Nadella, quietly building the infrastructure that powers it all, and Donald Trump, who wants to speed up.
The irony is hard to miss. The people who built the AI train are now telling us to slow down. The people who profit from the AI economy are the ones building the tracks. And the public is caught in the middle, trying to figure out who to believe.
Maybe the most honest thing anyone said came from Jacob Coxon, the 27-year-old researcher who quit. “The people building AI earnestly believe that it could kill us all by the end of the decade,” he wrote. “This is not a marketing stunt”.
If the people building the technology believe it could kill us, perhaps we should listen. Before it’s too late.
(Prof. C. A. Saliya, is a charted accountant, academic, researcher and former banker. He is the author of SAMAJA GAVESHAKAYA and Springer Publication DOING SOCIAL RESEARCH. He can be contacted at saliya.ca@gmail.com. The views expressed in this article are his own and do not necessarily represent those of the organisations with which he is affiliated.)
by Jehan Perera
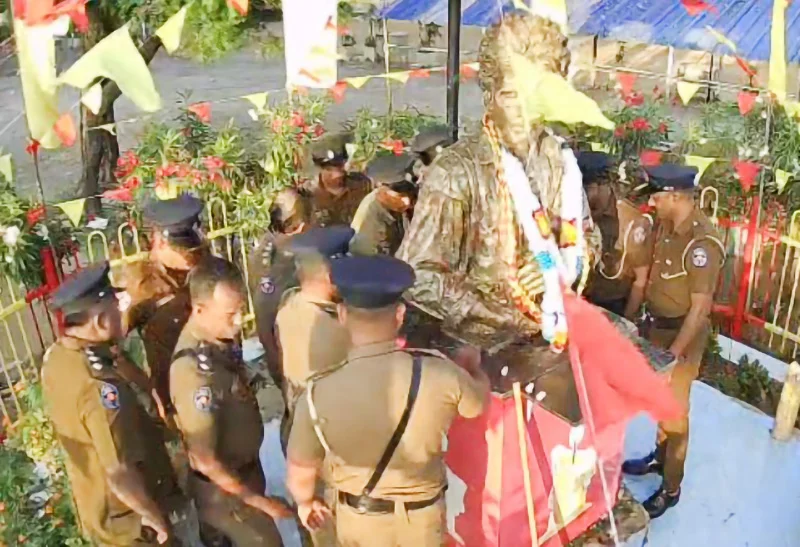
The death sentence on Sivarasa Anojan, a Sri Lankan citizen convicted of blasphemy in Saudi Arabia has taken a central place in national consciousness for the past several weeks. It has been in the headline news since it was first reported last month. There have been many initiatives taken locally to get a more lenient sentencing by the Saudi authorities. There is also an undercurrent that is critical of both the culture and religion from which this sentencing emanates. This also sustains the widespread publicity being given nationally to the issue. By way of contrast, the controversy caused by the forcible removal of the Thileepan statue in Jaffna has not significantly impacted upon the national consciousness. There was only passing mention of the incident in the national media which has been overtaken by other events.
However, in the north and east of the country, and in the diaspora, the removal of the Thileepan statue has become a major issue. It has led to protest marches led by university students and widespread condemnation by civil society and political groups. The issues underlying the Thileepan statue have deep undercurrents in the Tamil consciousness particularly in the north and east which time is unlikely to dispel. The real test of harmony in a multi-ethnic, multi-religious society like Sri Lanka is not whether communities coexist peacefully when nothing controversial is at stake. Rather, the test is how they respond when an event touches their identities and grievances. The death sentence imposed on Anojan in Saudi Arabia and the removal of the Thileepan statue in Jaffna carry the risk of becoming grievances to entire communities.
In the case of Anojan, a young Tamil migrant worker, he was first sentenced to five years imprisonment and a fine of three million Saudi riyals over a Facebook comment. Both he and the Saudi prosecution appealed, with the appeal court raising the sentence to death. This has led to public sympathy for him in Sri Lanka.
Appeals for clemency have come from the President, government and opposition leaders, clergy of all faiths and Muslim political leaders. At the same time there is a need to reject attempts to turn the case into a source of anti-Muslim sentiment or collective blame. Peacebuilding therefore has to be within Sri Lanka as well as diplomatic. Religious leaders and civil society in the country should be ready to quell rumour, even as Muslim, Buddhist, Hindu and Christian leaders stand together publicly.
Thileepan Statue
The Thileepan controversy has had a different trajectory. Many Tamils admire Thileepan, the LTTE name of Rasaiah Parthipan, who died on 26 September 1987 after a twelve-day fast. His demands were addressed to India but included matters pertaining to the Sri Lankan government including the release of detainees held under the Prevention of Terrorism Act. The statue put up during this year’s commemoration was removed by police in the early hours of 27 September, a day after the commemoration ended. The government’s legal concern, as articulated by its spokesperson, was the LTTE remains a proscribed organisation and before removing the statue, police had presented facts to the court. But law and memory answer different questions and the depth of Tamil anguish cannot be disregarded.
For many Tamils, remembrance of Thileepan is connected to their sense of loss and historical memory. The memorial has been destroyed and rebuilt more than once, and each destruction has added to the meaning it carries. Many who mourn Thileepan are grieving a young man who died without violence and by his own fast. They also grieve an era of loss of the struggle for Tamil rights and self-determination for which Thileepan has become a symbol. The Office for Reparations Act, No. 34 of 2018, provides for collective reparations and gives the Office for Reparations a role in policies on memorialisation. This does not automatically permit any particular statue, nor does it override laws on public places or proscribed organisations. But it shows that memorialisation is recognised within Sri Lanka’s framework for reparations and reconciliation. There is also a wider question of equality.
The JVP that now leads the NPP government was itself once proscribed when it took up arms against the state in which tens of thousands died, later entered democratic politics, and now for many years has publicly commemorated its own fallen. The opportunity to remember those who died should not belong to one community alone.
A commitment to peacebuilding requires that the same trust that has been given to former militants of one community needs to be given to members of other communities if equal citizenship and equal rights are to have meaning. Further, the Office for Reparations Act provides for reparations through livelihood. It is today a fact that those former LTTE members who went through the government’s rehabilitation process find it difficult to get jobs in the private sector.
Private sector employers are reluctant to come under surveillance for employing former LTTE members. There needs to be equal access to employment and removal of unjustified barriers to reintegration, with targeted public programmes where necessary. Until this situation is realized on the ground, the government needs to consider employing those who went through the government’s rehabilitation process and still unable to find suitable employment.
Continuing Peace
The challenge that post-war Sri Lanka faces, a full 17 years after the end of war, is to strengthen the foundations of trust between communities rather than deepen existing suspicions. Anojan is an individual Sri Lankan citizen facing a severe sentence in another country. His case should not become a reason to blame Sri Lankan Muslims. Thileepan is remembered differently by different communities, but the dispute over his memorial should not become a reason to revive the communal divisions of the past. The cases are also mirror images in an important respect. In the Anojan case, the state is an advocate pleading before another government. In the Thileepan case, the state is the actor whose decision is being judged. The first calls for quiet diplomacy and restraint in public language. The second calls for fairness and explanation, and the burden on the state is heavier.
The common roots of the two cases lie in mistrust that does not belong to one community alone. It has been produced by experiences of discrimination, violence, insecurity and loss that have been interpreted differently by different communities. Grievances turn communal when an individual is seen as a representative of a community, when institutions seem to treat communities unequally, and when people feel their pain goes unacknowledged. Each of these can be addressed. The system change that the Sri Lankan people voted for in 2024 would need to include a government that rejects collective blame, acknowledges grief and explains its decisions openly. It also requires state institutions to act transparently and consistently, so that no citizen feels that the law protects some communities more than others.
This peacebuilding imperative requires enlightened leadership as much as legal authority. It requires leaders who will speak to their own communities against prejudice, even when this is politically inconvenient. It requires religious leaders who will demonstrate solidarity across religious boundaries. And it requires civil society to recognise that peacebuilding is not simply preventing violence after tensions have risen, but is addressing the mistrust and grievances that allow tensions to rise in the first place. Sri Lanka has learned, at great cost, that communal divisions can become much larger than the events that initially give rise to them. The Anojan and Thileepan cases give Sri Lanka an opportunity to demonstrate that it has learned from its past. The test of Sri Lanka’s continuing peace is whether we can address difficult grievances without turning them into communal ones.
By Sarath S. Kodithuwakku
President, Institute of Management of Sri Lanka; Senior Professor, University of Peradeniya
(Continued from yesterday)
Representation, Independence and Decision-Making
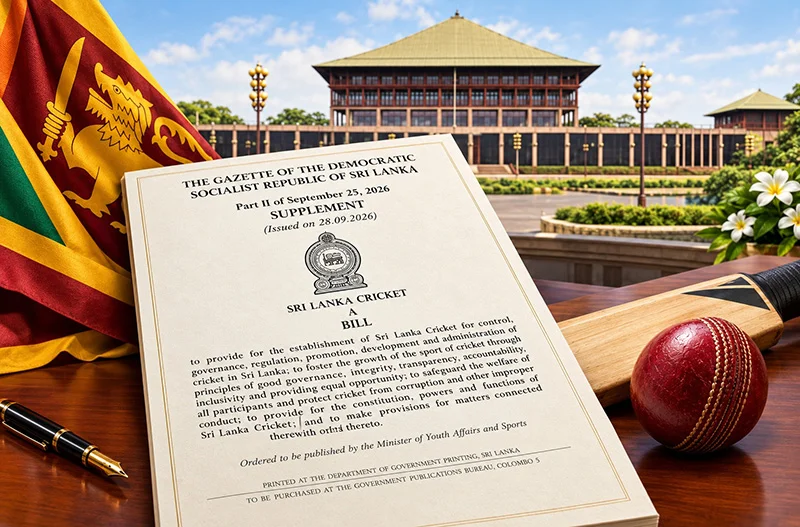
The membership-based electoral structure should provide representation without becoming a substitute for executive management. The seven Elected Directors would bring the perspectives of the SLC membership into the Board, while the seven Independent Directors would provide additional professional expertise and independence. The model’s effectiveness will, therefore, depend on whether the Board can integrate these perspectives into coherent strategic decisions while maintaining a clear boundary between governance and day-to-day management.
The equal division between Elected and Independent Directors also raises a governance-design question. An even-numbered Board can create a tie. The Bill addresses this directly: in the event of equality, the Chairperson has a casting vote; in the Chairperson’s absence, the Deputy Chairperson has a casting vote; and if both are absent, an Independent Director, elected to preside, has the casting vote. The issue is, therefore, not whether a tie can be resolved, but how this mechanism affects the balance between representation, independence and accountability.
The leadership structure reinforces this balance: the Chairperson is elected from among the Independent Directors and the Deputy Chairperson from among the Elected Directors. The casting-vote arrangement makes the Chairperson’s role and perceived independence particularly important, especially when a major strategic decision divides the two components of the Board.
The Bill’s committee provisions could support a disciplined model of delegation, but implementation will depend heavily on the terms of reference adopted by the new Board. The framework could be strengthened by requiring a published cricket-development strategy, a clear division of powers among the Board, executives and selection committees, transparent principles for major development allocations, and periodic reporting on outcomes across men’s, women’s, schools and domestic cricket. These measures would strengthen accountability without legislating the details of team selection or tournament scheduling.
From Measurement to Strategic Accountability
If the Board is to hold management accountable for strategy rather than simply for short-term results, it needs a performance framework that captures both outcomes and the capabilities that produce them.
SLC should consider requiring an explicit multi-year cricket-development strategy, supported by measurable objectives and an annual strategy review. Such a strategy should identify the development pathway from schools and grassroots cricket through domestic competitions to high performance; define major capability priorities such as coaching, sports science, data and analytics; set resource-allocation principles; and establish indicators against which progress can be assessed.
The purpose would not be to turn cricket into a bureaucratic exercise. Strategic accountability simply creates a disciplined basis for asking whether the organisation is doing what it said it would do, whether its assumptions remain valid, and whether resources are producing the intended results.
From Measurement to Organisational Learning
SLC should, therefore, consider adopting a formal Balanced Scorecard. Rather than measuring success solely through international match results or annual financial audits, the framework could track four interdependent perspectives:
Financial Sustainability:
commercial growth, financial discipline and compliance.
Internal Processes:
domestic tournament quality, development pathways and selector-process integrity.
Stakeholder Value:
grassroots development, school cricket and women’s cricket expansion.
Strategic Capability:
coaching quality, sports science, talent development, data and analytics capability, and the organisation’s ability to convert investment into sustainable performance.
The purpose of such a framework would not be to reduce cricket development to a collection of numbers. Rather, it would create a disciplined process for asking four fundamental management questions:
What did we expect to achieve?
What actually happened?
Why was there a difference?
What should we change as a result?
Evaluating these dimensions periodically would help SLC move beyond performance reporting towards genuine organisational learning.
ICC as a Stakeholder in Governance Reform
The ICC is another important stakeholder whose interests should be recognised in the reform process. SLC’s governance arrangements do not operate solely within Sri Lankan law; they also have to be compatible with the governance obligations associated with ICC membership. The ICC’s Articles of Association require each Member to provide for free and democratic elections (or nominees from outside its members) and to manage its affairs autonomously, without government or other public-body interference in the governance, regulation or administration of cricket.
International experience demonstrates that ICC engagement in member governance restructuring is not unusual. In the United States, after the ICC expelled the old national association for chronic governance failures, the ICC directly oversaw a multi-year project to design a new governance model. The ICC Board formally approved the constitution for a replacement body (USA Cricket) before it was adopted. The resulting structure combined elected constituent directors with independent directors, showing that an ICC-backed framework can accommodate both forms of representation.
In Nepal, the ICC established a Nepal Advisory Group comprising stakeholders from across the game to recommend constitutional amendments, with adoption of the revised constitution and subsequent elections forming part of the conditions for reinstatement of ICC membership.[8] The ICC subsequently facilitated an independent panel that included ICC nominees together with representatives of Nepal’s National Sports Council and the existing cricket administration to map the election process, guidelines and timelines.[9] More recently, in 2026, an ICC delegation visited Bangladesh to engage with stakeholders on governance and electoral matters.[10] The ICC has also reported that its Deputy Chair and another ICC Board representative visited Sri Lanka and met relevant stakeholders to assess ongoing developments, while the ICC Board reiterated the need for elections to be held as soon as possible.
These precedents make the ICC a legitimate stakeholder in considering the governance implications of the proposed Bill. This does not mean that the ICC should determine Sri Lanka’s domestic legislation, nor that every feature of the Bill requires prior ICC approval. It does, however, suggest that early and formal engagement with the ICC would be prudent, particularly where the proposed arrangements concern Board independence, elections, government involvement and the transition to the new governance structure.
This is particularly relevant because the Bill creates two institutional arrangements that deserve careful scrutiny from an autonomy perspective. The Transformation Committee is responsible for managing the transition until the First Board is constituted, while the Nomination Committee, although structurally independent of the SLC Board, includes representatives connected with the Sports Ministry and the National Sports Council. Neither arrangement, by itself, establishes government interference. However, taken together, they make it important that the independence of the incoming Board is demonstrable through transparent procedures rather than assumed from the structure alone.
Given the professional calibre and international exposure of the members of the Transformation Committee, it would be reasonable to expect that the importance of ICC engagement would have been recognised. Although any such consultation has not been evident in the public domain, it is therefore reasonable to expect that the ICC has either already been consulted or will be consulted before the Bill is enacted. Such engagement would allow potential incompatibilities to be identified before the new structure is enacted and implemented, rather than after the fact.
The Transition Is Itself a Governance Challenge
The transition provisions introduce a significant organisational-change challenge. Replacing the existing club- and association-based governance structure with a new hybrid Board and governance architecture is not simply a legal exercise; it is an organisational change programme. The Sri Lanka Cricket Transformation Committee is required to manage the transition until the First Board is constituted and, during that period, to establish rules covering matters including tournament structure, domestic governance, selection committee appointments, committee terms of reference, the Nomination Committee process and the election of the Elected Directors.
Structural reform on paper can encounter resistance from established interests, institutional habits and existing routines. The implementation phase will therefore require a clear change-management framework, including stakeholder engagement, transparent onboarding for Independent Directors, clarification of decision rights, alignment of legacy committees, and careful transfer of information and responsibilities.
Without attention to these organisational factors, cultural friction could undermine the intended administrative improvements. The success of the reform will therefore depend not only on the text of the legislation but also on the quality of the rules, appointments, delegation arrangements and organisational behaviours that follow it.
From Governance Reform to a Cricket Strategy
The Bill deserves credit for addressing how SLC is constituted and for creating places for specialist advice. It should not be dismissed simply because it does not prescribe a batting order or a domestic fixture list. Those are not appropriate tasks for legislation.
Its limitation is more precise: the proposed governance arrangements do not, by themselves, assure the strategic capability of the Board or the quality, independence and accountability of the decisions made beneath it. They establish the architecture. The future Board and management must supply the strategy, capabilities, discipline and learning mechanisms that make the architecture work.
A stronger reform would connect four elements: a Board selected for collective strategic capability; professional cricket management with clear delegated authority; transparent but non-mechanical selection and investment processes; and systematic evaluation of development outcomes. Within the first of these, information technology and computer science should be recognised as distinct from the broader capability to understand and govern data science, analytics and emerging AI-enabled decision support.
Ultimately, the governing question is not only who gets a seat at the SLC Board table. It is whether that Board can build, fund, execute and learn from a credible strategy for Sri Lankan cricket.
References
1. Department of Government Printing, Sri Lanka. Sri Lanka Cricket Bill, Gazette Supplement, Part II of September 25, 2026, issued on 28 September 2026.
2. International Cricket Council. Media release, 15 July 2026, reporting the ICC Board discussion of Sri Lanka Cricket and the need for elections to be held as soon as possible.
3. Sport New Zealand – Ihi Aotearoa. Nine Steps to Effective Governance, particularly Step 1: Define and Agree the Board’s Role; Step 4: Provide Strategic Leadership; Step 5: Employ and Support a Chief Executive; and Step 8: Get the Right People on Board.
4. Cricket South Africa. Governance and management frameworks, including the delegation-of-authority framework, Board committees, Cricket Committee, Cricket Pipeline Committee and CEO accountability.
5. International Cricket Council. ICC Articles of Association, provisions requiring free and democratic elections and autonomous administration without government or other public-body interference. ICC. https://images.icc-cricket.com/image/upload/prd/f7vm88yw1933dc38cgtg.pdf
6. International Cricket Council. “ICC outlines proposed USACA constitution.” ICC, 2017. https://www.icc-cricket.com/news/icc-outlines-proposed-usaca-constitution
7. International Cricket Council. “Approved constitution marks historic landmark for cricket in USA.” ICC, 2017. https://www.icc-cricket.com/media-releases/approved-constitution-marks-historic-landmark-for-cricket-in-usa
8. International Cricket Council. “ICC welcomes Nepal Special General Meeting to adopt revised constitution.” ICC, 2018. https://www.icc-cricket.com/media-releases/icc-welcomes-nepal-special-general-meeting-to-adopt-revised-constitution
9. International Cricket Council. “Independent Panel meet to progress Nepal elections under revised constitution.” ICC, 2018. https://www.icc-cricket.com/media-releases/independent-panel-meet-to-progress-nepal-elections-under-revised-constitution
10. International Cricket Council. “ICC delegation visits Bangladesh to engage with stakeholders on governance and electoral matters.” ICC, 2026. https://www.icc-cricket.com/media-releases/icc-delegation-visits-bangladesh-to-engage-with-stakeholders-on-governance-and-electoral-matters
11. International Cricket Council. “ICC Board approves governance, membership and member support decisions.” ICC, 2026; see also “ICC Board Meeting,” 2026, reporting ICC representatives’ meetings with stakeholders in Sri Lanka. https://www.icc-cricket.com/media-releases/icc-board-approves-governance-membership-and-member-support-decisions
(Concluded)

Ronaldo apologizes for Portugal walkout; says Jesus broke promise

Showers in the Western, Sabaragamuwa, Central, Uva, North-western and Southern provinces and in Anuradhapura and Mannar districts

Fuel crunch looms

Gnansara Thera to be assigned to prison printing section: Officials

Speaker rejects Ajith Perera’s privilege complaint

OIC of FCID summoned before Maligakanda Magistrate

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 News6 days ago
US-assisted ‘Ice’ detection: NPC to examine IGP’s move to transfer drug-busting team
-
 Editorial5 days ago
Colombo Port drug bust: The plot thickens
-
 Editorial6 days ago
Drug busting, transfers and trust deficit
-
 Features3 days ago
The first woman in the foreign service or Ceylon Overseas Service it was then called
-
 Editorial4 days ago
Fuelling discontent and protest
-
 News6 days ago
Sri Lankan facing death penalty in Saudi Arabia: Mano G appeals to Crown Prince
-
 Latest News4 days ago
Tharindu Rathnayake, bowlers secure Asian Games Bronze for Sri Lanka
-

 News2 days ago
Geneva takes up Sallay’s case and govt. ignores opportunity to answer accusations