News
Pulling back from the precipice: A Pathfinder perspective

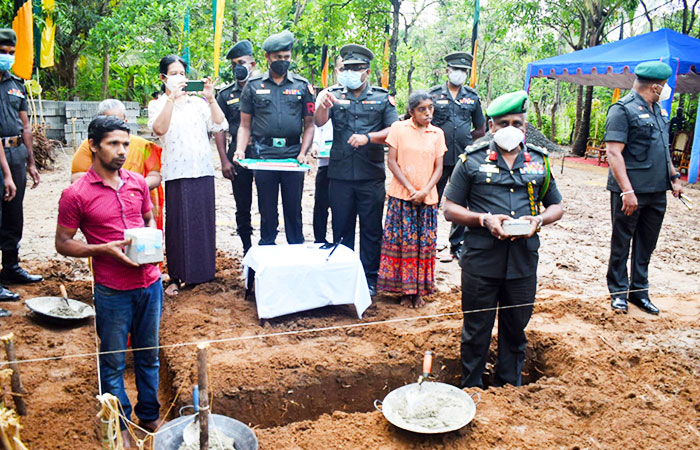
The way out of Sri Lanka’s most challenging external financing crisis is to negotiate an arrangement with the IMF and agree on a preemptive debt restructuring, Pathfinder Foundation has said in a media statement.
An IMF programme could include strengthening the government’s revenue base (widening the tax base and improving tax administration); improving the primary balance in the budget (revenue – (expenditure-interest payments)); proactive, data-driven and non-interventionist monetary policy; a flexible and realistic exchange rate policy to assist in building up external reserves; commercialisation of SOE operations, including full cost-recovery in the pricing of electricity and fuel, restructuring of the CEB and the CPC, the implementation of the Statements of Intent and addressing the losses being incurred by SriLankan Airlines, the Foundation said.
Pathfinder Foundation said that the Gross Official Reserves have declined to USD 1.6 bn as at end-November. Repayments over the subsequent 12 months amount to about USD 7 billion.
“The authorities have responded with import and capital controls as well as a fixed exchange rate based on moral suasion by the CBSL and rationing of foreign exchange by the commercial banks. This has resulted in a scarring of the economy which will inevitably have an adverse impact on growth, employment and incomes. Inflation is rising and is on the verge of reaching double digits and shortages constantly emerge of essential goods and services,” the Foundation said.
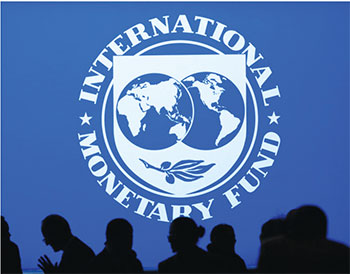 The Pathfinder statement in full: “The Road Map, presented by the CBSL, identified a number of potential sources of debt- and non-debt-creating inflows to fill the external financing gap. The securitisation of remittance flows has been added to the menu of options recently. However, to date there has been an alarming depletion of external reserves and an inexorable increase in the external financing gap.
“If the authorities have clear visibility of sufficient inflows to arrest the steady deterioration in the country’s external position, one can be hopeful of a turnaround to avoid the possibility of a debt default which would greatly amplify problems, such as rising inflation; pressure on exchange and interest rates; losses in the real value of incomes; decline in business confidence; and disruption to the supplies of basic goods and services. If the anticipated inflows are not forthcoming in sufficient quantities to fill the external financing gap, there will be no option but to turn to the IMF to avoid further scarring of the economy and creating greater shortages of essential goods and services.
“It is extremely unlikely that it would be possible to obtain IMF assistance without a debt rescheduling as the Fund does not support countries where the debt is considered unsustainable. Equally, it is not practical to reach agreement on debt restructuring without an IMF programme. So, the twin pillars of the way forward would need to be negotiating an arrangement with the IMF and agreement on a preemptive debt restructuring.
“Attempting to undertake stabilisation of the economy without the cushion of financing that can be mobilised through an IMF programme would be like performing on the high-trapeze without a safety-net. There needs to be a less painful blend of adjustment and financing. However, it must be highlighted that pain cannot be avoided. An IMF programme would impose significant burdens on the people. The main thrust of this article is that this pain would be less than the severe dislocation that is already being caused by squeezing the economy to make up for the dollar illiquidity. The conditionality attached to IMF programmes are intended to stabilise the economy (contain inflation and balance of payment pressure) and improve its creditworthiness.
“An IMF programme could include, inter alia, the following: strengthening the government’s revenue base (widening the tax base and improving tax administration); improving the primary balance in the budget (revenue – (expenditure-interest payments)); proactive, data-driven and non-interventionist monetary policy; a flexible and realistic exchange rate policy to assist in building up external reserves; commercialisation of SOE operations, including full cost-recovery in the pricing of electricity and fuel, restructuring of CEB and CPC, the implementation of the Statements of Intent and addressing the losses being incurred by SriLankan Airlines.
“An IMF Extended Fund Facility can provide balance of payment financing of up to USD 1 bn per year for three years. The amount made available would be calibrated according to the strength of the reforms undertaken. An IMF programme would also unlock direct budgetary support from the World Bank, Asian Development Bank and possibly a few bilateral donors (over and above their usual project loans). Both balance of payments and budgetary support are most urgently required for the twin deficit Sri Lankan economy. Based on indications in 2020, up to USD 2 bn in all can be mobilised through these sources, depending on the strength of the reforms undertaken. Engagement with the IMF will also transmit positive signals to both investors and creditors, both at home and abroad. It can also pave the way for an eventual upgrading of the sovereign rating, which would improve the prospect of attracting foreign investment and credits.
“The second pillar, preemptive restructuring, must also be pursued concurrently with negotiations with the IMF. Not only can this facilitate the obtaining of a Fund programme but it can also create some leeway to stabilise the economy and place it on a path of sustained growth. Debt restructuring can be achieved through: extending maturities; modifying coupon (interest) rates; and hair-cuts on the principal (write-downs). One or more of these modalities can be used to reach an agreement with creditors that places Sri Lanka’s debt servicing on a sustainable path. Ideally, about a 3-year window should be created where debt servicing is suspended. This can release a very substantial amount of scarce foreign exchange to finance imports. The impact on growth, employment and incomes would be materially positive. In considering debt restructuring, it is important to realise that the most significant usual downside is a loss of access to international capital markets. In Sri Lanka’s case, this has already happened with the downgrading of the sovereign rating. So, the most important disadvantage is no longer a factor. Another concern relates to the impact on domestic holders of USD denominated sovereign debt, mainly banks. A mitigating factor is that a significant share of these holdings have been bought at a discount from the secondary markets. In other countries, Central Banks have exercised regulatory forbearance to assist financial institutions which have required such support to repair their balance sheets.
“It must, however, be recognised that it could take 4-6 months to negotiate an IMF programme and a preemptive debt restructuring agreement. The present trends in external reserves on the one hand and net drains on foreign currency on the other indicate that bridging finance is required to meet obligations over the next 6 months to avoid a debt default. The package of assistance offered by India is an encouraging start and needs to be finalised as soon as possible. It has to be supplemented by financing from other friendly countries, like Japan. There is scope for India and Japan to work together to support Sri Lanka at this critical juncture. Their willingness to step forward is likely to be greater, if it is known that Sri Lanka has taken a decision to approach the IMF. While our development partners will be wary of having to make an open-ended commitment, they are likely to find bridging finance more palatable.
Time has almost run out. Urgent, focused and pragmatic attention to these pressing issues is of paramount importance. An IMF programme can be at the heart of a medium-term strategy to overcome the current challenges and give Sri Lankans greater hope about the future prospects of the economy.”


… warn of dire consequences
A group of trade unions and civil society groups has requested President Anura Kumara Dissanayake to abandon his government’s controversial plan for the proposed tripartite management of the EPF.
The group has told the President: “We strongly object to the government’s plan to transfer the EPF to a tripartite board—jointly promoted by the Employers’ Federation of Ceylon (EFC), International Monetary Fund (IMF) and the International Labour Organisation (ILO)—and to increase the investments of those funds within private equity and debt markets.
“While the EFC and the government jointly project this plan as a ‘modern governance framework’, it poses a serious threat to the EPF’s financial stability, fiduciary conduct, and returns to workers’ life savings, with severe consequences for broader macroeconomic stability. Rather than replacing the corruption existing in the public sector, this tripartite framework paves the way for a corporate takeover of the EPF. Through this, the fund is exposed to unlawful business practices such as insider trading using internal information of EPF investments, conflicts of interest and corporate bailouts of unstable private companies.
“Sri Lanka’s corporate sector has a tremendously negative track record, which you alluded to during your victorious election campaign in 2024. This was recently unravelled by the multi-billion-dollar illicit capital flight through trade misinvoicing, which your administration is now actively working to curb in the imports sector.
“The recent banking sector fraud exceeds Rs. 13 billion; widespread corporate tax evasion destabilised the fiscal position (Sri Lanka Auditor General’s Department Annual Reports) and consequently inflated the tax burden on the general public. The EFC has found it convenient to remain silent about these crimes, possibly assuming that their silence would preserve their social standing. Considering this inherent corruption within Sri Lanka’s corporate sector and its disregard to the living standards of the general public, there is no realistic basis to integrate corporate interests to actively manage the EPF. The corporate sector of Sri Lanka has not developed sufficiently on technical and ethical grounds to safely entrust the largest retirement savings pool in the country. The EPF is a captive fund that has no mechanism for the owners to divest if the management is corrupt. This further increases the possibility of corporate fraud when the management of the fund is jointly held with the corporate sector.
“Furthermore, during the recent public discussion with trade unions, Deputy Minister of Finance Dr. Anila Jayantha pointed out that the domestic debt restructuring (DDR) would inflict a loss of Rs. 600 billion to the EPF. Our independent calculations—formally submitted as an affidavit to the Supreme Court approved by the Federation of University Teachers’ Associations in 2024—reveal that nominal loss alone is Rs. 634.4 billion. When factoring in foreclosed reinvestment returns, the true loss skyrockets to Rs. 1,711 billion, wiping out 48% of the fund’s projected gross income for the 2023 – 2028 period. Under the pretext of safeguarding the banking system, this colossal robbery preserved high yields on government bonds held by commercial banks and high-net-worth individuals, subsequently reaping them astronomical profits. Now, the exact same plunder is rearing its head again disguised as a tripartite committee.”
“The main arguments supporting our resistance and viable alternatives for optimising EPF management directly under the Central Bank of Sri Lanka (CBSL), are outlined below.
“Objections to the government’s tripartite proposal:
1. The “International best practice and conflict of interest fallacies”
The government holds that tripartite management of pension funds is the “international best practice” and that there is a “conflict of interest” in CBSL managing the EPF. They are key pillars justifying government’s tripartite proposal.
These two positions are shockingly misleading given that four of the five largest pension funds in the world, in Norway, Japan, the U.S., and Singapore, are managed directly by state bodies or central banks. Therefore, ‘international best practice’ in pension fund management is the exact opposite of what the government and the IMF are proposing. We hence reject these baseless positions.
2. Corporate captivity and bailouts
It is clear that the EFC is desperately pushing for this proposal at a time of global uncertainty, to cushion the effects of the crisis and maximise gains. Under corporate influence within the proposed tripartite board, the private conglomerates can use the multi-trillion-rupee EPF to continue their unstable commercial operations without having to risk their own capital or savings to do so. This will severely erode the financial stability of the EPF and its returns.
3. Risk of front running
“Because the EPF is a colossal fund, its investment decisions can alter asset prices. This creates immense monetary value for the information generated by its investment decisions. Corporate representatives on the proposed tripartite board will be perfectly positioned to use this information to trade ahead of the EPF (front-running), buying assets cheaply and dumping them onto the EPF at inflated prices for guaranteed corporate gain, resulting in a reduction of returns to the EPF.
4. Unavoidable loopholes
“Presence of a separate group of investment analysts, trade union representatives and government officials within the proposed tripartite structure cannot prevent pre-market corporate access to EPF’s investment decisions. Investment proposals made by the analysts has to be first approved by the proposed tripartite committee, making it impossible to prevent corporate access to insider information on EPF investments.”
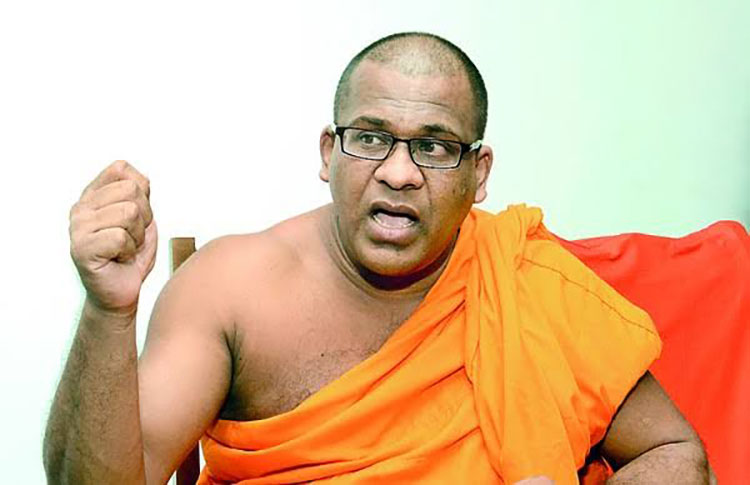
The Colombo High Court and Court of Appeal yesterday issued arrest warrants for the Bodu Bala Sena general secretary Galagoda Aththe Gnanasara in a case involving an alleged statement insulting Islam.
The arrest warrants were issued on Tuesday and Wednesday. The Court of Appeal issued an open warrant two weeks after the court rescinded the presidential pardon granted to the thera when he was serving a six-year term for contempt of court.
The Appeals Court also imposed a travel ban on the monk and ordered that the Controller General of Immigration and Emigration be informed of the restriction.
The case was taken up before Colombo High Court Judge Buddhika C. Ragala. Gnanasara Thera was not present when the case was called.
A medical report was submitted stating that Thera was unwell, while his sureties also failed to appear before court. His counsel, Asoka Weerasuriya, told court that his client wished to bring the case to an early conclusion and that representations had been made to the Attorney General in that regard.
However, after considering the submissions, the High Court judge said he was not satisfied with the medical report submitted on behalf of the accused. The court also noted the failure of the sureties to appear.
The judge subsequently ordered that Gnanasara Thera be arrested and produced before court.The Attorney General filed the case under provisions of the Penal Code, alleging that remarks made by Gnanasara Thera concerning the Holy Quran amounted to an insult to Islam.
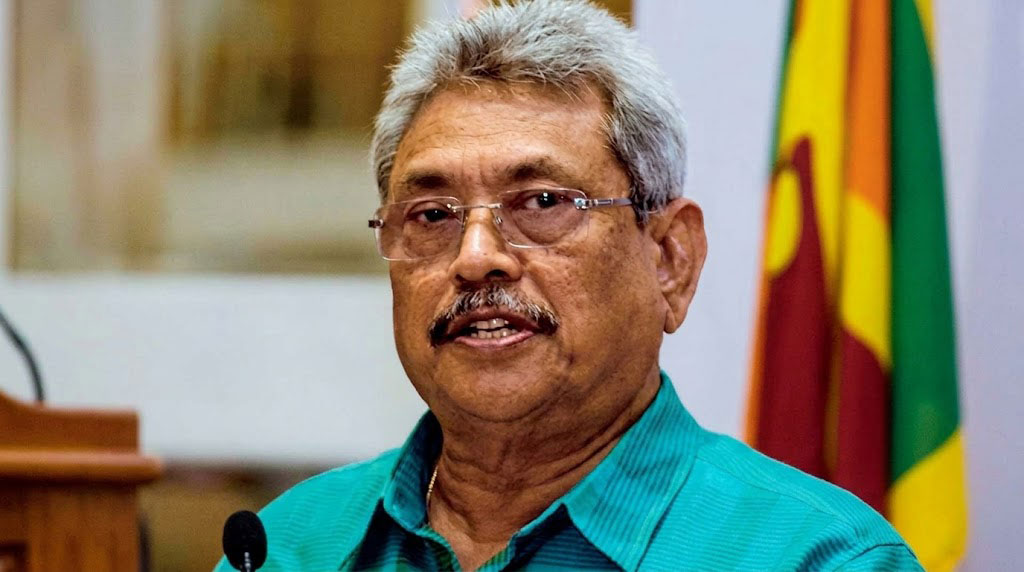
A two-member bench comprising Court of Appeal President Justice Rohantha Abeysuriya and Justice Sarath Dissanayake yesterday (1) dismissed a writ petition filed by former President Gotabaya Rajapaksa seeking judicial intervention to prevent his arrest under the Prevention of Terrorism Act (PTA) in connection with the ongoing investigations into 2019 Easter Sunday terror attacks.
The writ petition was rejected in limine.
In the petition, the former President cited Inspector General of Police Priyantha Weerasooriya, Criminal Investigation Department (CID) Director Shani Abeysekera, the Officer-in-Charge of the CID’s Special Investigations Unit and the Attorney General as respondents. The ex-President sought the court intervention after the arrest of former head of the State Intelligence Service (SIS) retired Maj. Gen. Suresh Sallay over the Easter Sunday attacks.
Since then , former Director of Directorate of Military Intelligence (DMI) has been named as a suspect.
Earlier, the Fort Magistrate’s Court imposed a travel ban on him in relation to investigations stemming from allegations made by Asad Moulana in the Channel 4 documentary on the Easter attacks.

Showers or thundershowers will occur in most parts of the island after 1.00 p.m.

Unions resist tripartite EPF management plan

Two arrest warrants issued for Gnanasara thera

CA dismisses GR’s writ petition against arrest

ADB-backed virtual net metering project faces policy contradiction

Media action group flays NPP over new anti-terrorism law

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Editorial6 days ago
Birth of a bad law
-
 News4 days ago
Police remove Thileepan statue in Jaffna
-
 News6 days ago
TIN mandatory for key transactions from Nov. 1
-
 Features4 days ago
The 22nd Amendment, constitutional recovery and illiberal slippage
-
 Features4 days ago
Of foreigners as CEOs of Lankan ventures
-
 News4 days ago
Sajith rejects Jt. Opp. protest sabotage claim; SJB TU chief demands remedial action
-

 Latest News2 days ago
Gold winner Tharanga gets brand-new Honda Vezel from SLAAJ
-
 Features3 days ago
Thailand’s biggest new global star …