Business
People’s Bank achieves LKR 92.7 billion in Consolidated Gross Income in Q1-2024

The People’s Bank reported total consolidated operating income of LKR 20.4 billion and post-tax profit of LKR 2.5 billion, for Q1-2024. Excluding the impact of exceptional adjustments in view of greater prudence considering current macro-economic circumstances, these figures on a normalized basis were otherwise LKR 28.4 billion and LKR 6.6 billion, respectively, reflecting a growth of 18.2% and 35.8%, People’s Bank press release said.
The release added: ‘Consolidated net interest income rose to LKR 16.1 billion during the quarter from LKR 15.3 billion in the same period 2023. On a normalized basis, excluding the impact of any exceptional items, consolidated net interest margins improved to 3.0% from 2.0% during 2023 reflecting the reducing term deposit cost of funding. Consolidated net fees & commissions amount to LKR 3.8 billion – representing a 14.7% growth on a like for like basis. Total consolidated operating expenses amounted to LKR 17.6 billion (2023: LKR 14.4 billion).
‘Total consolidated customers deposits touched LKR 2,808.3 billion (end 2023: LKR 2,745.2 billion) whilst net loans amounted to 1,845.4 billion (end 2023: LKR 1,823.8 billion). The impaired loan ratio also showed improvement relative to end 2023. Total consolidated assets reached LKR 3,264.5 billion at period end (end 2023: LKR 3,208.2 billion).
‘The Bank’s total Tier I and Total Capital Adequacy Ratios were 11.5% and 16.1%, respectively at March 31, 2024 (end 2023: 12.4% and 17.4%) whilst, on a consolidated basis, it was 12.9% and 17.2%, respectively (end 2023: 13.7% and 18.2%). The Bank’s solvency levels continue to remain sound. Further efforts to bolster its regulatory capital, including for the purposes of additional contingency, is currently in process.
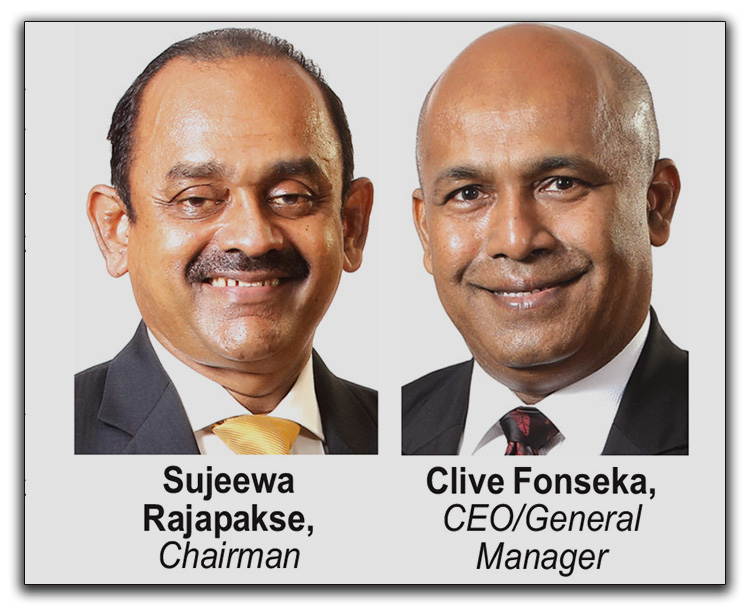
‘Commenting on the results of the Bank and the Group, the chairman of People’s Bank, Sujeewa Rajapakse, stated that: “We are pleased with the steadfast progress made by the Bank on many fronts even amidst interim pressures stemming from the yet ongoing – and likely to be soon concluded – debt restructuring initiatives of the government of Sri Lanka. We reasonably expect that these pressures will normalize in the near term with the support of all key stakeholders. Notwithstanding, the Bank has yet again demonstrated its strength, resilience and capacity to deliver positive growth across all core operating metrics even amidst such limiting circumstances.
‘Looking ahead, whilst navigating the challenges which naturally exists in a reviving macro-economic context – we remain focused on innovation, collaboration, and the drive for forward movement across all aspects of our business, ensuring that we continue to play our leading role in any and every way possible in the country economic revival”
‘Commenting on the results, the Bank’s Chief Executive Officer/ General Manager Clive Fonseka, stated that: In the face of unforeseen challenges, our team has once again demonstrated its resilience, adaptability, and unwavering commitment. Our first-quarter not only show cases our ability to grow amidst challenges but importantly, the strength and resilience of our business.’






Sri Lanka’s national economic discourse takes center stage today as the country’s premier private-sector body, The Ceylon Chamber of Commerce, hosts the Sri Lanka Economic & Investment Summit 2026 at the Shangri-La Colombo.
Convening on October 12 and 13, the two-day summit brings together an influential gathering of senior policymakers, international financiers, multilateral development partners, and private-sector captains to chart the island’s next phase of macroeconomic growth.
Held under the theme “Positioning Sri Lanka in a Changing Global Economy: Resilience, Reform, and the Future of Economic Policy,” this year’s forum marks a critical inflection point in the nation’s post-crisis trajectory.
As Sri Lanka shifts its emphasis from immediate financial stabilization toward sustainable, long-term expansion, the summit aims to address the structural imperatives necessary to secure high-impact foreign direct investment (FDI), deepen regional trade integration, and unlock emerging sectors of economic activity.
The core agenda over the two days focuses on building resilience across volatile global market cycles while executing targeted policy reforms. Key working sessions will examine:
Regional Value Chains & Trade Integration: Leveraging Sri Lanka’s strategic Indian Ocean geography to capture higher-value export flows and commercial linkages.
Energy & Infrastructure Transformation: Accelerating renewable energy integration and modernizing national utility policy.
Digital Economy & Public Modernization: Deploying digital technologies across public administration and financial services to enhance operational efficiency and transparency.
Sectoral Priorities: Modernizing healthcare infrastructure and agricultural value-addition to build a robust domestic economic base.
A defining feature of this year’s summit is the strong convergence between state policy and global commercial expertise. Keynote addresses and panel discussions will feature prominent leaders, including Prime Minister Dr. Harini Amarasuriya and T. Krishnakumar, Chief Executive Officer of Reliance Consumer Products Ltd.
They will be joined by senior delegations and policy experts from major global institutions, including:
= The Asian Development Bank (ADB)
= The International Finance Corporation (IFC)
= Standard Chartered Bank
= Zydus Lifesciences
The active participation of the country’s highest executive and legislative leadership across both days underscores a clear policy commitment to private-sector-led growth. By establishing a direct, high-level platform for dialogue between investors and policymakers, the Ceylon Chamber’s summit seeks to refine regulatory frameworks, improve the ease of doing business, and establish a clear, predictable environment for capital formation in the years ahead.
Microsoft and several other technology firms have been barred by the White House from hiring skilled international workers on a permanent basis through a widely used visa programme.
US Vice-President JD Vance on Thursday accused Microsoft alongside other firms of committing fraud through the use of the H-1B visa programme and a related process for workers from abroad to become permanent US residents.
Vance claimed that Microsoft, one of the most valuable companies in the US, has been effectively replacing American workers with “foreign indentured servants.”
Microsoft said most of the H-1B visas filed over the last financial year were for existing workers, who are paid the same as local staff.
“No company in the US has abused this system more than Microsoft,” Vance said.
He also made similar accusations about Adobe, Cognizant, Infosys, Tata, Wipro, HCL and Capgemini.
The US government will not process any new or pending Permanent Labor Certification Program (PERM) applications from Microsoft or the seven other companies, Secretary of Labor Keith Sonderling said during the same conference.
Sonderling said companies like Microsoft, as well as US universities, have turned into “visa mills” that were “flooding” the US with foreign workers.
The BBC has contacted all of the companies for comment.
The total number of H-1B visas, a precursor to anyone seeking to go through the PERM process, is capped at 85,000 per year.
A spokeswoman for Microsoft noted to the BBC that “the vast majority of Microsoft employees in the United States are Americans.” The company employs more than 200,000 people worldwide.
In response to emerging climate risks, the Commercial Bank of Ceylon has launched a proactive initiative through its Development Credit Department, to equip Sri Lanka’s agricultural sector against the potential impacts of the 2026 El Niño climate pattern.
Seeking to move the industry from reactive loss management to early climate preparedness, the Bank partnered with leading state universities to execute a two-part educational and technological intervention in September 2026.
The initiative comes at a critical juncture. Sri Lanka’s Department of Meteorology reported an 80% probability of El Niño conditions emerging between June and August 2026, with effects expected to persist through November and beyond. As highlighted by the Food and Agriculture Organization (FAO), El Niño acts as a risk multiplier for rural livelihoods, food production, and water supply.
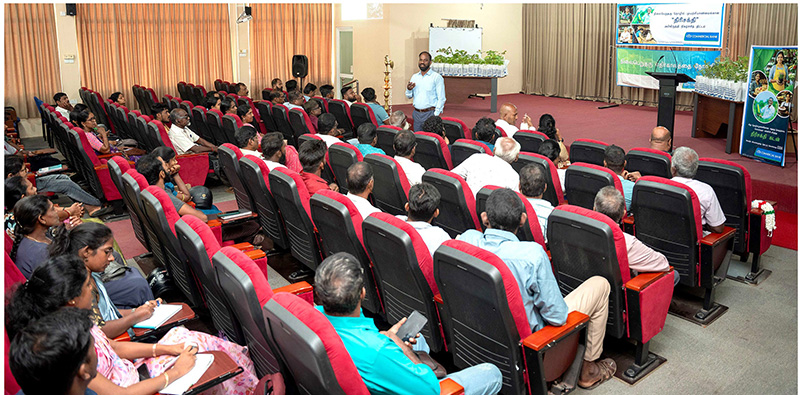
To mitigate these threats, the Bank’s initiative creates a collaborative network uniting academic institutions, agricultural extension services, technology providers, farming communities, and the financial sector. The awareness programme on El-Niño and its impact on agriculture was supported by 12 Commercial Bank branches, and engaged with more than 1,100 farmers at 15 diverse locations, including Vattapalai, Muththajankaddu, Palampas, Oddusuddan, Siyambalanduwa, Lindula, Neluwa, Kalawana, Pannala, Madampe, Mannar, Vavuniya and Kumalamunai.

Showers above 75 mm are likely at some places in the Western, Sabaragamuwa, Central, Southern, Uva and North-Western provinces and in Anuradhapura and Mannar districts.

New prison regulations for monks serving jail terms soon: President’s Office

CP alleges NPP has taken the blame for illegal US sanctions on Iranian vessels

Ex-Tiger witness claims Ekneligoda proposed to fire missile at MR’s plane

Chandrasekaran welcomes Indian stand of Katchatheevu

Alleged killer of couple apprehended

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Features4 days ago
The Sri Lankan who made Scottish history
-
 Features6 days ago
Preventing grievances from becoming communal
-
 Sports4 days ago
Nissanka absence opens door for Sri Lanka’s young guns
-
 News5 days ago
Gnansara Thera to be assigned to prison printing section: Officials
-
 News3 days ago
NDB fraud Rs 60mn more than reported
-
 News3 days ago
Removing monk’s robes matter for Sangha to decide: Mahanayake Theras
-
 Features4 days ago
Future of Sri Lanka’s state university system: Should it be shut down and reopened?
-
 News5 days ago
OIC of FCID summoned before Maligakanda Magistrate