Business
DFCC Bank forges ahead amidst a challenging environment


Financial Results for the year ended 31 December 2021
DFCC Group recorded a PAT of LKR 3.7 Bn.
Advances grew by LKR 64 Bn to LKR 366 Bn (21% growth)
Deposits grew by LKR 10 Bn to LKR 320 Bn (3% growth)
The DFCC Group comprises of DFCC Bank PLC (DFCC), and its subsidiaries – Lanka Industrial Estates Limited (LINDEL), DFCC Consulting (Pvt) Limited (DCPL) and Synapsys Limited (SL), the joint venture company – Acuity Partners (Pvt) Limited (APL) and associate company – National Asset Management Limited (NAMAL).
DFCC Bank PLC, the largest entity within the Group, reported a profit before tax (PBT) of LKR 4,326Mn and a profit after tax (PAT) of LKR 3,222 Mn for the year ended 31 December 2021. This compares with a PBT of LKR 3,398 Mn and a PAT of LKR 2,388 Mn in the year prior.
The Group recorded a PBT of LKR 4,859 Mn and a PAT of LKR 3,665Mn for the year ended 31 December 2021, compared with LKR 3,944 Mn and LKR 2,847 Mn, respectively, in 2020. All the member entities of the Group made positive contributions to this performance.
The basic earnings per ordinary share (EPS) of the Bank improved to LKR 10.14 for the year ended 31 December 2021 from LKR 7.83 for the comparative year 2020, recording an increase of 29%.
The Bank’s Return on Equity (ROE) improved to 6.55% during the year ended 31 December 2021 from 4.93% recorded for the year ended 31 December 2020. The Bank’s Return on Assets (ROA) before tax for the year ended 31 December 2021 is 0.91%, against a figure of0.78% for the year ended 31 December 2020.
Net Interest Income
The Bank recorded LKR 12,653 Mn in net interest income (NII), which is a 15% increase year on year. This contributed to an increase in interest margin from 2.53% in December 2020 to 2.66% in December 2021.
Other Operating Income
Due to travel restrictions imposed during the year to curb the spread of the pandemic, business momentum was noticeably negatively affected.
The Bank staff at Head office and across branch network working continuously over the year has helped the Bank to increase non-funded business. This effort was fruitful as it resulted in an increase in net fee and commission income to LKR 2,596 Mn for the year ended 31 December 2021, up from LKR 2,061 Mn in the comparative year. Other operating income has increased mainly due to increases in dividend income and gains on the sale of fixed income securities during the year ended 31 December 2021.
Impairment Charge on Loans and Other Losses
Impairment provisions for the year ended 31December 2021 was LKR 4,485 Mn compared to LKR 3,298 Mn in the year prior. The NPL ratio increased from 5.56% in December 2020 to 5.60% in December 2021. In order to address the current and potential future impacts of Covid-19 and other prevailing economic conditions on the lending portfolio, the bank has made adequate impairment provisions, as at 31 December 2021, by introducing changes to internal models to cover unseen risk factors in the present highly uncertain and volatile environment, including additional provisions made for the Bank’s exposure to risk elevated sectors.
Operating Expenses
The Bank’s operating expenses increased from LKR 7,387 million during the year prior to LKR 8,381 million during the year under review, primarily due to increases in transport costs, as result of special transport facilities provided to staff due to covid restrictions and non-availability of public transport, along with all other additional expenses incurred in keeping and maintaining a safe and healthy environment within the Bank’s premises, to support client engagements and servicing. During the year, the Bank also created multiple channels to enhance service delivery to customers through a strong digital drive, providing access to uninterrupted banking services during difficult times. This resulted in an increase in IT related expenses in order to support the infrastructure upgrades. However, the numerous process automation and workflow management systems introduced during the year under review helped to facilitate effective cost controls, which resulted in operating expenses being curtailed and managed at these levels.
Other Comprehensive Income
Investments in equity securities and treasury bills and bonds (fixed income securities) are classified as financial assets and their change in fair value is recorded through other comprehensive income. Accordingly, a fair value loss of LKR 36Mn and a net fair value loss of LKR 2,469Mn were recorded on account of equity and fixed income securities, outstanding as at 31 December 2021 respectively. Unfavourable movements in Treasury bill and bond yields resulted in the fair value loss of LKR 4,532 Mn during the year. A gain of LKR 2,062 Mn was recycled through the Income statement by disposing of selected Treasury bill and bond holdings, originally categorized under fair value through other comprehensive income (FVOCI), with the objective of cash flow management to support loans and advance growth in line with projections. The action also goes in tandem with the bank’s expectations with regard to the domestic interest rate trend, going forward.
Business Growth
Despite the challenging business environment, the Bank continued its growth strategy by increasing both its deposit and loan portfolios during the year ended 31 December 2021. The loan portfolio grew by LKR 63,991 Mn to record LKR 365,901 Mn compared to LKR 301,909 Mn as at 31 December 2020, recording an increase of 21%. The Bank’s deposit base also experienced a growth of 3%, recording an increase of LKR 9,834 Mn to LKR 319,861 Mn from LKR 310,027 Mn as at 31 December 2020. This resulted in recording a loan to deposit ratio of 114%. Further CASA ratio improved to 31.25% as at 31 December 2021. Funding costs of the Bank were also contained by using medium to long-term concessionary credit lines. When these concessionary term borrowings are considered, the CASA ratio further improved to 36.47% as at 31 December 2021.
DFCC Bank continued its approach to tap local and foreign currency related long to medium- term borrowing opportunities to facilitate lending to deserving segments of the market whilst maintaining a high-quality portfolio.
Equity and Compliance with Capital Requirements
In order to support future growth as a full-service retail bank, the Bank has consistently maintained a capital ratio above the Basel III minimum capital requirements. As at 31 December 2021, the Bank has recorded Tier 1 and total capital adequacy ratios of 9.31% and 13.03%, respectively which is comfortably above the minimum regulatory requirements of 8% and 12% including capital conservation buffer of 2%. The Bank’s Net Stable Funding Ratio was 122.43%, which is well above the regulatory minimum of 100%.
CEO Comment
“Ensuring that we run our business responsibly, delivering profit with purpose, DFCC Bank will always place our customers at the forefront of everything we do. As a customer centric, digitally enabled bank, we will continue to be a source of stability to our customers and deliver value through an unmatched, top-of-the-line customer experience.
In line with our stated vision, the Bank embarked upon implementing a state of the art, core banking system which went live in October 2021. Considering the magnitude and complexity of the implementation, we have had to face some unforeseen challenge and I take this opportunity to express our sincere thanks and gratitude to all our clients, who have been understanding and patient with us this year, as we continuously strive to ensure a more futuristic, digitally-enabled system for our clients.
Despite the unprecedented challenges faced due to the ongoing pandemic, staff of DFCC Bank have and will continue to work with commitment to combat the negative socio-economic effects that have impacted our customers and assist them through tailor made financial solutions. We will continue to introduce banking services that put safety and security at the forefront and ensure that our internal processes are aligned with these same principles to serve our customers better.
We have a strong asset base to be deployed, but nothing is more important than the loyalty we earn from customers, not just by keeping their money and their data safe, but by offering products and services that meet their financial needs and requirements. This loyalty generates both more predictable returns and keen insights, enabling us to continuously improve our services and exceed customer expectations.”
Business
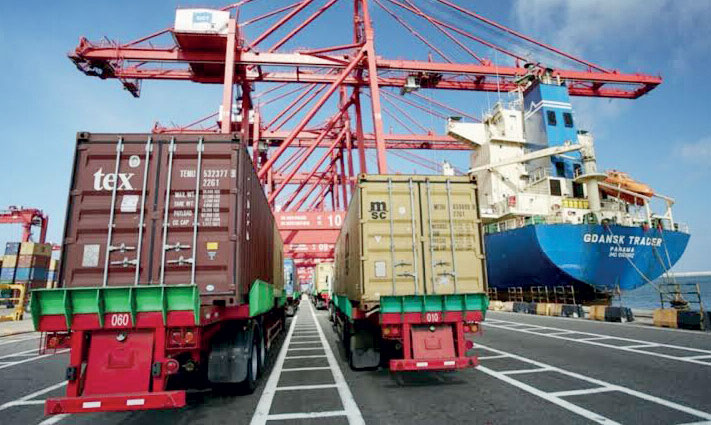
Cost-effective clearance of goods across borders to determine worth of Customs Paperless Declaration

By Ifham Nizam
The introduction of the Customs Paperless Declaration from October 1 could mark an important step in Sri Lanka’s efforts to modernise trade, but its real value will depend on whether it reduces the time and cost of moving goods through the country’s borders, Customs House Agents & Traders Association President Mohamed Niyas said.
Niyas warned that digitising Customs declarations alone would not necessarily translate into faster cargo clearance or lower costs for businesses.
‘Expecting a dramatic improvement in clearance speed under the present conditions is like expecting Ferrari performance from a Morris Minor configuration, he said.
For importers and exporters, the issue extends well beyond paperwork. Every additional hour or day that cargo remains in the clearance chain can have wider consequences for businesses, including increased port and storage-related costs, additional working-capital requirements, uncertainty over delivery schedules and disruptions to production and distribution.
Niyas said the competitiveness of Sri Lanka’s trading sector ultimately depended on how efficiently goods could move through the country’s border-clearance system.
‘The real bottleneck is not merely the absence of paper. It is the entire clearance ecosystem—the limitations of the existing ASYCUDA World system, excessive regulatory interventions by Other
Government Agencies, multiple approvals, physical examinations, manual interventions, fragmented processes and institutional constraints, he said.
He cautioned that unless these bottlenecks were addressed, there was a risk that the paperless initiative would merely digitise existing bureaucracy.
‘If these underlying constraints remain unchanged, there is a real risk that the new paperless system could become another “copy-and-paste road show”—where an old, complex clearance process is simply transferred onto a digital screen without fundamentally changing the process itself, Niyas said.
For businesses dependent on imported raw materials, machinery, components and other inputs, clearance efficiency can directly affect the wider supply chain.
Delays at the border can create uncertainty for manufacturers, distributors and retailers, while exporters can face difficulties meeting delivery schedules when imported inputs or export consignments are held up.
Niyas therefore argued that the success of the October 1 initiative should be judged by its impact on trade flows rather than by the number of declarations processed electronically.
‘Paperless does not automatically mean faster, he said. ‘Digitising a slow process does not make the process fast. It only makes the slow process digital.’
He said Sri Lanka needed to move towards what he described as “process-less Customs”—a system in which unnecessary procedures are eliminated rather than simply converted into electronic procedures.
Among the reforms he called for are simplification of Customs declarations and approval workflows, improvements to the functionality of ASYCUDA World, greater use of risk-based inspections and better integration of Other Government Agency approvals.
Niyas also called for the elimination of repetitive document submissions and physical endorsements, greater use of pre-arrival processing, sufficient capacity for digital document uploads and clearly defined service-level timelines for Customs and OGAs.
By Sanath Nanayakkare
As global attention has fixed on the high-level diplomatic choreography at the United Nations General Assembly in New York, a subtler, yet profound geopolitical signal was sent from Colombo, yesterday.
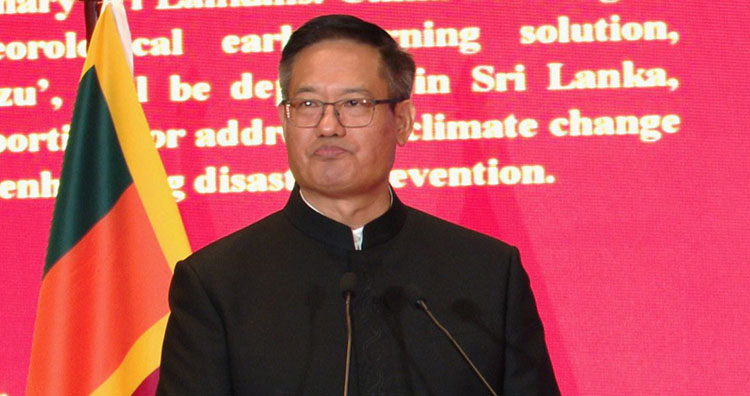
In a major address marking the founding anniversary of the People’s Republic of China, newly appointed Chinese Ambassador Wei Huaxiang chose to anchor bilateral relations not just in modern trade or infrastructure, but in a shared respect for Sri Lanka’s legacy of non-aligned independence.
By explicitly invoking Sri Lanka’s foundational role in the 1976 Non-Aligned Summit, Beijing was doing something unexpected in an era defined by fierce great-power rivalry: it was officially validating a small island nation’s right to maintain an independent foreign policy stance.
The Strategic Value of Independence
For decades, nations caught in the crosshairs of major-power competition have faced intense pressure to pick sides. Yet, Ambassador Wei’s embrace of Colombo’s non-aligned tradition signaled a different diplomatic playbook. Instead of demanding alignment, Beijing was framing its partnership as a reliable counterbalance to regional pressures. By honouring Sri Lanka’s diplomatic autonomy, China was effectively reassuring smaller economies that sovereign independence and robust economic cooperation can coexist.
Beyond Ports and Industrial Zones
This diplomatic framing reframed the narrative surrounding major collaborative ventures like the Colombo Port City and Hambantota Port. While foreign analysts often view these projects exclusively through the lens of strategic rivalry, Beijing’s diplomatic messaging tied them back to a historical ethos of solidarity—evoking memories of the 1952 Rubber-Rice Pact.
By marrying economic projects with a stated respect for non-alignment, China is positioning itself as a steadfast stakeholder that respects Sri Lanka’s internal agency during difficult economic and political seasons.
As both nations look toward major milestones in 2027—including the 70th anniversary of diplomatic ties—this nuanced diplomatic move revealed how historic traditions are being leveraged to navigate modern multipolar realities.
For global observers, the takeaway was clear: in the shifting architecture of Asian geopolitics, respecting a nation’s historical neutrality may just be the most effective way to secure a lasting partnership, a diplomatic masterclass that Ambassador Wei Huaxiang executed in style.
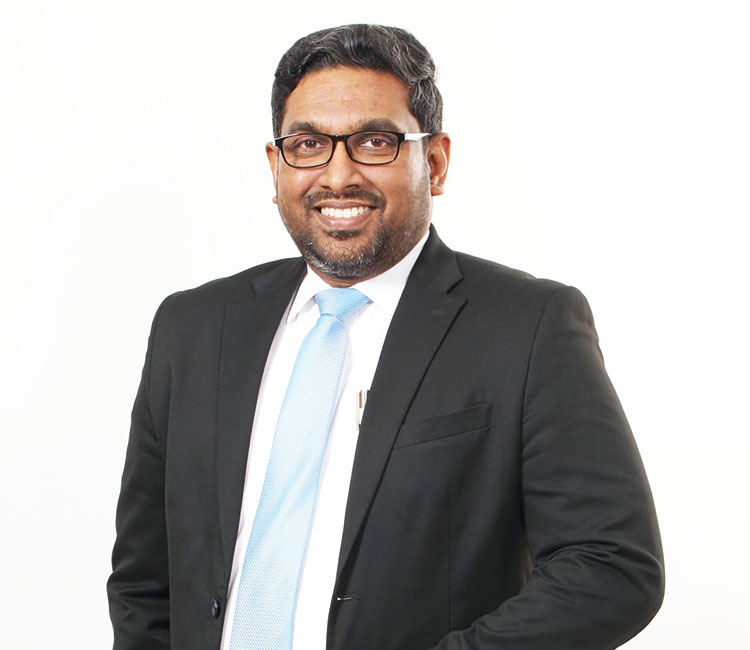
Sri Lanka Insurance Life (SLIC Life), the nation’s largest and strongest Life Insurer, is pleased to announce the appointment of Dr. Sameera Dharmasena as its new Chief Executive Officer, effective 22nd September 2026.
Dr. Dharmasena is a distinguished insurance professional with over 21 years of experience in the Sri Lankan insurance industry, having held senior leadership positions across several leading insurance companies affiliated with some of Sri Lanka’s largest business conglomerates. His extensive career spans both local and multinational insurance environments, bringing together broad industry expertise, strategic leadership and a strong commitment to the advancement of the insurance profession.

Lalit Rajbanshi, Kushal Bhurtel set up Nepal’s opening win

‘Vision’ Programme Marks Two Years

Costa Rica minister fired for unapproved meeting with Trump in US

At least 41 die as boat capsizes in DRC’s Lake Tanganyika

Showers will occur at times in the Western, Sabaragamuwa, Southern, Central and North-western provinces

Sajith vows to scrap 22A under future govt.

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 News7 days ago
Shanakiyan urges urgent action over reported death sentence for Lankan in Saudi Arabia
-
 News6 days ago
Namal Rajapaksa Buddhist gambit fails, bail denied
-
 Features6 days ago
Why the spelling Sri Lankan names in English vary
-
 Features6 days ago
Three bands, a new identity: Sri Lankan wolf snake recognised as distinct species
-
 Business6 days ago
SLIIT holds largest-ever convocation
-
 News6 days ago
Vehicle prices drop by up to Rs. 1 mn, says importers’ body
-
 News6 days ago
Govt monitors reported Saudi death sentence – Foreign Ministry
-
 Business6 days ago
All-new Bolero MaXX Pik-Up unveiled in Lanka