Business
Central Bank of Sri Lanka releases Financial Stability Review for Year 2026


In terms of Section 70(1) of the Central Bank of Sri Lanka Act, No. 16 of 2023, the Central Bank of Sri Lanka released its annual Financial Stability Review (FSR) for 2026. This statutory report provides an assessment of the stability of the financial system, identifies and evaluates the associated risks and vulnerabilities, and outlines the policy measures implemented by the Central Bank and other regulatory authorities. The report generally covers data up to end June 2026. The electronic version of the publication can be accessed through the Central Bank website. (https://www.cbsl.gov.lk/en/publications/economic-and-financial-reports/financial-system-stability-review )
Summary of the FSR 2026 is given below:
Amidst multiple shocks, Sri Lanka’s financial system remained stable during the first half of 2026, supported by the continued economic recovery, sustained adequacy of capital and liquidity buffers across banks and finance companies (FCs), and improved fiscal performance. While domestic macrofinancial conditions remained stable, intensifying uncertainties in the global environment increased the risk of adverse spillovers to the domestic economy. Stability during the review period was supported by the continued recovery in economic activity, improved fiscal conditions and stronger financial sector performance. These developments provided an important cushion against heightened external uncertainties and supported the overall stability of the financial system. Nevertheless, the external environment remained challenging. Heightened geopolitical tensions, resurgent global inflationary pressures, elevated energy and commodity prices, tighter global financial conditions, growing trade fragmentation and increasing climate-related risks continued to pose potential spillovers to the domestic economy. Sri Lanka remained particularly exposed to adverse external developments, given its significant exposure through trade, tourism receipts, workers’ remittances, capital flows, external financing conditions and exchange rate dynamics. On the domestic front, credit growth, particularly in household lending including vehicle financing and gold-backed lending, continued to widen the private sector Credit Gap, signaling a potential build-up of systemic vulnerabilities. Moreover, although financial sector exposure to the public sector reduced, it remained significant, underscoring the considerable sovereign-financial sector nexus. Rising household indebtedness, volatility in collateral values with increased exposure to collateral-backed lending, the continued rise in real estate prices and inflationary pressures further highlighted emerging risks. In response to these developments, the Central Bank increased the overnight policy interest rate in May 2026 and introduced macroprudential measures, including loan-to-value (LTV) limits on vehicle and gold-backed lending, aimed at containing the build-up of vulnerabilities within the economy.
Domestic financial markets remained largely stable during the period, with the Financial Stress Index remaining at relatively low levels. Financial market conditions were shaped by heightened global uncertainty, domestic inflation concerns, and tighter monetary conditions. Equity market performance moderated amid subdued investor sentiment, while market liquidity weakened and volatility increased. Yields of Government securities increased across maturities during the review period with evolving market expectations and subsequently due to monetary policy tightening. Secondary market liquidity remained relatively subdued pointing to limited depth and trading activity in the domestic debt market. Meanwhile, foreign investor participation continued to be low despite a modest recovery towards the latter part of the reference period. The domestic foreign exchange market experienced periods of heightened pressure particularly with the escalation of tensions in the Middle East, reflecting increased demand for foreign currency arising from higher import expenditure, rising energy prices, and shifts in investor sentiment. These developments contributed to the depreciation of the Sri Lanka rupee against the US dollar. Market conditions subsequently improved, supported by policy measures and continued inflows from workers’ remittances, tourism, exports and intermittent fall in oil prices. Money market activity strengthened during the period, while overall liquidity remained in surplus and interest rates remained broadly aligned with the monetary policy stance. Payment and settlement systems continued to demonstrate operational resilience, supported by further digitalisation and improvements in settlement infrastructure. The continued expansion of digital financial services enhanced efficiency and financial inclusion, albeit increasing the financial system’s exposure to cyber, operational, and third-party risks. As digital connectivity deepens and technology evolves rapidly, ensuring adequate cyber resilience and operational preparedness remains critical to safeguarding financial stability.
Financial institutions continued to demonstrate overall resilience during the period under review, supported by the recovery in economic activity, stronger profitability and adequate capital and liquidity buffers. The banking sector credit expanded significantly amid robust private sector demand, with notable growth in consumption, trade, financial services, construction, and offshore-related lending. The decline in the Stage 3 loans ratio along with the improvement in the Stage 3 impairment coverage ratio depicted improved resilience of the banking sector. However, Stage 2 loans increased during Q2 of 2026, indicating a potential build-up of credit risk among borrowers amid elevated credit expansion. While liquidity ratios in the banking sector moderated during the review period, they remained well above regulatory thresholds. This decline primarily reflected a shift in asset allocation from high-quality liquid assets, particularly Government securities, to private sector lending. Meanwhile, short-term maturity mismatches widened, increasing potential refinancing and liquidity risks within the sector under unexpected stress conditions. Further, banking sector profitability continued to improve, although the pace of growth moderated somewhat from the levels recorded during the first half of 2025. Despite continued buildup of capital, driven by stronger profitability, the banking sector’s capital adequacy ratios declined as the growth of risk-weighted assets exceeded the pace of capital accumulation. Notwithstanding this moderation, capital buffers remained well above regulatory thresholds, providing adequate capacity to absorb potential shocks.
FCs sector witnessed a significant credit expansion driven by heightened demand for vehicle financing and gold-backed lending. Despite the improvement in the Stage 3 loans ratio, the sharp increase in Stage 2 loans indicated rising credit risks within the FCs sector. This was partly attributable to the adverse effects of Cyclone Ditwah and the Middle East conflict on affected borrowers and underscored the need for continuous monitoring of asset quality developments and the potential buildup of sectoral vulnerabilities. Moreover, the impairment coverage ratio declined, indicating a deterioration in loss absorption capacity within the sector. While liquidity buffers in the FCs sector remained adequate and well above regulatory thresholds, liquidity ratios declined amid strong credit expansion. Meanwhile, faster growth in borrowings compared to deposits highlighted the increasing interconnectedness between FCs and banks. Profits in the FCs sector continued to increase, supported by net interest income, although the rate of profit growth moderated during the first quarter of the financial year 2026/27. Capital buffers of the sector declined alongside the increase in risk-weighted assets driven by the expansion in credit. The insurance sector remained adequately capitalised, although profitability moderated. Significant claims arising from Cyclone Ditwah increased reinsurance receivables and heightened underwriting, liquidity, and counterparty risks.
Lending to both the Household and Institutional sectors increased during the first half of 2026. Although household credit growth remained elevated, a marginal moderation was observed towards the latter part of the period. The share of credit extended by Non-Bank Financial Institutions to the Household sector increased further during the first half of 2026, although the banking sector remained the primary source of formal financing for households. Moreover, risk profiles of Household borrowers, as reflected by overall credit scores, remained broadly stable during the first half of 2026. Credit to the Institutional sector also expanded at a rapid pace, with the banking sector accounting for the vast majority of lending to the sector. Meanwhile, the listed non-financial corporate (NFC) sector recorded stronger revenue growth during the first half of 2026, although aggregate profitability weakened. The decline in aggregate profits was largely attributable to higher costs of sales and operating expenses. Against this backdrop, creditworthiness of the listed NFC sector showed some signs of moderation, reflecting a slowdown in aggregate profitability and debt-servicing capacity.
In response to developments and emerging risks within the financial sector, a range of policy measures were implemented during the review period. Against the backdrop of rapid credit expansion in vehicle financing and gold-backed lending, borrower-based macroprudential measures were tightened to contain excessive leverage and mitigate emerging risks. These measures included simplification and tightening of maximum LTV limits on motor vehicle financing and the introduction of maximum LTV limits on gold-backed lending, aimed at promoting prudent lending practices and containing the buildup of systemic vulnerabilities. In addition to the LTV limits on gold-backed lending, applicable risk weights were also tightened during the review period. In response to the adverse effects of Cyclone Ditwah, the Central Bank issued circulars to both banks and FCs, requiring relief measures to be provided to affected individuals and businesses. The Directions on recovery planning for both banks and FCs were issued, alongside consolidation initiatives aimed at strengthening the resilience of the banking and FCs sectors. Amid the increasing prevalence of financial frauds and scams involving digital payment channels, the Central Bank introduced policy initiatives aimed at strengthening the security of digital payment methods and improving public awareness of related risks. Measures were also taken to strengthen the resolution framework, financial consumer protection, and Anti-Money Laundering, Countering the Financing of Terrorism and Countering Proliferation Financing (AML/CFT/CPF) framework, alongside preparations for Sri Lanka’s third Mutual Evaluation of its AML/CFT/CPF framework by the Asia Pacific Group on Money Laundering (APG) as well as initiatives aimed at improving financial inclusion.
Financial Stability Outlook
The outlook for financial stability remains broadly positive, provided that the ongoing economic recovery remains sustained, fiscal consolidation progresses, and prudent policy implementation continues. However, the outlook is contingent on external developments, including geopolitical and financial market uncertainties, as well as domestic vulnerabilities arising from any excessive expansion and sectoral concentration of credit, along with evolving cyber risks. Continued monitoring and timely policy intervention will therefore remain important in preserving financial stability. Prolonged geopolitical tensions and energy price shocks could weaken external balances and increase inflationary pressures, thereby impacting the repayment capacity of borrowers. These effects could amplify existing domestic vulnerabilities, including higher growth in collateral backed lending to households, rising Stage 2 exposures and declining liquidity and capital buffers. Financial market resilience will increasingly be shaped by the ability to strengthen investor confidence, improve market liquidity, deepen domestic capital markets, and attract a broader and more stable foreign investor base, thereby enhancing the market’s capacity to absorb shocks and support efficient price discovery. Overall, maintaining financial stability will require a well-calibrated combination of prudent monetary, macroprudential and regulatory policies, supported by sustained progress in structural reforms. Priorities of the financial sector should therefore focus on preserving strong capital and liquidity buffers across financial institutions, strengthening the management of climate-related and cyber risks, enhancing resolution and crisis-preparedness frameworks, and ensuring that credit expansion remains commensurate with underlying economic activity and risk conditions. These efforts will be essential in mitigating the buildup of systemic vulnerabilities, strengthening the financial system’s shock-absorbing capacity, and safeguarding financial stability over the medium term.

By Hiran H. Senewiratne
Sri Lanka’s financial literacy rate is approximately 58 percent. Such literacy is absolutely necessary for the inclusion of people in the country’s financial system which in turn is central to overall economic development, Central Bank Governor Dr. Nandalal Weerasinghe said.
‘One needs to have knowledge and skills of a financial nature to figure in financial inclusiveness. While 86 percent of Sri Lanka’s population has access to the country’s financial system, 82 percent of the public has at least a savings account in the country’s banking system, Dr Weerasinghe said.
The Governor made these comments recently at the inauguration of Financial Literacy Month 2026 at the Central Bank’s Centre for Banking Studies, Rajagiriya.
Dr. Weerasinghe added: ‘Suitable, affordable and quality financial instruments are needed to enhance financial literacy in the country.
‘Financial information has to be accurate, risk-free and accountable, thus creating confidentiality in the financial system, which would enable the sector to reach greater heights’.
Meanwhile CBSL sources said: ‘The Literacy Month opened with the two-day ‘FinLit Expo Colombo’. The expo gives the public the opportunity to engage with institutions, better understand financial services, gain practical insights into managing their finances and learn how to protect themselves from financial fraud and scams.
‘The CBSL is leading the program in collaboration with stakeholder institutions. It forms part of the Financial Literacy Roadmap for Sri Lanka, which is implemented under the National Financial Inclusion Strategy (NFIS), the national framework for widening access to and use of formal financial services.
‘The Colombo event will be followed by six regional ‘FinLit Expos’ aimed at direct engagement with local communities. Partner institutions will also run awareness activities. Together, the events are intended to provide financial education to communities and encourage people to apply financial knowledge in everyday life.
‘A public awareness campaign on television, radio, newspapers and social media will extend the program’s reach. The program also includes digital financial literacy activities and the promotion of QR codes and other online payment methods.
‘The public and stakeholder institutions are encouraged to take part in the month’s activities under the theme, “Towards a Financially Literate Sri Lanka”.
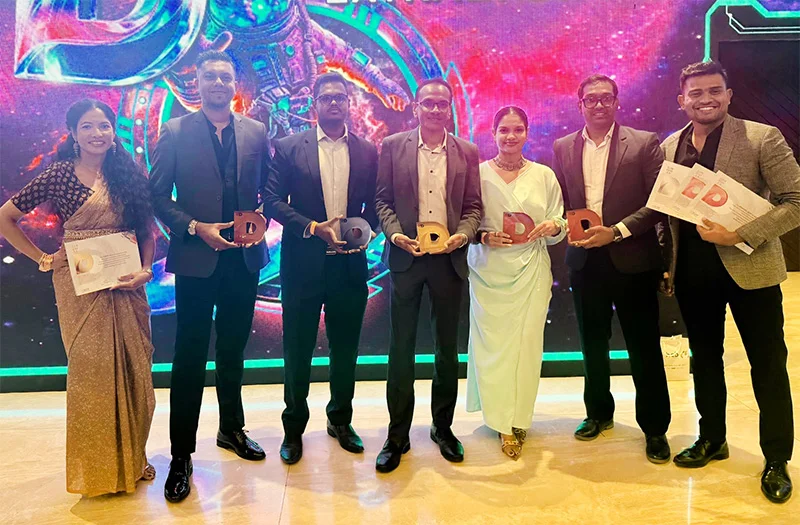
HUTCH Sri Lanka strengthened its position as a leader in digital engagement by securing five accolades at SLIM Digis 2.6, emerging as one of the most recognized brands at this year’s digital excellence awards. The achievement was further highlighted by HUTCH being the only telecom operator to be recognized at the event.
Organized by the Sri Lanka Institute of Marketing (SLIM), SLIM Digis is Sri Lanka’s premier platform celebrating excellence, innovation, and outstanding achievements in the digital marketing industry. The recognition highlights HUTCH’s growing strength in digital-first, agile, and creative marketing, and its ability to respond to everyday moments, engage audiences, and deliver impactful digital campaigns.
The Gold Award for Best Use of Agile and Moment Marketing, a Silver for Best Use of Digital in a Marketing Campaign, and a Bronze for Best Performance Marketing were all awarded for “Keeping Sri Lanka Connected Through Ditwah,” HUTCH’s response to the cyclone that struck Sri Lanka in November 2025, recognised for the speed and relevance with which HUTCH kept customers better connected and informed.
HUTCH Roaming also earned two further Bronze awards for Best Use of Digital in a Marketing Campaign and Best Use of Creative Content. Bringing together AI-led storytelling, the campaign was designed around distinct customer clusters, each characterized by unique travel behaviours, needs, and perceptions, delivering relevant content for different audiences within a single overarching campaign.
“These wins are a strong reflection of how HUTCH approaches marketing today, staying close to the moments that matter to our customers and responding with speed, relevance, and creativity. Being the only telco recognised at SLIM DIGIS 2.6, and across five categories, is proof that agility and thoughtful storytelling can go hand in hand. This recognition reflects the collective efforts with our strategic partners, whose collaboration, expertise, and shared commitment brought great campaigns to life,” said Hamdhy Hassen, Chief Marketing Officer, HUTCH Sri Lanka.
Sri Lanka’s Smart Luxury Business Hotel to Host Delegates and Contestants from Over 40 Countries as the Island Nation Hosts Its First-Ever Global Pageant of This Scale
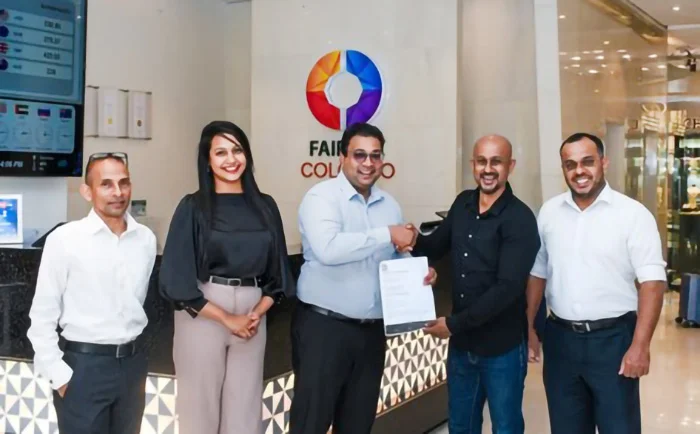
Fairway Colombo, a subsidiary of Fairway Holdings (Pvt) Ltd, has been appointed as the Official Accommodation Partner for Manhunt International 2026, one of the world’s most prestigious male pageants, scheduled to take place in Sri Lanka.
The event marks a historic milestone for Sri Lanka, as the country prepares to host a global pageant of this scale for the very first time. More than 40 contestants representing countries from across the world will arrive in Colombo, bringing together diverse cultures, international media attention, and a global audience — further strengthening Sri Lanka’s position as a premier destination for tourism, culture, and hospitality.
As the official accommodation partner, Fairway Colombo will welcome and host international delegates and contestants throughout their stay in Colombo, delivering the exceptional hospitality experience and personalized service that the hotel is recognized for.
A Landmark Partnership for Sri Lankan Tourism
“We are truly honored to be selected as the Official Accommodation Partner for Manhunt International 2026. This partnership is a proud moment not only for Fairway Colombo but also for Sri Lanka as a whole. Hosting an event of this global stature provides us with an opportunity to showcase our commitment to smart luxury, innovation, and authentic Sri Lankan hospitality to an international audience. We look forward to creating a memorable and seamless experience for all delegates and guests,” said Avinga Wanigasekara, General Manager of Fairway Colombo.
Strategically located in the heart of Colombo’s historic Fort district, Fairway Colombo is recognized as a Smart Luxury Business Hotel, combining modern comfort, advanced technology, and exceptional service. As part of Fairway Holdings (Pvt) Ltd, the property represents the group’s vision of delivering innovative, world-class experiences across the hospitality and leisure sectors.

Cabinet approves redrafting of State Assets Management Act
Cooperative Employees Commission Act No. 12 of 1972 to be amended
Dilki Wathsala Marambage appointed as Director General of the Department of Technical Education and Training
Declaration of Naakolagane Sanctuary under the Fauna and Flora Protection Ordinance
Cabinet approves transfer and maintenance of selected roads presently under PC’s and Local Authorities to the RDA
Obtaining financial facilities for the Water Supply and Sanitation Improvement Program (Sub-program 2) from the ADB

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Features6 days ago
The Sri Lankan who made Scottish history
-
 Sports6 days ago
Nissanka absence opens door for Sri Lanka’s young guns
-
 News5 days ago
NDB fraud Rs 60mn more than reported
-
 News7 days ago
Gnansara Thera to be assigned to prison printing section: Officials
-
 News5 days ago
Removing monk’s robes matter for Sangha to decide: Mahanayake Theras
-
 News7 days ago
OIC of FCID summoned before Maligakanda Magistrate
-
 Features6 days ago
Future of Sri Lanka’s state university system: Should it be shut down and reopened?
-
 News6 days ago
Shiranthi R remanded until 13 Oct.