Business
Sampath Bank moves ahead steadily to prove its ability to withstand strong headwinds

Amidst widespread economic uncertainty during the year 2022, Sampath Bank maintained a strong capital base and a steady liquidity profile. Proactive efforts to identify challenges and implement appropriate strategies has allowed the Bank to further reinforce its strength and stability. The Bank has also continued to lead by example in demonstrating its commitment to the national growth agenda by promoting inward remittances and encouraging the inflow of export proceeds to the Country while assisting all stakeholders to manage the current economic crisis. CSR activities were also accelerated by undertaking multiple projects under the Bank’s flagship ‘Weweta Jeewayak’ programme in order to propel the rural economy.
The Bank reported a PAT of Rs 7.2 Bn and PBT of Rs 9.3 Bn for the period ended 30th September 2022, reflecting a decline of 19.8% and 24.4% respectively, from the figures reported for the corresponding period in 2021 which is a reflection of the current economic turmoil in the Country. As at 30th September 2022, the Group reported PAT and PBT of Rs 7.7 Bn and Rs 10.2 Bn, a drop of 21.6% and 24.3% respectively compared to the corresponding period 2021.
Key financial highlights declared by Sampath Bank for 2022:
276% growth in exchange income stemming from the sharp depreciation of LKR against USD by 82% or by Rs 164.75.Sizeable 69.5% increase in net fee and commission income during the period, driven by cards and trade-related operations.
The Bank booked Rs 48.8 Bn impairment charge on loans and investments to capture possible economic uncertainties during the year.
Fund Based Income
Total interest income increased by 67.7% YoY during the nine months ended 30th September 2022, reaching Rs 106 Bn from the Rs 63 Bn reported in the corresponding period of the previous year. This was primarily due to the hike in interest rates reported in 2022, which saw the AWPLR reaching 25.95% as at 30th September 2022, denoting a 1,953 bps increase from the 30th September 2021 and 1,734 bps increase compared to the year-end 2021. The one-year T Bill coupon rate also rose to 29.85% as at 30th September 2022, an increase of 2,284 bps against 30th September 2021.
Driven by the rising market interest rates, the Bank’s interest expense increased by 57.3% compared to the corresponding period of the last year to reach Rs 52.8 Bn for the reporting period. Prudent asset and liability management ensured that net interest income increased by 79.4%
Non-Fund based income
During the reporting period, the Bank’s Net Fee and Commission Income (NFCI) increased substantially by 69.5% compared to the same period in the prior year. NFCI, which comprises of revenue from numerous sources, such as loans and advances, credit cards, trade and electronic channels increased significantly led by the card related businesses and fee and commission income derived from trade related activities.
The net other operating income for the nine months ended 30th September 2022 was Rs 18 Bn. This 320% YoY increase was attributed to the Rs 164.75 drop in value of the LKR against USD. During 2022, the Bank reported a net trading loss of Rs 3 Bn against the Rs 98 Mn loss reported during the previous year. Total foreign exchange income for the reporting period was Rs 14.5 Bn, up from the Rs 3.8 Bn recorded during the last year.
Impairment charge
The Bank has recognised a total impairment charge of Rs 48.8 Bn for the nine months ended 30th September 2022. This is a 396% increase from the Rs 9.8 Bn charge reported in the previous year. Of this, the impairment charge for loans and advances amounted to Rs 37.7 Bn, while Rs 10.3 Bn was on account of other financial instruments. In addition, an impairment charge totalling Rs 839 Mn was booked against other commitments and contingencies.
Impairment charge on loans and advances: In order to reflect the deterioration of the country’s economic environment, the Bank increased the probability weightage allocated to a worst economic scenario and revisited the EFA model which led to the recognition of a significantly higher impairment provision during the reporting period. Industries considered under elevated risk were further expanded to capture a broader range of industry specific stress factors. The potential impact of rising inflation, higher interest charges and increase in taxes on the retail segment were some of the other factors that were considered in recognizing impairment provisions.
The Bank reviewed the adequacy of the impairment provision in respect of customers in the tourism and other similarly affected industries whereby necessary and adequate impairment provisions were recognised under individually significant loan impairment. The Bank also continued to recognise impairment provision against the customers who exited the moratorium at the end of December 2021 and June 2022 as some customers have requested further concessions given the current economic outlook. In addition, steps were taken to shift customers from Stage 1 to Stage 2 based on their ability to withstand the negative effects caused by the economic downturn.
A culmination of these efforts has ensured that a higher overall provision cover of 9.8% at the end 30th September 2022 which is deemed adequate to support the Bank to absorb potential losses arising from severe macro-economic conditions.
Impairment charge on other financial instruments: The Bank provided Rs 9,040 Mn against SLISBs and Rs 935 Mn against SLDBs as at 30th September 2022. This decision was influenced by two key factors- the downgrade in Sri Lanka’s sovereign rating in May 2022 to RD from C by Fitch Ratings and the current debt restructuring actions taken by the Government. The Bank’s cumulative impairment provision for SLDBs and SLISBs stood at Rs 21.6 Bn at the end of the reporting period. Meanwhile, the Bank was able to significantly reduce the exposure to FCY instruments by converting the matured SLDBs to LKR instruments during the reporting period.
Net operating income
Total operating income for the period increased by Rs 40 Bn. However, impairment charge too increased by Rs 39 Bn, restricting the growth of net operating income to 3.7%.
Operating expenses
Operating expenses during the reporting period amounted to Rs 20.5 Bn, a 23.6% increase from Rs 16.6 Bn recorded during the corresponding period of last year. Rising inflation and the LKR depreciation were the main contributors to this increase. Despite the growth recorded in the operating expenses, the Bank’s cost to income ratio (CIR) dropped significantly by 1,460 bps and stood at 25% compared to 39.6% reported in the corresponding period of 2021. This drop in CIR was predominantly due to the increase in total operating income surpassing the rise in total operating costs.
Tax expenses
Despite the 17.6% drop in profit before VAT, the VAT on Financial Services increased by 9.3% owing to the upward movement in the VAT rate from 15% to 18%, with effect from 1st January 2022.
The Inland Revenue (Amendment) Bill issued on 11th October 2022 has not been substantively enacted by the parliament. Therefore, the Bank has not considered the changes proposed in the Bill for the reporting period.
Key ratios
The Return on Average Shareholders’ Equity (after tax) dropped to 8.08% as at 30th September 2022 compared to 11.05% reported at the end of the year 2021. Return on Average Assets (before tax) stood at 0.96% as at 30th September 2022 as against the 1.44% reported for 2021.
Capital ratios
As at 30th September 2022, the Bank maintained all its capital ratios well above the regulatory minimum requirements. Bank’s CET 1, Tier 1 and total capital ratios on 30th September 2022 were 11.31%, 11.31%, and 13.72% respectively, in comparison with 13.95%, 13.95%, and 17.02% at the end of 2021. The decline in the ratios during the reporting period is due to the combined impact of increase in risk-weighted assets resulting from the LKR depreciation, cash dividends and payment of surcharge tax.
Assets and liabilities
Sampath Bank’s total assets exceeded Rs 1.3 Tn by end of September 2022, an increase of Rs 113 Bn (annualised growth of 12.6%) from 31st December 2021 position of Rs 1.2 Tn. Increases in cash and cash equivalents as well as net loans and advances have contributed to the aforementioned growth. One of the primary causes of the balance sheet expansion can be attributed to the devaluation of the local currency during the year.
Total advances increased by 22.6% (annualised) over the reporting period, from Rs 813 Bn at the end of December 2021 to Rs 951 Bn as of 30th September 2022. The LKR loan book increased by 12.1% (annualised). It should be mentioned that the value of loans denominated in foreign currency grew significantly after the LKR depreciated by Rs 164.75 against USD during the period. If the variations in currency rates had not occurred, the total loans and advances would have shown an increase of 8.8% (annualised).During the 3Q22, the LKR deposit base grew by Rs 44.4 Bn due to deposit mobilisation initiatives promoted by the Bank. Nevertheless, growth in LKR deposit base was restricted to 0.8% compared to year end 2021.







The Securities and Exchange Commission of Sri Lanka (SEC) and the Colombo Stock Exchange (CSE) have taken their ‘A Share for Everyone, A Unit for Everyone’ (Samata Kotasak, Samata Ekakayak) initiative to Anuradhapura and Jaffna through investor forums last week, as part of an ongoing islandwide effort to broaden investor participation. The forums were held on 10th September at the Golden Mango in Anuradhapura, and on 12th September at the Tilko Jaffna City Hotel. The forums attracted over 600 participants across both locations.
The “A Share for Everyone, A Unit for Everyone” concept, developed by the Chairman of the SEC, Sen. Prof. D.B.P.H. Dissabandara and launched in July of this year, aims to promote a shared commitment to creating wealth and value within a fair, efficient, orderly, and transparent capital market by ensuring broad and accessible participation for all.
As part of this initiative, the SEC and CSE will continue to host investor forums across the country to strengthen investor education and awareness while promoting broader participation in the capital market beyond the Western Province. By leveraging the CSE’s nationwide reach and the growing interest in equity investments, the programme will provide investors with greater access to Sri Lanka’s capital market through stockbroking firms and unit trust management companies.
“Traditionally, Sri Lankan investors have favoured conventional investment avenues, but it has yielded comparatively fewer returns than the capital market,” remarked Executive Vice President – Marketing, CSE, Niroshan Wijesundera, speaking on the Unit Trust and Stockbrokering firm outreach objectives of the broad-basing initiative.
“Over the medium to long term, capital markets have given higher returns. By setting aside small allocations to invest regularly through professionally managed vehicles such as unit trusts, first-time investors can participate in the capital market, receive higher returns in the medium-to-long-term, and gain experience and confidence. On the other hand, those with experience and knowledge can directly engage with the capital market through a stockbrokering firm. Traditional investments are liable to be taxed, whereas investments in the capital market are capital-gains tax free.”
Speaking on the favourable investment climate, he noted that the Sri Lankan capital market is at a relatively low Price-to-Earnings (P/E) ratio of 11.03x in a global context. “As covered in the presentations at the forums, the Sri Lankan capital market has demonstrated comparative resilience in the face of global market corrections, such as the Middle Eastern crisis. Sri Lanka has withstood bigger shocks, such as past crises, the war, COVID-19, the economic downturn, and the fuel crisis.’’
Business
“Pulle Madu” to medical school: record intake signals turning point for plantation sector welfare

Many generations ago, an estate child’s first years began in a cloth hammock strung up near the rows of tea bushes, so a mother could keep working within earshot of her infant. Later a corner in a line room was converted to establish Pulle Madu, where infants and toddlers were sheltered to ensure that plucking by their mothers was not disrupted.
Today, fully equipped Child Development Centers (CDC’s) complete with qualified and trained CDC officers have replaced the old Pulle Madu, to offer children the same level of education and exposure that any child in a city avails. These children receive custodial care, and child development support through these CDC’s, while Early Childhood Centers (ECD) lay greater emphasis on structured early learning through a play-based curriculum, while also providing dedicated spaces for working mothers to breastfeed.
These Centers are the result of the collaborative efforts of the Regional Plantation Companies (RPCs), the Government of Sri Lanka, and key plantation-sector trade unions, including the Planters’ Association of Ceylon. Together, these stakeholders form the tripartite body that established the Planters’ Human Development Trust (PHDT) in 1992, and have since contributed to significant development across the 22 RPCs.
The RPCs collectively spend nearly Rs. 720 million annually to maintain these CDC’s, reflecting the sector’s continued investment in childhood development and the wellbeing of plantation communities. This foundation supports their continued education and health development and, in the long term, helps them progress towards successfully completing the GCE O/L and A/L examinations.
To date, primary school enrolment among children from plantation communities has reached 100%, while approximately 2–3% of students go on to pursue higher education at local universities. Over the past two years, nearly 250 children from plantation families have gained admission to university, marking the highest number recorded by the sector to date. Among them is a young man from Strathspey Estate, now training to be a doctor at Eastern University. “Everything I have achieved is a direct result of my parents’ tireless hard work,” he said, thanking his teachers and the scholarship grant that carried him through school, whose identity is withheld in line with the programme’s standard practice for student privacy.
It also manifests powerfully in Roots to Wings, the university start-up scholarship initiative launched by PHDT in collaboration with the Planters’ Association and other industry partners. “Every year we saw bright students earn a place at university and then risk losing it, not for lack of ability, but because they couldn’t afford a laptop, a set of books, or even proper clothing to arrive on campus with dignity,” explained PHDT Director General Lal Perera. “To correct this situation, after careful study, we facilitated a scheme that bridges the most urgent gap. We cover the immediate start-up costs, while the Regional Plantation Companies, through their CEOs, ensure that the student is carried through to graduation. If a family loses estate housing when a parent retires, we don’t let that end a degree either. Students are granted extensions, and where needed, RPCs provide new housing, supported in part by Indian High Commission grants. Once a child has earned a place at university, we consider it our duty to make sure that place is never lost to circumstance.”
This scheme has become more than financial assistance; it is a lifeline of dignity, continuity, and hope. By addressing the hidden barriers that often derail promising futures, Roots to Wings ensures that talent from the plantation sector is not wasted but nurtured into leadership for tomorrow. It is a model of shared responsibility, where industry stakeholders collectively safeguard the aspirations of youth, transforming vulnerability into opportunity and circumstance into achievement.
The scheme costs an estimated LKR 10 to 15 million a year, funded by various industry stakeholders. The 2024 to 2025 cohort spans 35 Arts students, 22 in Commerce and Management, 13 in Drama and Theatre, 10 in Bio-systems, 7 in Music, 6 in ICT, four each in Medicine and Engineering, three in Engineering Technology, two in Law and 24 across other faculties, a spread once unimaginable on estates where literacy in PHDT’s target areas has climbed from 40 to 84 percent. Specialised degree pathways and vocational opportunities such as Uva Wellassa University’s Bachelor of Science Honours in Plantation Management, vocational training through the National Institute of Business Management and digital learning through the Open University of Sri Lanka has further empowered students with promising academic and career prospects.
The health figures tracked alongside the Department of Census and Statistics and the Family Health Bureau since 1992, shows infant mortality falling from 18.3 per 1,000 live births to 4.65, and under five mortality from 42.6 to 6.26. Maternal mortality, once as high as 150 per 100,000 live births, has fallen close to zero in most recent figures, and stillbirths have dropped from 40 per 1,000 deliveries to under five today. Nearly all deliveries now happen in health institutions, almost every mother receives antenatal care, and every child completes first year immunization, which are gains attributed to better roads, housing, welfare services and preventive healthcare across the estates.
Nutrition support has similarly evolved, with centers moving from contractor-supplied meal packets towards parent-prepared midday meals. A centrally managed kitchen model has also been piloted at Dessford Estate, with a second facility planned at Holyrood Estate. However, officials do acknowledge that nutrition among younger children remains the area needing the most continued investment.
The progress made in improving health outcomes, particularly in reducing infant mortality, is significant. This reflects the RPCs’ continued commitment to community development, which extends to supporting education through scholarship programmes. These initiatives, together with established healthcare and educational support systems, contribute to improving opportunities and outcomes for children and families across plantation communities.
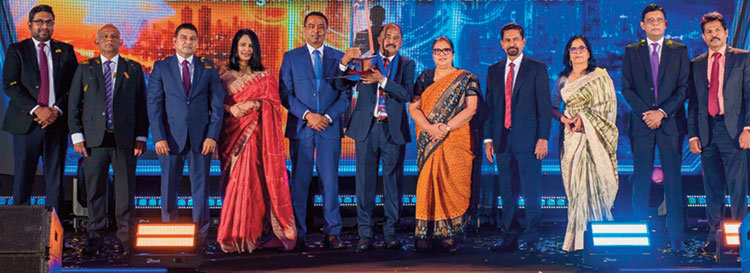
Ceylinco Life has reaffirmed its standing as a powerhouse of sales excellence in Sri Lanka’s life insurance industry, securing an outstanding 12 awards at the 2026 edition of the National Forum for Life Insurance Advisors (NAFLIA), including five National Awards that recognised its professionals as the best in the country.
The awards event saw Ceylinco Life’s sales professionals excel at both the Large Company and National levels, with the company claiming top honours across the Advisor, Supervisor and Branch Manager categories in both levels, while also producing two winners in the Large Company level in the Fast Starter Advisor category.
In the Advisor category, A. P. S. Wijayakumar secured first place at National and Large Company Level, while A. I. P. Manjula was placed second in both levels, giving Ceylinco Life four awards across the two tiers of recognition in this category.

Advisory for strong winds and rough seas for Multi-day boats in the Bay of Bengal

Showers in the Western, Sabaragamuwa and North-western provinces and in Galle, Matara, Kandy and Nuwara-Eliya Districts

Some NPP manifesto promises may be difficult to fulfil – CIABOC DG

Yoshitha and ex-Navy chief Karannagoda’s case fixed for PTC

Court orders probe into Wimal’s rally speech

Court to rule on Dilith’s writ petition on September 30

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 News6 days ago
Gnanasara Thero absconding after SC ruling
-

 Opinion5 days ago
From Galkissa (Mount Lavinia) to Tambuttegama
-

 Business6 days ago
HNB Finance strengthens Board with four independent directors
-
 News2 days ago
US embassy won’t comment on IGP’s probe into joint drug raid
-
 Sports6 days ago
Culture within cricket team worrying authorities
-

 Features5 days ago
Sri Lanka’s university crisis: Brain drain and union action demand urgent reform
-
 Features4 days ago
The emptying university: why are academics leaving?
-

 News6 days ago
House to debate 22A, Judicature Bill next week