Business
Russia-Ukraine conflict: Economic implications for Sri Lanka

By Asanka Wijesinghe
 The Russian invasion of Ukraine deepens the existing global economic woes – persistent supply chain bottlenecks and associated rising inflation – clouding the prospects of a smooth global economic recovery from the pandemic. The West, led by the US and the EU, swiftly imposed strict economic sanctions, targetting Russian banks, oligarchs, political leaders, and state-owned and private entities, generating additional uncertainty over the global economic outlook. The initial disunity in the West on cutting off Russia from SWIFT-a global financial telecommunication system that allows the smooth and rapid cross-border transaction of money- was resolved over the weekend. Such a move will inevitably make payments for Russian exports and imports hard. The ongoing military conflict in Europe could not have come at a worse time for Sri Lanka given its own prevailing high inflation, rising energy costs, and scarcity of foreign exchange. Against this backdrop, this article discusses the economic impact of the European conflict on Sri Lanka, the sectors that will be hit hard, and ways to mitigate the negative impact.
Global Economic Impact
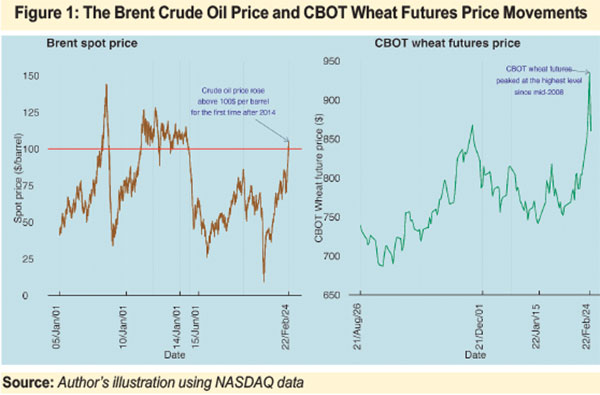
 Immediately after the Russian invasion on 24 February, commodity markets rallied up. The Brent spot price of a crude oil barrel reached USD 105 for the first time after 2014. Similarly, the cost of wheat futures for March 2022 in the Chicago Board of Trade (CBOT) exchange peaked, at its highest since mid-2008 (Figure 1). The Russian Federation and Ukraine-known as Europe’s breadbasket- are major cereal, fertiliser, critical minerals, and iron and steel exporters. Meanwhile, the Western powers were busy over the weekend in negotiations to tighten sanctions on Russia.
While the fate of Ukraine hangs in the balance, the consensus among analysts is that the Ukrainians were mounting a fierce and unexpected resistance, effectively increasing the costs for Russia. The US, EU and their allies are contributing to the military conflict by providing financial and military assistance to Ukraine while imposing sanctions on Russia to make dollar transactions difficult. Thus, the severity of the global economic impact will be determined by the scope and duration of the conflict and the effectiveness of Western sanctions.
Western countries will be keen to minimise the spillover effects of sanctions on their economies. Like Germany, the major European economies heavily depend on Russian energy, making it necessary to exempt the energy sector from sanctions. Indeed, the sanctions package unveiled by the Biden administration did not target the energy sector. As long as payments for energy-related transactions go through non-sanctioned and non-US financial institutions, an unconstrained flow of money is guaranteed. Thus, oil prices dropped with futures closing below USD 93 a barrel in New York. However, that optimism was largely fading in early trade on 28 February. The Brent price rallied over 100 dollars again while wheat, soybean, and corn futures were up. Cutting off Russia from SWIFT and imposing sanctions on the Russian Central Bank can deal a severe blow to the Russian economy in the long run. The collapsing ruble can be a harbinger of Russia’s economic collapse. A possible economic fallout will reduce Russian demand for foreign products, and if Russia cuts off natural gas to the European market, a likely outcome will be a recession.
Implications for Sri Lanka
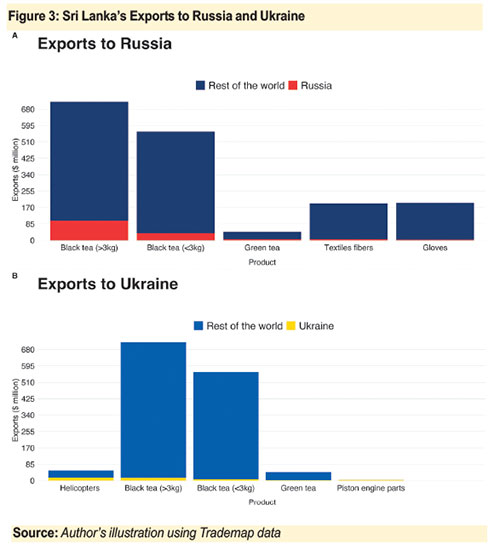
Overall, Russia and Ukraine account for 2% of Sri Lanka’s imports and 2.2% of exports in 2020. However, both countries are vital import sources for wheat and export destinations for Sri Lanka’s black tea (Figure 2 and 3). Russia and Ukraine purchase about 18% of fermented black tea (>3kg) exported by Sri Lanka. Similarly, 45% of Sri Lanka’s wheat imports are sourced from Russia and Ukraine. In addition, more than half of Sri Lanka’s imported soybeans, sunflower oil and seeds, and peas are from Ukraine. Moreover, Russia and Ukraine are significant import sources for asbestos, semi-finished products of iron and steel, copper (cathodes), and potassium chloride for fertiliser.
Unless the Ukraine crisis is not solved immediately, the fuel and commodity prices can rally further. The inflationary pressure in the Western markets, especially in Europe due to high energy prices and supply chain bottlenecks, may reduce consumers purchasing power, lowering the demand for goods exported by Sri Lanka. Europe is a significant export destination for readymade garments, tea and spices, and seafood.
There is also a growing tendency for increased military expenditure in the long run, which might reduce the “peace dividends” for European households. For example, the German Chancellor committed 2% of GDP for defence expenditure, addressing an extraordinary session of Bundestag. Replacing consumerism with militarism will adversely affect countries like Sri Lanka that depend on the European export market. In addition, a prolonged crisis may impede Sri Lanka’s ability to purchase necessary raw materials like fertiliser. Importantly, Sri Lanka’s exposure to the situation is mainly through linkages to the commodity and European export markets rather than direct exposure to the two countries involved in the conflict.
Mitigation
 Sri Lanka should focus on safeguarding access to vital raw materials and food commodities. Globally, responding to the crisis, countries are stockpiling grain and exploring alternative ways to do business with Russia in purchasing raw materials. Sri Lanka has limited options to mitigate the impact on already deteriorating food security conditions and access to raw materials. As wheat and rice are substitutes, high wheat prices may increase the demand for rice.
Thus, it is necessary to remove input shortages like fertiliser to ensure domestic production is adequate. Due to the current foreign exchange crisis, Sri Lanka’s ability to effectively face such shocks is constrained. Thus, the urgent priority is to resolve the current foreign exchange crisis to regain the ability to trade swiftly. Achieving debt sustainability and securing dollar inflows from multilateral institutes might be the options at Sri Lanka’s disposal. Then, entering forward contracts for raw materials and fuel and negotiations with friendly countries for food on predetermined prices are possibilities.
Link to Talking Economics blog:
Russia-Ukraine Conflict: Economic Implications for Sri Lanka
Asanka Wijesinghe is a Research Fellow at IPS with research interests in macroeconomic policy, international trade, labour and health economics. He holds a BSc in Agricultural Technology and Management from the University of Peradeniya, an MS in Agribusiness and Applied Economics from North Dakota State University, and an MS and PhD in Agricultural, Environmental and Development Economics from The Ohio State University. (Talk with Asanka – asanka@ips.lk)

Sri Lanka’s national economic discourse takes center stage today as the country’s premier private-sector body, The Ceylon Chamber of Commerce, hosts the Sri Lanka Economic & Investment Summit 2026 at the Shangri-La Colombo.
Convening on October 12 and 13, the two-day summit brings together an influential gathering of senior policymakers, international financiers, multilateral development partners, and private-sector captains to chart the island’s next phase of macroeconomic growth.
Held under the theme “Positioning Sri Lanka in a Changing Global Economy: Resilience, Reform, and the Future of Economic Policy,” this year’s forum marks a critical inflection point in the nation’s post-crisis trajectory.
As Sri Lanka shifts its emphasis from immediate financial stabilization toward sustainable, long-term expansion, the summit aims to address the structural imperatives necessary to secure high-impact foreign direct investment (FDI), deepen regional trade integration, and unlock emerging sectors of economic activity.
The core agenda over the two days focuses on building resilience across volatile global market cycles while executing targeted policy reforms. Key working sessions will examine:
Regional Value Chains & Trade Integration: Leveraging Sri Lanka’s strategic Indian Ocean geography to capture higher-value export flows and commercial linkages.
Energy & Infrastructure Transformation: Accelerating renewable energy integration and modernizing national utility policy.
Digital Economy & Public Modernization: Deploying digital technologies across public administration and financial services to enhance operational efficiency and transparency.
Sectoral Priorities: Modernizing healthcare infrastructure and agricultural value-addition to build a robust domestic economic base.
A defining feature of this year’s summit is the strong convergence between state policy and global commercial expertise. Keynote addresses and panel discussions will feature prominent leaders, including Prime Minister Dr. Harini Amarasuriya and T. Krishnakumar, Chief Executive Officer of Reliance Consumer Products Ltd.
They will be joined by senior delegations and policy experts from major global institutions, including:
= The Asian Development Bank (ADB)
= The International Finance Corporation (IFC)
= Standard Chartered Bank
= Zydus Lifesciences
The active participation of the country’s highest executive and legislative leadership across both days underscores a clear policy commitment to private-sector-led growth. By establishing a direct, high-level platform for dialogue between investors and policymakers, the Ceylon Chamber’s summit seeks to refine regulatory frameworks, improve the ease of doing business, and establish a clear, predictable environment for capital formation in the years ahead.
Microsoft and several other technology firms have been barred by the White House from hiring skilled international workers on a permanent basis through a widely used visa programme.
US Vice-President JD Vance on Thursday accused Microsoft alongside other firms of committing fraud through the use of the H-1B visa programme and a related process for workers from abroad to become permanent US residents.
Vance claimed that Microsoft, one of the most valuable companies in the US, has been effectively replacing American workers with “foreign indentured servants.”
Microsoft said most of the H-1B visas filed over the last financial year were for existing workers, who are paid the same as local staff.
“No company in the US has abused this system more than Microsoft,” Vance said.
He also made similar accusations about Adobe, Cognizant, Infosys, Tata, Wipro, HCL and Capgemini.
The US government will not process any new or pending Permanent Labor Certification Program (PERM) applications from Microsoft or the seven other companies, Secretary of Labor Keith Sonderling said during the same conference.
Sonderling said companies like Microsoft, as well as US universities, have turned into “visa mills” that were “flooding” the US with foreign workers.
The BBC has contacted all of the companies for comment.
The total number of H-1B visas, a precursor to anyone seeking to go through the PERM process, is capped at 85,000 per year.
A spokeswoman for Microsoft noted to the BBC that “the vast majority of Microsoft employees in the United States are Americans.” The company employs more than 200,000 people worldwide.
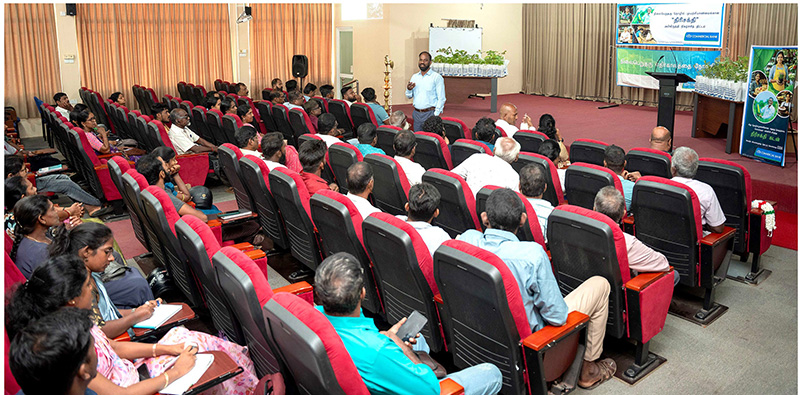
In response to emerging climate risks, the Commercial Bank of Ceylon has launched a proactive initiative through its Development Credit Department, to equip Sri Lanka’s agricultural sector against the potential impacts of the 2026 El Niño climate pattern.
Seeking to move the industry from reactive loss management to early climate preparedness, the Bank partnered with leading state universities to execute a two-part educational and technological intervention in September 2026.
The initiative comes at a critical juncture. Sri Lanka’s Department of Meteorology reported an 80% probability of El Niño conditions emerging between June and August 2026, with effects expected to persist through November and beyond. As highlighted by the Food and Agriculture Organization (FAO), El Niño acts as a risk multiplier for rural livelihoods, food production, and water supply.
To mitigate these threats, the Bank’s initiative creates a collaborative network uniting academic institutions, agricultural extension services, technology providers, farming communities, and the financial sector. The awareness programme on El-Niño and its impact on agriculture was supported by 12 Commercial Bank branches, and engaged with more than 1,100 farmers at 15 diverse locations, including Vattapalai, Muththajankaddu, Palampas, Oddusuddan, Siyambalanduwa, Lindula, Neluwa, Kalawana, Pannala, Madampe, Mannar, Vavuniya and Kumalamunai.

Showers above 75 mm are likely at some places in the Western, Sabaragamuwa, Central, Southern, Uva and North-Western provinces and in Anuradhapura and Mannar districts.

New prison regulations for monks serving jail terms soon: President’s Office

CP alleges NPP has taken the blame for illegal US sanctions on Iranian vessels

Ex-Tiger witness claims Ekneligoda proposed to fire missile at MR’s plane

Chandrasekaran welcomes Indian stand of Katchatheevu

Alleged killer of couple apprehended

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Features4 days ago
The Sri Lankan who made Scottish history
-
 Features6 days ago
Preventing grievances from becoming communal
-
 Sports4 days ago
Nissanka absence opens door for Sri Lanka’s young guns
-
 News5 days ago
Gnansara Thera to be assigned to prison printing section: Officials
-
 News3 days ago
NDB fraud Rs 60mn more than reported
-
 News3 days ago
Removing monk’s robes matter for Sangha to decide: Mahanayake Theras
-
 Features4 days ago
Future of Sri Lanka’s state university system: Should it be shut down and reopened?
-
 News5 days ago
OIC of FCID summoned before Maligakanda Magistrate