Business
DFCC Bank forges ahead amidst a challenging environment


Financial Results for the year ended 31 December 2021
DFCC Group recorded a PAT of LKR 3.7 Bn.
Advances grew by LKR 64 Bn to LKR 366 Bn (21% growth)
Deposits grew by LKR 10 Bn to LKR 320 Bn (3% growth)
The DFCC Group comprises of DFCC Bank PLC (DFCC), and its subsidiaries – Lanka Industrial Estates Limited (LINDEL), DFCC Consulting (Pvt) Limited (DCPL) and Synapsys Limited (SL), the joint venture company – Acuity Partners (Pvt) Limited (APL) and associate company – National Asset Management Limited (NAMAL).
DFCC Bank PLC, the largest entity within the Group, reported a profit before tax (PBT) of LKR 4,326Mn and a profit after tax (PAT) of LKR 3,222 Mn for the year ended 31 December 2021. This compares with a PBT of LKR 3,398 Mn and a PAT of LKR 2,388 Mn in the year prior.
The Group recorded a PBT of LKR 4,859 Mn and a PAT of LKR 3,665Mn for the year ended 31 December 2021, compared with LKR 3,944 Mn and LKR 2,847 Mn, respectively, in 2020. All the member entities of the Group made positive contributions to this performance.
The basic earnings per ordinary share (EPS) of the Bank improved to LKR 10.14 for the year ended 31 December 2021 from LKR 7.83 for the comparative year 2020, recording an increase of 29%.
The Bank’s Return on Equity (ROE) improved to 6.55% during the year ended 31 December 2021 from 4.93% recorded for the year ended 31 December 2020. The Bank’s Return on Assets (ROA) before tax for the year ended 31 December 2021 is 0.91%, against a figure of0.78% for the year ended 31 December 2020.
Net Interest Income
The Bank recorded LKR 12,653 Mn in net interest income (NII), which is a 15% increase year on year. This contributed to an increase in interest margin from 2.53% in December 2020 to 2.66% in December 2021.
Other Operating Income
Due to travel restrictions imposed during the year to curb the spread of the pandemic, business momentum was noticeably negatively affected.
The Bank staff at Head office and across branch network working continuously over the year has helped the Bank to increase non-funded business. This effort was fruitful as it resulted in an increase in net fee and commission income to LKR 2,596 Mn for the year ended 31 December 2021, up from LKR 2,061 Mn in the comparative year. Other operating income has increased mainly due to increases in dividend income and gains on the sale of fixed income securities during the year ended 31 December 2021.
Impairment Charge on Loans and Other Losses
Impairment provisions for the year ended 31December 2021 was LKR 4,485 Mn compared to LKR 3,298 Mn in the year prior. The NPL ratio increased from 5.56% in December 2020 to 5.60% in December 2021. In order to address the current and potential future impacts of Covid-19 and other prevailing economic conditions on the lending portfolio, the bank has made adequate impairment provisions, as at 31 December 2021, by introducing changes to internal models to cover unseen risk factors in the present highly uncertain and volatile environment, including additional provisions made for the Bank’s exposure to risk elevated sectors.
Operating Expenses
The Bank’s operating expenses increased from LKR 7,387 million during the year prior to LKR 8,381 million during the year under review, primarily due to increases in transport costs, as result of special transport facilities provided to staff due to covid restrictions and non-availability of public transport, along with all other additional expenses incurred in keeping and maintaining a safe and healthy environment within the Bank’s premises, to support client engagements and servicing. During the year, the Bank also created multiple channels to enhance service delivery to customers through a strong digital drive, providing access to uninterrupted banking services during difficult times. This resulted in an increase in IT related expenses in order to support the infrastructure upgrades. However, the numerous process automation and workflow management systems introduced during the year under review helped to facilitate effective cost controls, which resulted in operating expenses being curtailed and managed at these levels.
Other Comprehensive Income
Investments in equity securities and treasury bills and bonds (fixed income securities) are classified as financial assets and their change in fair value is recorded through other comprehensive income. Accordingly, a fair value loss of LKR 36Mn and a net fair value loss of LKR 2,469Mn were recorded on account of equity and fixed income securities, outstanding as at 31 December 2021 respectively. Unfavourable movements in Treasury bill and bond yields resulted in the fair value loss of LKR 4,532 Mn during the year. A gain of LKR 2,062 Mn was recycled through the Income statement by disposing of selected Treasury bill and bond holdings, originally categorized under fair value through other comprehensive income (FVOCI), with the objective of cash flow management to support loans and advance growth in line with projections. The action also goes in tandem with the bank’s expectations with regard to the domestic interest rate trend, going forward.
Business Growth
Despite the challenging business environment, the Bank continued its growth strategy by increasing both its deposit and loan portfolios during the year ended 31 December 2021. The loan portfolio grew by LKR 63,991 Mn to record LKR 365,901 Mn compared to LKR 301,909 Mn as at 31 December 2020, recording an increase of 21%. The Bank’s deposit base also experienced a growth of 3%, recording an increase of LKR 9,834 Mn to LKR 319,861 Mn from LKR 310,027 Mn as at 31 December 2020. This resulted in recording a loan to deposit ratio of 114%. Further CASA ratio improved to 31.25% as at 31 December 2021. Funding costs of the Bank were also contained by using medium to long-term concessionary credit lines. When these concessionary term borrowings are considered, the CASA ratio further improved to 36.47% as at 31 December 2021.
DFCC Bank continued its approach to tap local and foreign currency related long to medium- term borrowing opportunities to facilitate lending to deserving segments of the market whilst maintaining a high-quality portfolio.
Equity and Compliance with Capital Requirements
In order to support future growth as a full-service retail bank, the Bank has consistently maintained a capital ratio above the Basel III minimum capital requirements. As at 31 December 2021, the Bank has recorded Tier 1 and total capital adequacy ratios of 9.31% and 13.03%, respectively which is comfortably above the minimum regulatory requirements of 8% and 12% including capital conservation buffer of 2%. The Bank’s Net Stable Funding Ratio was 122.43%, which is well above the regulatory minimum of 100%.
CEO Comment
“Ensuring that we run our business responsibly, delivering profit with purpose, DFCC Bank will always place our customers at the forefront of everything we do. As a customer centric, digitally enabled bank, we will continue to be a source of stability to our customers and deliver value through an unmatched, top-of-the-line customer experience.
In line with our stated vision, the Bank embarked upon implementing a state of the art, core banking system which went live in October 2021. Considering the magnitude and complexity of the implementation, we have had to face some unforeseen challenge and I take this opportunity to express our sincere thanks and gratitude to all our clients, who have been understanding and patient with us this year, as we continuously strive to ensure a more futuristic, digitally-enabled system for our clients.
Despite the unprecedented challenges faced due to the ongoing pandemic, staff of DFCC Bank have and will continue to work with commitment to combat the negative socio-economic effects that have impacted our customers and assist them through tailor made financial solutions. We will continue to introduce banking services that put safety and security at the forefront and ensure that our internal processes are aligned with these same principles to serve our customers better.
We have a strong asset base to be deployed, but nothing is more important than the loyalty we earn from customers, not just by keeping their money and their data safe, but by offering products and services that meet their financial needs and requirements. This loyalty generates both more predictable returns and keen insights, enabling us to continuously improve our services and exceed customer expectations.”
By Ifham Nizam
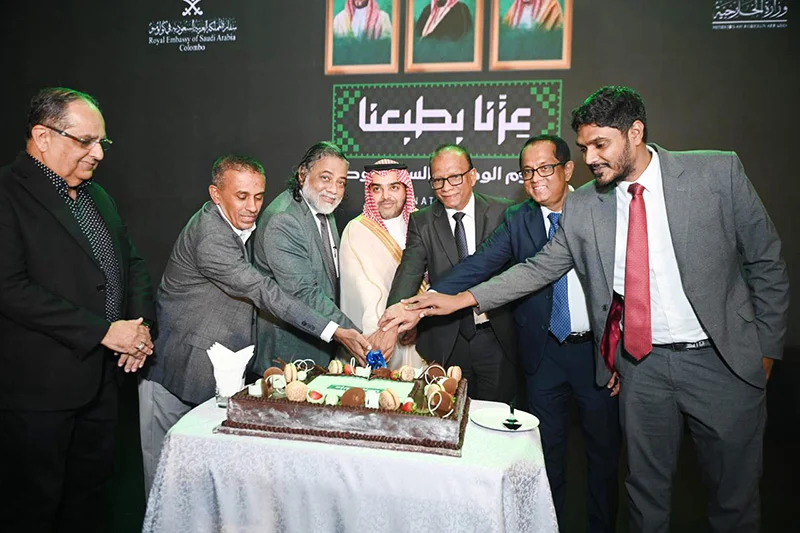
Sri Lanka is pitching Saudi Arabia for greater investment and deeper trade ties, seeking to attract Saudi capital into new development opportunities while aligning bilateral economic cooperation with the Kingdom’s ambitious Vision 2030 agenda, Ports and Civil Aviation Minister Anura Karunathilaka, chief guest at Saudi Arabia’s 96th National Day celebrations in Colombo, said.
Addressing the National Day reception at ITC Ratnadipa, Karunathilaka said Sri Lanka was keen to identify new areas of economic cooperation with the Kingdom and create fresh opportunities for Saudi investors and businesses.
‘We look forward to creating new opportunities for the people of both countries by working in cooperation with Saudi Arabia’s Vision 2030 and its broader development initiatives, he said.
The minister said Sri Lanka wanted to move beyond its existing development cooperation with Saudi Arabia and build a broader economic partnership encompassing investment, trade and new development projects.
He noted that Saudi Arabia had already made a substantial contribution to Sri Lanka’s development. Since 1981, the Kingdom has provided concessional financing amounting to around Saudi Riyals 1.5 billion for 13 projects in Sri Lanka, supporting key sectors including energy, healthcare, education, drinking water and infrastructure.
Karunathilaka said Sri Lanka appreciated this support and was keen to build on the foundation created by those projects by opening further avenues for Saudi investment.
The minister’s investment pitch comes as Saudi Arabia advances its Vision 2030 programme, with the Kingdom seeking to diversify its economy and develop new international partnerships. Sri Lanka, meanwhile, is seeking to attract investment and expand economic opportunities through closer engagement with international partners.
Karunathilaka also highlighted the strong people-to-people links between the two countries, noting that nearly 250,000 Sri Lankans currently work and reside in Saudi Arabia.
‘They serve as an important bridge between our two countries and contribute significantly to strengthening the people-to-people ties between Sri Lanka and Saudi Arabia, he said.
He expressed appreciation for Saudi Arabia’s continued assistance to Sri Lanka and thanked the Saudi government for the facilities extended to Sri Lankan Muslims undertaking Hajj and Umrah pilgrimages.
Karunathilaka said Sri Lanka looked forward to working more closely with Saudi Arabia to strengthen political relations, broaden investment opportunities and enhance development cooperation.
Yaser Abdulrahman Al-Hazme, Chargé d’Affaires of the Royal Embassy of Saudi Arabia to Sri Lanka, said the embassy remained committed to strengthening bilateral relations by promoting political, economic and cultural communication between the two countries.
‘The embassy of the Kingdom of Saudi Arabia in Colombo has been keen during the past period to strengthen bilateral relations between the two countries by playing its role in supporting political, economic, and cultural communication, Al-Hazme said.
Al-Hazme also highlighted the embassy’s role in strengthening communication between Saudi and Sri Lankan institutions and following up on the interests of Saudi citizens in Sri Lanka.
‘On this precious national occasion, I extend my sincere thanks and appreciation to the government and people of the Democratic Socialist Republic of Sri Lanka for the attention and care given to relations between our two countries, and for the constructive cooperation that has contributed to strengthening the bonds of friendship and partnership between the Kingdom and Sri Lanka, he said.
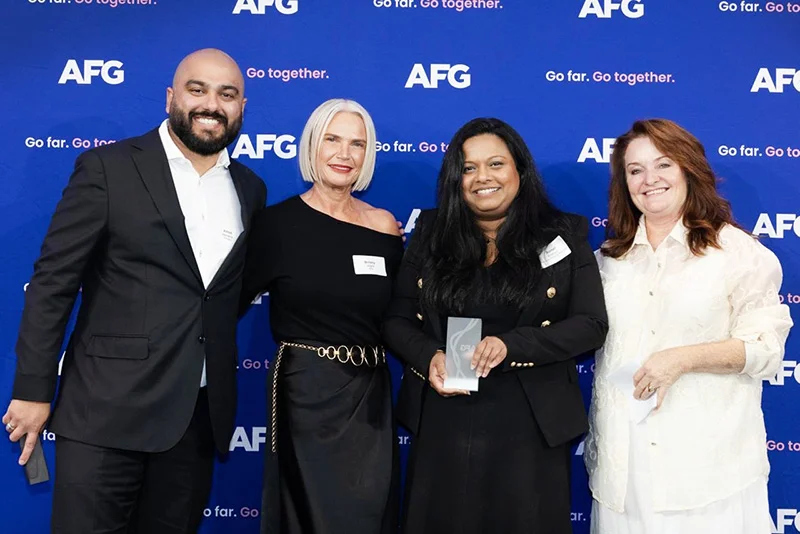
Australian finance professional Sonali Rodrigo has been recognised with the prestigious AFG Women on the Move Scholarship, presented by Australian Finance Group (AFG), in recognition of her leadership, industry contribution and impact spanning more than two decades in Australia’s finance industry.
The AFG Women on the Move program is dedicated to supporting and advancing women in the finance and mortgage broking industry, recognising individuals who demonstrate leadership, professional contribution, growth, impact and a commitment to empowering other women. The scholarship is supported by leading industry partners, including HSBC and Thinktank.
Sonali’s career spans more than 20 years in Australia’s finance industry, encompassing senior leadership, financial advisory and governance roles. Alongside her professional responsibilities, she has actively mentored and supported women in their career development, contributed to financial literacy, and helped individuals make more informed financial decisions. Her recognition reflects both her professional achievements and the broader impact of her leadership, particularly in creating opportunities and empowering the next generation of women in finance.
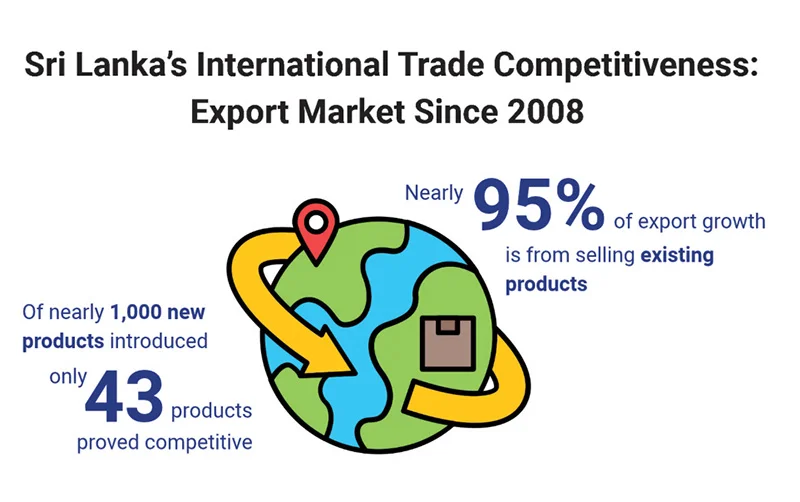
Institute of Policy Studies of Sri Lanka (IPS)
Continued From last Friday
Regional infrastructure improvements beyond the Western Province are essential to close market-access gaps and improve efficiency. The Western Province alone generates 42% of Sri Lanka’s GDP, but the dynamics of such agglomeration may also be highly underestimated. Officially, barely a fifth is deemed ‘urban’ in the province, but IPS re-estimates from the 2024 census using population density and infrastructure access, place the true figure at nearly 61%. The absence of strong secondary cities and industrial clusters outside the province reduces the potential gains from this agglomeration, thereby weakening incentives for firms to locate elsewhere or decentralise operations.
Fiscal incentives can promote decentralised corporate operations by offering tax rebates, lower property taxes, and land access in secondary cities like Kalutara and Gampaha, leveraging the connectivity of Southern and Colombo-Katunayake Expressways. The Hambantota seaport and airport, along with Koggala and Mirijjawela Export Processing Zones, can help develop the Southern Province through geography-based tax concessions.
Immediate measures, such as pricing vehicle entry into Colombo city will support regional agglomeration while tackling the acute problem of city congestion. Adopting a low-cost, technology-anchored free-flow method, similar to the Automated Number Plate Recognition (ANPR) currently used in commercial parking facilities for vehicles entering the city, is one such means. Installing high-mounted overhead ANPR gantries at key arterial entry points can operationalise congestion pricing without disrupting traffic speed. Fee collection can use a system like E-Tags electronic toll collection on expressways, integrated with digital payment gateways like GovPay and LankaQR for dynamic, time-of-day variable pricing.
The renewable energy transition is vital to drive competitiveness, external shock resilience, and green growth. Sri Lanka’s transition to renewable energy (RE) has advanced from a mere aspiration to tangible progress. Yet, the evidence suggests the transition is advancing faster on the generation side than the system built to absorb it. Transmission capacity, market design, financing channels, and digital infrastructure have not kept pace with capacity additions, and this gap is what will determine the pace of the transition through 2030.
Capital spending on transmission must be ring-fenced by legally, operationally, and financially separating the electricity grid (the transmission network) from the rest of the energy sector or by the broader government budget as a protected public investment within the medium-term budget framework. Funding should shift from general budget support to dedicated multilateral facilities, reinforced by sovereign guarantees for eligible borrowing. To safeguard public funds, this must be paired with a clear tariff pass-through mechanism that effectively limits open-ended Treasury exposure.
To build market trust, domestic budget funding should be earmarked for market-design technical assistance, signalling strong policy ownership rather than relying on external donors. Transparency too should be strengthened by publishing a firm implementation timeline in the Budget statement and fully disclosing long-term fiscal commitments from Power Purchase Agreements, capacity arrangements, and ancillary services.
(Concluded)

Cabinet nod to increase the number of new automated passenger clearance gates at the Bandaranayake International Airport to 12
Draft Bill for amending the Trust Ordinance
Implementing further relief programme to Public sffected by the Middle East conflict situation
Establishment of a Spectrum Management and Monitoring System and a Quality of Service and Quality of Experience System for the Telecommunications Regulatory Commission of Sri Lanka
Appointment of a Committee for the Restitution of Sri Lankan Cultural Heritage Held Abroad
Ten-Year National Action Plan on the Social Protection Sector (2026–2035)

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 News7 days ago
Mastermind Naufer Moulavi among 15 found guilty
-
 Midweek Review7 days ago
Thileepan’s fast unto death: An authentic narrative that many missed
-
 Latest News6 days ago
Showers above 100 mm are likely at some places in the Western, Sabaragamuwa, Central and North-western provinces and in Galle and Matara Districts
-
 Editorial7 days ago
Big Bad Bills
-
Editorial6 days ago
Crimes punished and unpunished
-

 Features5 days ago
Beyond traditional jobs: Why Sri Lanka needs to facilitate the gig economy
-

 News7 days ago
No referendum needed for passage of 22 A: SC
-
 News7 days ago
One clause in Anti-Corruption (Amendment) Bill requires referendu: SC