Business
Stock market hits record high; 14,000 mark breached


By Hiran H. Senewiratne
Stock market activities were heavily bullish yesterday and the All Share Price Index hit a record high, breaching the 14,000 mark. The reason being that local and foreign investors are positive that the external debt restructuring process would end successfully, market analysts said.
The index has been steadily rising since November and both indices moved upwards. The All Share Price Index went up by 150 points, while the S and P SL20 rose by 42.8 points. Turnover stood at Rs 7.3 billion with eleven crossings.
Those crossings were reported in Alumax, which crossed 32.4 million shares to the tune of Rs 406 million, its shares traded at Rs 12.60, JKH 13.7 million shares crossed for Rs 290 million; its shares traded at Rs 21.30, Asiri Hospital PLC 9.3 million shares crossed to the tune of Rs 85.5 million; its shares traded at Rs 25.50, NDB 1 million shares crossed for Rs 85.5 million; its shares traded at Rs 85.50, Pan Asian Bank 2 million shares crossed for Rs 56 million; its shares traded at Rs 28, LMF 1.2 million shares crossed to the tune of Rs 42.6 million and its shares traded at Rs 36, Ambeon Capital 1.3 million shares crossed for Rs 29.9 million and its shares traded at Rs 23, Sampath Bank 250,000 shares crossed for Rs 26 million; its shares sold at Rs 104, HNB 100,000 shares crossed to the tune of Rs 24.7 million and its shares traded at Rs 247, Tokyo Cement 330,000 shares crossed for Rs 22.1 million; its shares traded at Rs 60 and Commercial Bank (Non- Voting) 200,000 shares crossed for Rs 20 million; its shares traded at Rs 100.
In the retail market companies that mainly contributed to the turnover were; JKH Rs 682 million (31.9 million shares traded), LMF Rs 585 million (16.7 million shares traded), PickMe Rs 297 million (4.4 million shares traded), Sampath Bank Rs 239 million (2.2 million shares traded), Commercial Bank Rs 238 million (1.8 million shares traded) and ACL Cables Rs 203 million (1.8 million shares traded). During the day 282million share volumes changed hands in 33,300 share transactions. .
Market participants said that local high networth individuals and institutions were taking positions in anticipation of company profiles improving. Investor interest in banking stocks led the charge originally amid expectations of the successful completion of the international sovereign bond restructuring.
Then interest was seen in companies with exposure to the automotive industry on the anticipated lifting of the vehicle import ban. Diversified financials saw stock prices rising especially in JKH. Tourism and construction industries have also attracted investor interest amidst promising tourist arrivals and increasing projects respectively.
Yesterday the rupee was quoted at Rs 290.22/280 to the US dollar in early trade, stronger from the previous day’s close of Rs 290.30/35, dealers said, while bond yields were steady ahead of an auction.
A bond maturing on 15.12.2026 was quoted at 9.35/50 percent, flat. A bond maturing on 15.10.2027 was quoted at 10.90/11.00 up from 9.85/10.00 percent Wednesday. A bond maturing on 15.02.2028 was quoted at 10.15/24, down from 10.25/35 percent. A bond maturing on 15.10.2028 was quoted at 10.45/50, down from 10.50/60 percent. A bond maturing on 15.09.2029 was quoted at 10.70/80, up from 10.75/90 percent. (Colombo/Dec12/2024). Sri Lanka auctioned Rs 132.5 billion of Treasury bonds yesterday.
Fund says discussions will continue on policies and parameters needed to complete the Seventh Review
By Sanath Nanayakkare
Sri Lanka’s latest talks with the International Monetary Fund (IMF) have concluded without a staff-level agreement on the policies and parameters required to complete the Seventh Review of its Extended Fund Facility (EFF), leaving further discussions ahead as the government prepares its next Budget.
An IMF team led by Mission Chief Evan Papageorgiou visited Sri Lanka from September 10 to 23 for discussions on the Seventh Review and the 2026 Article IV Consultation.
The Fund said the discussions with Sri Lankan authorities had been productive, but would continue in the near term towards reaching agreement on the parameters and policies needed to complete the Seventh Review.
The outcome therefore represents a delay in reaching the formal staff-level milestone rather than a breakdown in negotiations.
The latest mission comes as Sri Lanka moves from economic stabilisation towards longer-term structural transformation, while continuing to face external shocks and domestic fiscal pressures.
The IMF said economic activity expanded by 4.2 percent in the second quarter of 2026, marking the 11th consecutive quarter of growth. At the same time, the Fund cautioned that downside risks remained, particularly amid an uncertain external environment.
Gross official reserves had risen to US$6.9 billion by the end of August, while the banking sector remained well capitalised and profitable, providing some buffers against external pressures.
A major focus of the IMF’s latest assessment was Sri Lanka’s revenue position.
The Fund said developing and implementing a strong medium-term revenue strategy would be critical to sustaining revenue mobilisation and strengthening fiscal resilience.
It stressed the need to broaden the tax base, rationalise tax exemptions and incentives, and strengthen revenue administration and compliance.
The IMF also emphasised the importance of maintaining cost-recovery energy pricing and improving the efficiency and fairness of the tax system in order to reduce fiscal vulnerabilities.
These issues assume particular significance as the government prepares its next Budget, with the authorities seeking to balance revenue mobilisation and fiscal consolidation against the need to sustain economic recovery.
The Fund’s latest position does not indicate that negotiations have broken down. Rather, the IMF has said that discussions will continue towards reaching agreement on the remaining policies and parameters required to conclude the Seventh Review.
The latest talks follow the combined Fifth and Sixth Reviews, for which IMF staff and Sri Lankan authorities reached a staff-level agreement in April, subject to completion of the remaining requirements before consideration by the IMF Executive Board.
For Sri Lanka, the immediate challenge is therefore to preserve the gains made in macroeconomic stabilisation while addressing the remaining issues under the IMF programme and preparing a Budget capable of supporting longer-term fiscal and economic resilience.
With further discussions expected in the near term, the Seventh Review remains a work in progress as Sri Lanka enters another critical stage of its economic reform programme.
Notably, the IMF has yet to publicly specify the outstanding issues that remain to be resolved.
Business
UK digital expertise and Sri Lankan business leaders unite to explore growth through technology

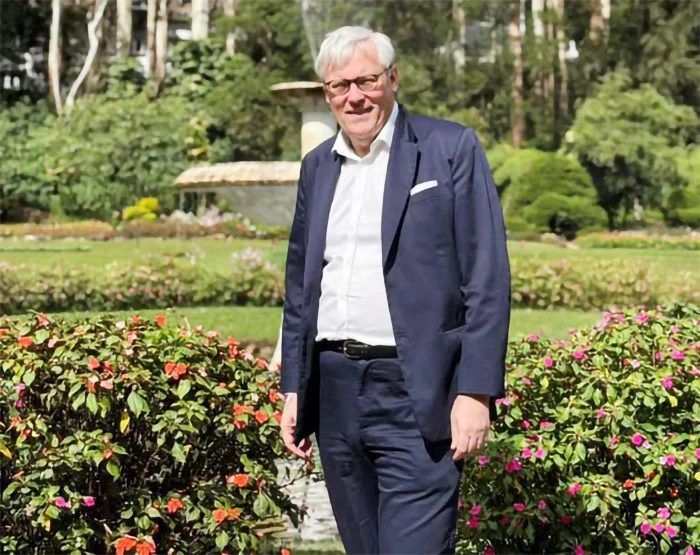
British High Commissioner Andrew Patrick hosted UK digital product consultancy Apadmi at Westminster House, his official residence in Colombo, for an invite-only forum bringing together senior business leaders from across Sri Lanka’s retail, banking, telecommunications, hospitality and public sectors.
The event, “Turning Digital Assets into Growth Engines”, marked Apadmi’s first official event in Sri Lanka since establishing its Colombo office in 2025, and was delivered in partnership with the British High Commission as part of ongoing efforts to strengthen UK and Sri Lanka commercial and technology ties.
Guests were welcomed by High Commissioner Andrew Patrick, followed by a keynote from Niresh Muthuratnanandan, Head of Omni Commerce, Digital & Loyalty at Keells Supermarkets, who spoke about the launch of the Keells Nexus app and the modernisation of a loyalty programme serving 2.9 million members.
A panel discussion followed, hosted by Mark Collin, Chief Growth Officer at Apadmi, and featuring Malik Induruwana, Chief Information Officer at HSBC Sri Lanka & Maldives; Jiffry Zulfer, Founder and CEO of PickMe; Uthpala Pinnaduwahewa of Hatton National Bank; and Marcus Hadfield, Chief Strategy Officer at Apadmi.
The discussion centred on the commercial opportunity created by Sri Lanka’s rapid mobile adoption. According to [source], mobile data usage in the country reached 1.03 million terabytes in Q2 2026, a 31% increase year on year, against 29.4 million mobile subscriptions. With 71% of devices now smartphones or tablets, speakers discussed how Sri Lankan businesses could convert growing digital engagement into customer loyalty, new revenue and operational efficiency.
British High Commissioner Andrew Patrick said:
“It was a pleasure to welcome Apadmi and such a strong group of business leaders to Westminster House for this event. The UK and Sri Lanka have a longstanding partnership, and digital innovation is an increasingly important part of that relationship. Apadmi’s decision to establish a base in Colombo reflects the confidence that UK companies have in Sri Lanka’s digital economy, and I look forward to seeing this partnership continue to grow to the benefit of both our countries.”
Mark Collin, Chief Growth Officer at Apadmi, said:
“Being hosted by the British High Commission was a real privilege, and a fitting way to mark the next stage of our commitment to Sri Lanka. To bring leaders from Keells, HSBC, PickMe and Hatton National Bank into the same room says a great deal about the ambition here. We opened our Colombo office because we believe Sri Lanka is at a genuine turning point; the talent is exceptional, and we are proud to be building here for the long term.”
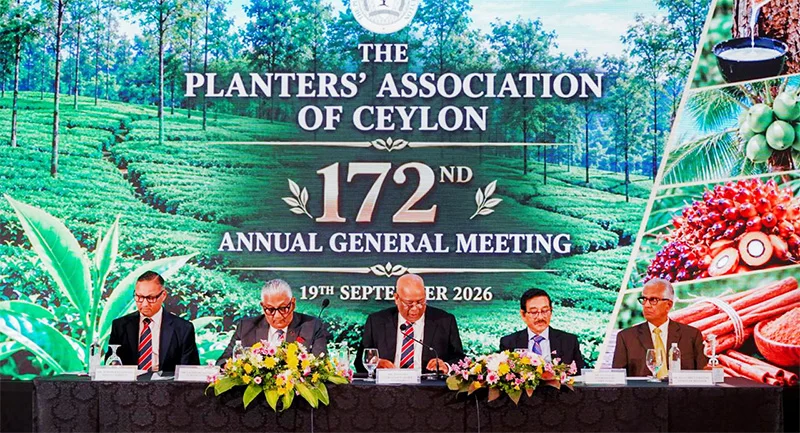
Malwatte Valley Plantations PLC Director / CEO, Shanaka Samaradiwakara was appointed as Chairman of the Planters’ Association of Ceylon (PAC), while Kahawatte Plantations PLC Director / CEO Binesh Pananwala, was appointed as Deputy Chairman at the Association’s 172nd Annual General Meeting (AGM) on 19 September at the Cinnamon Grand.
The event was graced by Central Bank of Sri Lanka Governor, Dr. Nandalal Weerasinghe and Sri Lanka Tea Board Chairman, Raj Obeyesekere as Chief Guest and Guest of Honour respectively.
In his inaugural address, Samaradiwakara outlined a five-point vision for the plantation sector, focusing on value addition, research and development, land-use and productivity, irrigation and long-term security of tenure. He emphasised that the future of commercial agriculture in Sri Lanka would hinge on how effectively all industry stakeholders could work together, while maintaining clear understanding of the ground realities faced by producers.
Value-added tea accounted for more than 50% of total tea export volumes in 2025. Samaradiwakara noted Regional Plantation Companies (RPCs) have accounted for the majority of that volume through continuous investments, including most recently in matcha, green tea and artisanal teas.
In that context, he sought the support of the Sri Lanka Tea Board and the export sector to protect this emerging high value segment, given that significant quantities of green tea and other high-value teas remain unsold at auction while similar products continue to enter the country. “We respectfully request the authorities to review this matter and introduce appropriate measures to support domestic production and value addition,” he stated.
On research and development, he observed that commercially viable alternatives to several essential crop protection products remain limited. Accordingly, he called on the Tea, Rubber and Coconut Research Institutes to lead the development of practical, scientifically proven alternatives, while stressing that disease threatening the rubber industry requires immediate attention. “We cannot afford to repeat the experience of the coffee industry, where coffee blight devastated the sector,” he added.
Turning to issues around land-use policies and productivity, he noted that RPCs have diversified for over two decades in response to changing rainfall patterns, introducing crops such as oil palm, pepper and avocado. He warned that these investments are increasingly threatened by unsupportive policy, agricultural theft and crop damage by wild animals, costing companies millions of rupees each month in security. “It is imperative that these investments are protected through strong enforcement, appropriate regulatory reforms, and effective measures to address both agricultural theft and crop damage,” he noted. On irrigation, he appealed to the Government to relax archaic restrictions on groundwater use and simplify approvals for drilling tube wells in order to enhance climate resilience.
Addressing security of tenure, he highlighted that replanting often takes more than a decade to generate meaningful revenue, and that uncertainty over lease extensions is making it harder for RPCs to attract foreign direct investment and long-term financing. “If we are to attract fresh capital, accelerate replanting, modernise our plantations and improve productivity, security and certainty of tenure are mandatory,” he added.

Muhammad Shahzad smashes fastest first-class hundred by a Pakistani batter

Gul, Kharote spin Afghanistan to victory over Japan in Asian Games opener

Showerss above 100 mm are likely at some places in the Western, Sabaragamuwa, Central and North-western provinces and in Galle and Matara Districts

Mirabai Chanu wins Asian Games silver as Ri breaks weightlifting record

Trump greets China’s Xi Jinping on arrival for three-day US

BASL calls for conscience vote on 22nd Amendment

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 News6 days ago
Shanakiyan urges urgent action over reported death sentence for Lankan in Saudi Arabia
-

 News7 days ago
Bid for Basil’s extradition nears final stage: Police
-
 News5 days ago
Namal Rajapaksa Buddhist gambit fails, bail denied
-
 Features5 days ago
Why the spelling Sri Lankan names in English vary
-
 Features5 days ago
Three bands, a new identity: Sri Lankan wolf snake recognised as distinct species
-
 Business5 days ago
SLIIT holds largest-ever convocation
-
 News5 days ago
Govt monitors reported Saudi death sentence – Foreign Ministry
-
 News5 days ago
Vehicle prices drop by up to Rs. 1 mn, says importers’ body