Business
Is wealth tax the solution to Sri Lanka’s low tax revenue collection?

By Sathya Karunarathne
Successive governments have run fiscal deficits. Inadequate revenue collection and unrestrained government expenditure have worsened the country’s fiscal position.
Tax revenue which averaged over 20% of GDP in 1990 has declined to under 10% of GDP in 2020. Ad hoc tax policy changes have significantly eroded the tax base. Weak tax administration has also contributed to the sharp decline in tax collection.
While tax revenue has contracted, government expenditure has ballooned over time. Today, government revenue is not sufficient even to meet its expenditure on salaries and wages and transfers and subsidies to households which include pension payments and social welfare payments such as Samurdhi.
In this context, there are various proposals put forward to raise government revenue. One proposal is the reintroduction of the wealth tax.
A wealth tax is expected to bridge the gap between the rich and the poor, achieving equality. This tax shifts the tax burden to affluent households, taxing an individual’s net wealth, which is the market value of total owned assets. Proponents of wealth taxation argue that this is a progressive system of taxation and is a more powerful tool in comparison to income, estate or corporate taxes as it addresses the issue of wealth concentration.
Moreover, a tax should ideally satisfy basic characteristics of taxation: it should not be distortionary; it should be fair, and it should not be difficult to collect.
The rationale for a wealth tax
One of the earliest proponents of the wealth tax for developing countries was Nicholas Kaldor. Based on his recommendation, a wealth tax together with an income tax, expenditure tax and a gift tax were introduced in Sri Lanka in 1958.1 However, these new taxes yielded little revenue due to difficulties in determining the tax base and problems in administration. Following the recommendation of the Tax Commission in 1990,2 the government abolished the wealth tax from the year of assessment 1992/1993.3
Wealth taxes have mainly been implemented in European countries. In 1990, twelve countries in Europe had a wealth tax. Today, there are only three: Norway, Spain, and Switzerland. Several non-European countries have also imposed wealth taxes from time to time including such as Argentina, Bangladesh, Colombia, India, Indonesia, Pakistan
In recent times there has been renewed interest in wealth taxes. Presidential candidates in the US proposed various forms of a wealth tax. In the UK and France, there were proposals to impose “super taxes” on the rich. The primary justification was to address the increasing inequality in society.
Issues with a wealth tax
Despite renewed interest in the wealth tax as a progressive tax based on equity, it scores poorly on the criteria of efficiency, and administrative feasibility.4
Many factors have justified the repeal of wealth taxes in OECD countries. The reasons cited are related to efficiency costs, risk of capital flight particularly in light of increased capital mobility and wealthy taxpayers’ access to tax havens, failure to meet redistributive goals as a result of narrow tax bases, tax avoidance and evasion, high administrative and compliance costs compared to limited revenues (high cost yield ratio).5
To understand the efficiency costs of wealth taxes one can look at taxing a person’s wealth accumulated through savings. Despite the common consensus that taxing savings is an effective way to redistribute, a person’s saving decisions reveal little about their underlying lifetime resources and wellbeing. It only reveals their preference to consume tomorrow rather than today. Thereby a wealth tax imposes a tax on those who prefer to spend their money later as opposed to taxing the wealthy.6 Efficiency costs refer to the reduction of the welfare of the taxed individuals by more than $1 to generate $1 of revenue.7 Therefore, the efficiency cost of a wealth tax in terms of taxing savings is a reduction of future consumption that can be bought with earnings, reducing incentive to work for those who prefer to consume the proceeds later and reducing incentive for young people to save for their retirement.8
Capital flight is the possibility of holding assets outside of one’s resident country without declaring them.As wealth taxes are imposed on residents it increases the risk of the wealthy reallocating their assets to avoid taxation. Therefore a high tax burden encourages taxpayers to change their tax residence to a lower tax jurisdiction or tax havens.9
Both income-generating and non-income generating assets are taxed under wealth taxation. They can include land, real estate, bank accounts, investment funds, intellectual or industrial property rights, bonds, shares, and even jewellery, vehicles, art and antiques.10 However, this tax base for wealth taxes has often been narrowed through exemptions. These exemptions have been justified most commonly on the grounds of social concerns such as the negative social implications of taxing pension assets. Further liquidity issues (eg – farm assets), supporting entrepreneurship and investment (eg- business assets), avoiding valuation difficulties ( eg- artwork and jewellery) and preserving countries cultural heritage (eg – artwork and antiques) have also been cited as reasons for wealth tax reliefs. While some of these exemptions can be justified, they have led to the reduction of revenue raised from wealth taxes. They have also contributed to wealth taxes being less equitable as the wealthiest such as businesses benefit from these exemptions defeating the very purpose of imposing a wealth tax which is to meet its redistributive goals.11
Narrow tax bases in wealth taxation often leads to tax avoidance and evasion opportunities. For example, Spain’s 1994 wealth tax exemption for the shares of owner managers resulted in wealthy businesses reorganizing their activities to reap benefits of the exemption resulting in a significant erosion of the wealth tax base.12
Further, several other factors have also discouraged countries to sustain a wealth tax. They are namely, the difficulty in determining the tax base or what assets to be taxed, underreporting and undervaluation of assets, difficulty in measuring wealth taxes13, distinguishing between individuals who are asset rich but cash poor, the constant need to value assets and audit returns increasing administrative and enforcement costs .
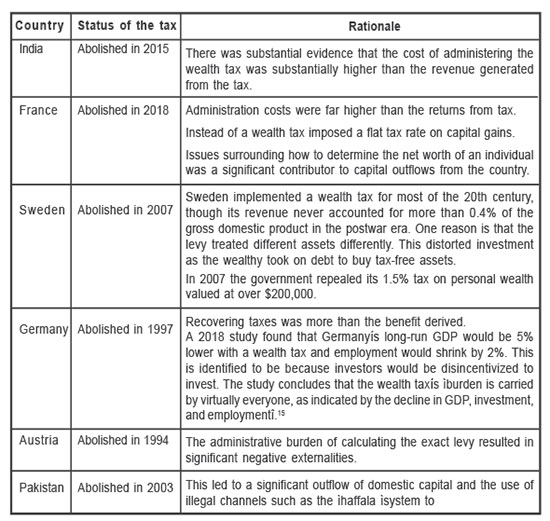
Low revenue collection as well as the other reasons discussed have led to the abolishing of wealth taxes in most countries (See Table 1 for details) . Tax revenue from individual net wealth taxes in 2016 ranged from only 0.2% of GDP in Spain to 1.0% of GDP in Switzerland. Sri Lanka’s experience with wealth taxation was no different with the tax yielding low revenue as reported by the 1990 Tax Commission.14
Conclusion
Taxing the wealth of the rich to generate income and to eliminate economic inequality sounds promising in terms of political debate. However, wealth taxes have failed to generate adequate revenue, failed to meet redistributive goals as a result of narrow tax bases, proven to have high administrative and enforcement costs, resulted in tax evasion and avoidance due to underreporting and undervaluation of assets, increased the risk of capital flight and access to tax havens and may have contributed to the reduction of investment and employment.
Therefore, imposing a wealth tax may not be the ideal policy response to Sri Lanka’s low tax revenue, especially given the country’s previous experience with the tax yielding low revenue.
Sathya Karunarathne is the Research Analyst at the Advocata Institute and can be contacted at sathya@advocata.org. Learn more about Advocata’s work at www.advocata.org. The opinions expressed are the author’s own views. They may not necessarily reflect the views of the Advocata Institute, or anyone affiliated with the institute.

HNB PLC, the leading private bank in Sri Lanka, has partnered with IDEAL Motors (Pvt) Limited to provide customers with attractive leasing solutions for brand-new vehicles & generators .
The partnership introduces a range of benefits designed to support individuals, entrepreneurs, and businesses seeking reliable vehicle and power solutions. Through this collaboration, customers can access structured lease facilities, special interest rates, free life insurance coverage, and attractive discounts through HNB General Insurance.
Commenting on the partnership, HNB, Senior Vice President/ Head of Retail Banking, Kanchana Karunagama, said, “At HNB, we believe that the right financial support can help people and businesses move forward with greater confidence. This partnership with IDEAL Motors shows our commitment to creating meaningful solutions that make vehicle and power investments more accessible, while helping our customers achieve their personal and business aspirations. By combining HNB’s financial expertise with IDEAL Motors’ industry capabilities, we are creating opportunities that support the ambitions of Sri Lankans and contribute towards a stronger, more connected economy.”
Customers purchasing vehicles through IDEAL Motors will also benefit from exclusive offers including free registration, and discounts on Bolero Maxx Pik-Up, Alfa Plus Load Carrier, Mahindra Pik-Up Single Cab, Mahindra Pik Up Double Cab, XUV 3XO vehicles, creating greater value throughout their ownership journey.
IDEAL Motors (Pvt) Limited, Director Legal and Corporate Affairs, Nimesha Welgama, said, “Our collaboration with HNB represents a shared commitment to supporting Sri Lankans in achieving greater financial independence through accessible ownership solutions. By combining IDEAL Motors’ mobility and power solutions with HNB’s financial expertise, we aim to empower individuals and businesses with opportunities that contribute to economic progress and community development. This partnership highlights our vision of creating lasting value by enabling customers to confidently invest in their future.”
With IDEAL Motors recognised for its diverse portfolio of automotive and power solutions, and HNB’s extensive expertise in financial services, the partnership aims to provide a seamless experience from selection to ownership, supported by flexible financing options and customer focused solutions.
The partnership further strengthens HNB’s commitment to supporting economic progress by providing financial solutions that enable customers to invest in personal mobility, commercial growth, and business continuity. Through collaborations with leading industry partners, HNB continues to expand opportunities for Sri Lankans while delivering a banking experience built around accessibility, trust, and value.
Business
Sri Lanka Insurance Corporation General and the Ministry of Education committed to protect Sri Lanka’s schoolchildren

Sri Lanka Insurance Corporation General Ltd (SLICGL) and the Ministry of Education, Higher Education and Vocational Education share a commitment to protect Sri Lanka’s children throughout their school education. The pledge is delivered through the Suraksha Student Insurance Scheme, which protects over 4 million school children.
The Government of Sri Lanka, through the Ministry of Education, Higher Education and Vocational Education, provides the Suraksha Student Insurance Scheme free of charge to schoolchildren throughout the country. SLICGL is proud to partner with the Ministry in delivering this national initiative, which helps safeguard students against the financial impact of unforeseen circumstances.
Eligible students include those aged 5-21 years in Grades 1-13 from government schools, government-approved private schools, and Pirivena education, as well as students aged 4-21 years in assisted special schools.
The scheme provides hospitalisation, outpatient and critical illness cover, as well as personal accident cover for permanent and temporary disability, together with a life insurance benefit for children from low-income families on the death of a parent. Cover applies to incidents within and outside school premises.
For a child, an illness or accident can be far more than a temporary setback. It can place added pressure on a family and, in some circumstances, disrupt schooling. Suraksha acts as a safety net, giving children and their families greater peace of mind and helping them stay in school despite life’s uncertainties. The scheme is easily accessible through SLICGL’s islandwide network of 200 branches and customer service centres.
Children’s Day is a celebration of hope, the hope for every child to have the opportunity to learn, grow and build a better future. Celebrating children also means protection, not for a single day but for every day they spend in the classroom.
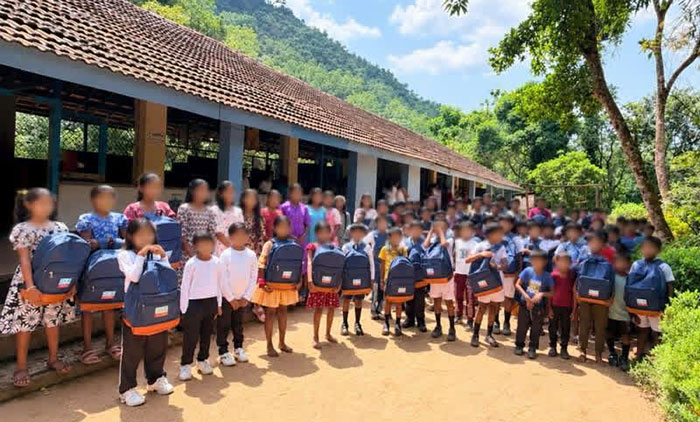
Commemorating Children’s Day, SLICGL extended support towards the educational needs of children at an underprivileged school. The project highlighted the company’s belief in protecting the future not only by being supportive when the unexpected happens, but also in helping create an environment in which children can learn, grow and fulfil their potential.
As Sri Lanka’s National Insurer, SLICGL’s role goes further than protecting people against risk. It is also about contributing to a stronger, safer and more resilient country as children’s education, wellbeing and aspirations contribute directly to help build the journey ahead.
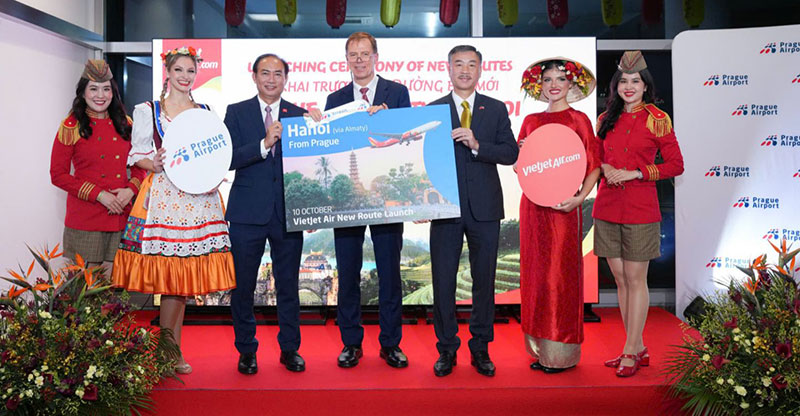
Vietjet, which already flies between Colombo and Ho Chi Minh City, has officially launched new services connecting Hanoi with Almaty, Kazakhstan, and Prague, Czech Republic, as well as Almaty with Prague, expanding its intercontinental network and marking its entry into the European Union. The new air links offer more affordable travel options while fostering greater tourism, trade and cultural exchange between Asia and Europe.
For Sri Lanka, the new routes widen the network that Vietjet is building out of Colombo. The airline has operated non-stop flights between Colombo and Ho Chi Minh City since August 2026, three times a week on Tuesdays, Thursdays and Saturdays, while its new Ho Chi Minh City to Maldives service via Colombo is scheduled to begin on 5 December 2026. With Hanoi now linked to Central Asia and Europe, Sri Lankan travellers have a growing choice of destinations reachable through Vietjet’s extensive network.
The inauguration ceremonies took place at Almaty International Airport and Václav Havel Airport Prague on 10 October, amid a warm welcome from local leaders, residents and visitors. The inaugural flights were greeted with traditional water cannon salutes and performances showcasing local cultural heritage, marking the beginning of new journeys connecting the three regions and welcoming international travellers to Vietnam. Passengers on the inaugural flights also received commemorative gifts from Vietjet and the airports, adding a special touch to their journeys.

AgriConnect Sri Lanka’ to be launched on 30 October to Modernise the Agricultural Sector Through Digitalisation

57th Annual Saints’ Quadrangular Tournament on Saturday and Sunday

Showers or thundershowers will occur at most parts of the island

Prison rules to be revised over monks’ attire

AC President recuses himself from hearing prison attire case pertaining to Gnanasara Thera

Court orders steps to obtain INTERPOL Red Notice against Basil

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 News7 days ago
NDB fraud Rs 60mn more than reported
-
 News7 days ago
Removing monk’s robes matter for Sangha to decide: Mahanayake Theras
-
 News5 days ago
Sri Lanka escalates anti-graft drive with Shiranthi’s jailing
-
 News6 days ago
NPP govt. reminded of its responsibilities as US warship leaves Colombo
-
 Latest News6 days ago
Farhan, Sadaqat help Pakistan ace 183 chase to go 1-0 up
-
 News7 days ago
BHC, Colombo: “LTTE remains a proscribed org. in the UK”
-
 Latest News4 days ago
Farhan and Sadaqat help Pakistan seal series in style
-
 News5 days ago
Iranian ships stranded, Lanka fears US sanctions