News
CB reduces interest rates by 100 basis points to tackle inflation and ease borrowing costs

The Monetary Policy Board of the Central Bank, at its meeting held on Thursday (23), decided to reduce the Standing Deposit Facility Rate (SDFR) and the Standing Lending Facility Rate (SLFR) of the Central Bank by 100 basis points (bps) to 9.00 percent and 10.00 percent, respectively, CB said in a press release.
It said: The Board arrived at this decision following a careful analysis of the current and expected developments in the domestic and global economy, with the aim of achieving and maintaining inflation at the targeted level of 5 percent over the medium term, while enabling the economy to reach and stabilise at the potential level.
The Board took note of possible upside risks to inflation projections in the near term due to supply-side factors stemming from the expected developments, domestically and globally. However, the Board viewed that such near term risks would not materially change the medium-term inflation outlook, as inflation expectations of the public remain anchored and economic activity is projected to remain below par in the near to medium term. Further, the Board viewed that with this reduction of policy interest rates, along with the monetary policy measures carried out since June 2023, sufficient monetary easing has been effected in order to stabilise inflation over the medium term.
Hence, the Monetary Policy Board underscored the need for a swift and full pass through of monetary easing measures to market interest rates, particularly lending rates, by the financial institutions, thereby accelerating the normalisation of market interest rates in the period ahead.
Headline inflation continues to remain low, reflecting subdued demand conditions. Headline inflation, as measured by the year-on-year change in the Colombo Consumer Price Index (CCPI, 2021=100), was recorded at 1.5 percent in October 2023 compared to 1.3 percent in September 2023.
Food inflation continued to be negative (year-on-year) for the fourth consecutive month in October 2023. The National Consumer Price Index (NCPI, 2021=100) based headline inflation (year-on-year) was recorded at 1.0 percent in October 2023, compared to 0.8 percent in September 2023.
Both CCPI and NCPI based core inflation (year-on-year), which reflects underlying demand pressures in the economy, moderated further in October 2023, reflecting the subdued demand pressures in the economy. A one-off upward movement in inflation is expected in the near term, driven mainly by the changes to the Value Added Tax (VAT) proposed by the Government effective January 2024. The spillover effects of tax measures and other developments are likely to be muted due to subdued underlying demand pressures; hence, this rise in inflation is expected to be transitory. Accordingly, headline inflation over the medium term is expected to converge towards the targeted level of 5 percent, supported by appropriate policy measures.
Market interest rates are expected to normalise in the period ahead. Market interest rates continued to adjust downwards, and most benchmark interest rates have declined significantly. Meanwhile, the yields on government securities are also adjusting downwards with falling risk premia. The reduction of policy interest rates by 100 bps in this monetary policy review is expected to create further space for market interest rates to adjust downward and normalise in the period ahead. Reflecting the transmission of the relaxed monetary policy stance, outstanding credit to the private sector by the banking sector expanded on a monthly basis in September as well as in October 2023 based on provisional data. With the moderation of market lending interest rates, credit to the private sector is expected to increase further in the period ahead, thereby supporting the envisaged rebound of domestic economic activity.
The Board anticipates a swift, sizeable and broad-based reduction in overall market lending interest rates in line with the monetary policy easing measures effected since June 2023. Such adjustment in interest rates is imperative to ease the domestic monetary conditions further. The Board stressed the need for all licensed banks to take swift measures to reduce market lending interest rates to ensure that the benefits of the series of monetary policy easing measures are adequately passed on to businesses and households.







The Bar Association of Sri Lanka (BASL) yesterday called on all political parties, represented in Parliament, to allow their members to vote on the proposed 22nd Amendment to the Constitution according to their conscience, stressing that the responsibility for deciding whether the Bill should be enacted now rests with Parliament.
In a statement issued after the Supreme Court’s determination on the 22nd Amendment Bill, BASL President Rajeev Amarasuriya and General Secretary Nalin de Silva have said the SC’s determination should not be interpreted as an endorsement of the proposed constitutional amendment as a matter of policy.
The BASL has said the SC’s jurisdiction, under Articles 120, 121 and 123 of the Constitution, was to determine the constitutional requirements for the enactment of the Bill, including whether the Bill, or any of its provisions, required approval at a referendum under Article 83.
“The determination is therefore not a determination as to whether the proposed amendment is good or bad policy, desirable or undesirable, wise or unwise, or whether Parliament ought to enact it,” the BASL said.
Full text of the BASL statement: The Supreme Court has now delivered its Determination on the Twenty-Second Amendment to the Constitution Bill and determined that the Bill does not require the approval of the People at a Referendum.
In terms of Articles 120, 121 and 123 of the Constitution, the jurisdiction of the Supreme Court in relation to the Bill is to determine the constitutional requirements for its enactment, including importantly whether the Bill, or any provision thereof, requires the approval of the People at a Referendum by virtue of Article 83.
The Determination is therefore not a determination as to whether the proposed Amendment is good or bad policy, desirable or undesirable, wise or unwise, or whether Parliament ought to enact it.
This distinction is also evident from Sri Lanka’s previous constitutional amendments. During the 48 year history of the second republican Constitution there have been many amendments which passed constitutional muster but nevertheless had a negative effect on democracy, constitutionalism, the independence of the judiciary and the rule of law.
The question that now arises is whether Parliament ought to enact the proposed Amendment. That responsibility rests with Parliament and with each individual Member of Parliament when they vote on the Bill.
In making that decision, Members of Parliament should be mindful of the possible and probable consequences the 22nd Amendment will have on our nation. They should also consider the lack of transparency and a proper consultative process in the introduction of the 22nd Amendment. As representatives of the people they should also consider the concerns that have been expressed in relation to the proposed Amendment by a broad cross-section of society including the Maha Nayakes of the Three Nikayas, the Catholic Bishops’ Conference in Sri Lanka, the Church of Ceylon, the Bar Association of Sri Lanka, the Judicial Service Association, the Commonwealth Lawyers Association, LAWASIA, the International Association of Judges, the United Nations Special Rapporteur on the Independence of Judges and Lawyers, the French National Bar Council, and more than 40 Professional Associations and Unions, including the Government Medical Officers’ Association and other leading professional bodies.
Accordingly, the Bar Association of Sri Lanka calls upon all the political parties in Parliament to allow the Members of Parliament to speak and vote on the 22nd Amendment according to their conscience.
The responsibility now lies with Members of Parliament, when called upon to vote, to take a principled position according to their conscience giving due consideration to their constitutional responsibility, their representative capacity and most importantly their duty to the sovereign People of Sri Lanka.

SL to regain access to international financial and capital markets next year in line with IMF projections
Sri Lanka is on course to regain access to international financial and capital markets around 2027, in line with the International Monetary Fund’s (IMF) current economic projections, IMF Mission Chief Evan Papageorgiou said yesterday.
Papageorgiou said the IMF’s core assumptions under Sri Lanka’s economic programme continued to envisage the country returning to international capital markets in 2027.
“Our previous assumption that Sri Lanka will go back to capital markets still stands. We still have a good trajectory to achieving this in 2027 or thereabouts, and that should be the goal,” he said.
Papageorgiou stressed that Sri Lanka could not rely solely on domestic sources of financing to build long-term economic resilience and would need a diversified funding strategy.
“Every country needs to have a good ability to access funds both in domestic markets, as it already has, as well as international markets for eurobonds and other modes,” he said.
He said a return to international capital markets would have significant implications for Sri Lanka’s external debt composition, while strengthening foreign exchange reserves would remain essential as the country prepares to meet future debt-servicing obligations.
The IMF’s assessment comes amid improving international investor sentiment towards Sri Lanka and positive developments in the country’s sovereign credit ratings.
Papageorgiou cited Fitch’s recent upgrade of Sri Lanka’s credit rating as a positive development, saying global investors were increasingly viewing the country from a more constructive perspective.
Sri Lanka remains under the IMF’s Extended Fund Facility (EFF) programme, which is scheduled to continue until March 20, 2027. Regaining access to international capital markets remains a key milestone under the country’s broader economic recovery.
The IMF has stressed the importance of rebuilding Sri Lanka’s foreign exchange buffers and maintaining stability in domestic financial markets as the country approaches substantial external debt repayments.
A sustained improvement in these areas would help strengthen the country’s capacity to return to international markets while safeguarding macroeconomic stability, the IMF has indicated.
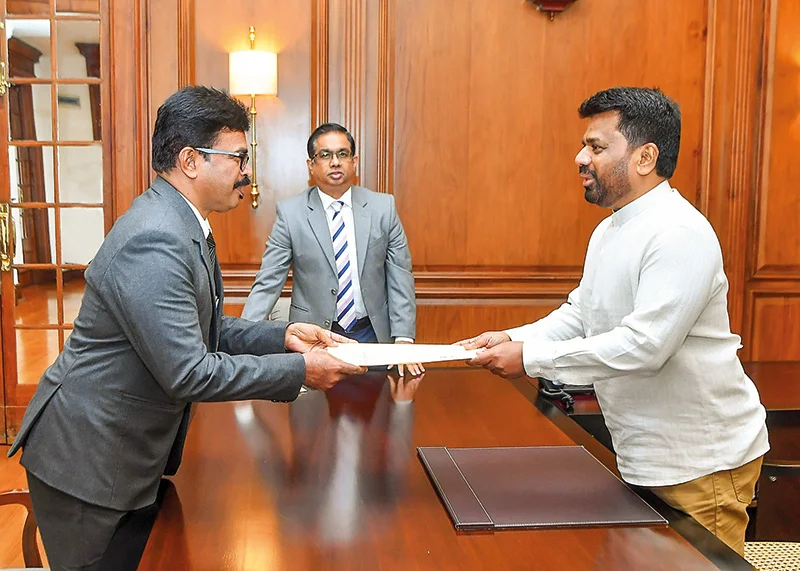
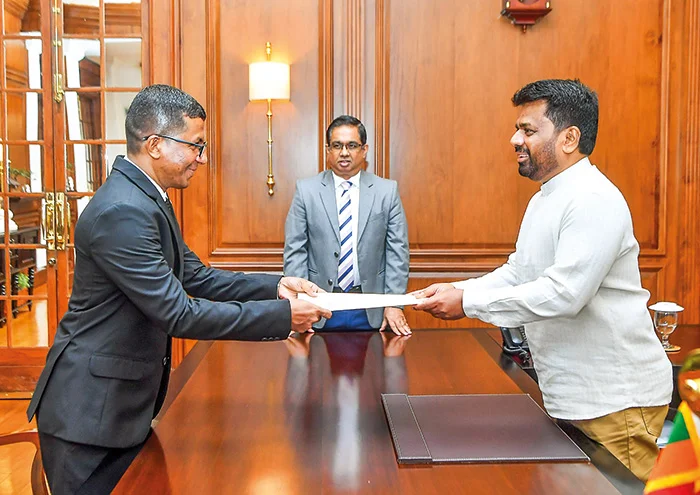
President Anura Kumara Dissanayake yesterday (23) handed over appointment letters to three Special Grade officers of the Judicial Service as High Court Judges, at a ceremony held at the Presidential Secretariat, according to the President’s Media Division (PMD).
The new appointees are Perumal Sivakumar, District Judge of Jaffna; Anandi Kanagaratnam, Senior Assistant Secretary of the Judicial Service Commission; and Gnanesha Lalith Kannangara, District Judge of Colombo.
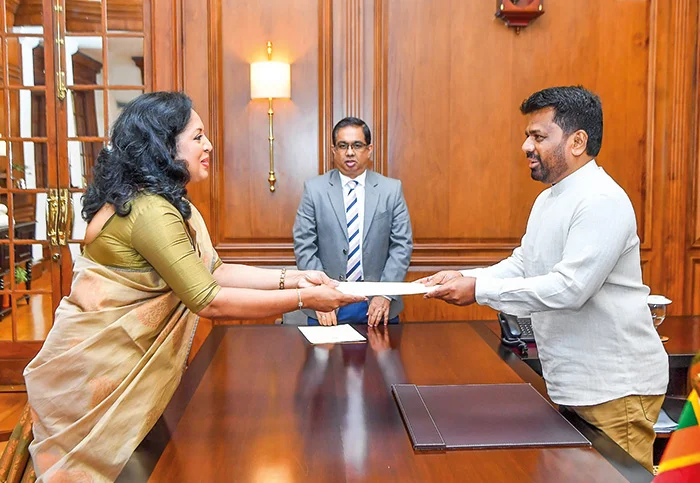
The three senior Judicial Service officers will take up duties as High Court Judges following their appointments.
The appointments were made from among Special Grade officers of the Judicial Service, the PMD said.

Showerss above 100 mm are likely at some places in the Western, Sabaragamuwa, Central and North-western provinces and in Galle and Matara Districts

Mirabai Chanu wins Asian Games silver as Ri breaks weightlifting record

Trump greets China’s Xi Jinping on arrival for three-day US

BASL calls for conscience vote on 22nd Amendment

IMF: Sri Lanka on course for 2027 market return

President appoints three new judges to High Court

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 News5 days ago
Shanakiyan urges urgent action over reported death sentence for Lankan in Saudi Arabia
-

 News6 days ago
Bid for Basil’s extradition nears final stage: Police
-
 News4 days ago
Namal Rajapaksa Buddhist gambit fails, bail denied
-
 Features4 days ago
Why the spelling Sri Lankan names in English vary
-
 Features4 days ago
Three bands, a new identity: Sri Lankan wolf snake recognised as distinct species
-
 Business4 days ago
SLIIT holds largest-ever convocation
-
 News4 days ago
Govt monitors reported Saudi death sentence – Foreign Ministry
-
 Business4 days ago
All-new Bolero MaXX Pik-Up unveiled in Lanka