Business
Cabraal and Central Bank responds to debt default fears

Recent commentary on Sri Lanka’s credit outlook ignores the numerous policy initiatives of the Government of Sri Lanka, which have already started yielding results
The Government of Sri Lanka observes that the concerns expressed in the media in reference to recent reports on Sri Lanka’s ability to service its debt obligations by international banks are one sided, and do not take into consideration the numerous of policy measures that have been introduced to revive the economy and ensure macroeconomic stability. These innovative policy measures are not restricted to traditional debt-based solutions to service the current debt obligations. Measures to build resources through non-debt solutions, the preservation of foreign currency resources and the gradual phasing down of the relative share of foreign debt are already yielding desired results, with a high likelihood of harnessing further improvements during the remainder of the year and beyond.
Certain media reports published recently attempts to raise concerns about Sri Lanka’s ability to honour its debt service obligations, based on backward looking and linear assumptions, thus ignoring the expected outcome of the novel policy regime currently in place. While gross official reserves have moderated somewhat since end December 2020, such moderation is not expected to continue. When all relevant facts are considered, it becomes apparent that the fears raised in certain reports are, in fact, merely hypothetical. The Sri Lankan economy, which is over US dollars 80 billion, has major natural and regular sources of foreign exchange inflows, including merchandise and services exports, workers’ remittances, programme and project related inflows, equity investment, and other financial flows. Aided by the post-COVID revival of the economy, such foreign exchange inflows are projected at US dollars 32 billion in 2021, even without major forms of borrowings, such as floating International Sovereign Bonds (ISBs). These projected inflows are expected to increase by about US dollars 2-3 billion annually in the period ahead with the support of well targeted policies and strategies of the Government. At the same time, authorities will continue to take measures to build up official reserves with the help of measures already implemented and further measures as necessary in the period ahead. It is noteworthy that the Government has launched a major drive towards promoting real inflows of foreign exchange through actively facilitating various merchandise and services exports, in both traditional and non-traditional sectors. The import curtailment measures and the steady recovery in export earnings would continue to improve liquidity in the domestic foreign exchange market. Further, envisaged equity investment flows through the Colombo Port City and Industrial Zones and the reprioritisation of project financing would help reduce the share of foreign debt notably in the period ahead, thereby dispelling concerns about debt sustainability.
In this context, settling the maturing ISBs of US dollars 1.0-1.5 billion, per year, over the medium term, need not be viewed as a major source of concern, given the entire stock of outstanding ISBs account for only 16.7 per cent of Sri Lanka’s total government debt as of end February 2021. It is also stressed that lenders in the majority of 83.3 per cent of the debt stock have raised no concern whatsoever about Sri Lanka’s ability to honour debt obligations. The authorities remain committed to honoring all upcoming debt obligations, leaving zero probability of any form of default on any obligation, which would jeopardise the longstanding relations with stakeholders and the impeccable credit history of the country.
The engagement with the International Monetary Fund (IMF) continues at staff level and as a member state in technical exchanges of know-how. Exploration of liquidity facilitation arrangements with regional central banks is also continuing, with some discussions are at an advanced stage.
As indicated in the Budget 2021, the Government has adopted a novel approach in relation to foreign financing, while enhancing the effectiveness of already secured financing channels, aimed at reducing the share of foreign financing of the budget deficit over the medium term. Reflecting the impact of measures already put in place by the Government, the relative share of outstanding external debt has already declined notably. The Government aims to reduce its external debt over the medium term to around a third of the total debt, and already the share of external debt has declined to around 40 per cent by end 2020 from over 48 per cent at end 2019.
The measures introduced to manage non-essential imports helped ease trade deficit to USD 5,978 million in 2020 from USD 7,997 million in 2019. The trade deficit is further expected to shrink in 2021 to around USD 4 billion. Export facilitation is expected to continue through allowing intermediate goods imports unhindered and promoting domestic value chain improvements, which would result in export earnings of about USD 13 billion in 2021.
Additionally, despite the projections of downturn in workers’ remittances, Sri Lanka recorded an increase of over USD 400 million remittances in 2020 with an aggregate of USD 7.1 billion. The policy measures to further incentivise remittances flows were facilitated with the Budget 2021 announcement of an additional Rs. 2 for conversion of per USD remittance, and the banks were required to sell 10 per cent of such remittance conversion to the Central Bank. The Central Bank has already commenced such absorption of conversions into its foreign exchange reserve. Further arrangements to improve foreign currency liquidity have been introduced, including a mandatory conversion of ¼ of export proceeds.
The Government is also in the process of channeling in official credit sources, with priority being envisaged for policy loans with a significantly high liquidity component. In addition, the commercial external financing component of the already lined-up term financing facility and other market financing components are envisaged in line with Budget 2021.
Sri Lanka Development Bonds (SLDBs) and loans of Overseas Banking Units (OBUs) also remain sources of foreign currency financing mainly from domestic foreign currency earning entities. The recently introduced measures to entice foreign investors to the government securities market and the real economy through an attractive foreign exchange swap arrangement are also likely to help enhance foreign currency inflows in the near term.
Real investment flows to the country remain a promising source based on the Colombo Port City related developments. The land reclamation work had been completed and the required legislation is being finalised. In December 2020, the Sri Lankan conglomerate, LOLC Group, signed an agreement with the Port City developers for a Mixed Development Project valued at USD 1 billion, which is set to break ground in mid-2021.
In this context, the Government reiterates its utmost commitment on meeting its external debt obligations, which will be facilitated not only through direct and indirect financing arrangements but also through highlighted policy measures and the current work plan to increase non-debt creating forex inflows.
The Government wishes to reiterate that even in the midst of various concerns raised by many parties on Sri Lanka’s debt service capability at the height of the COVID-19 pandemic, the Government was able to service its total external debt of around USD 4.3 billion in 2020.
The recent research reports indicate different figures of external debt obligations for 2021. The external debt obligations of the Government for 2021 amount to around USD 3.7 billion including the amortisation payments of USD 2.5 billion. Of this amount, thus far in 2021, the Government has settled over USD 500 million.
Sri Lanka will engage freely with all its investment and development partners and implement the envisaged measures to build up reserves through non-debt creating inflows while reviewing closely the international capital market developments.
Investors are invited to approach the Sri Lankan policy authorities at the highest levels who always remain open for constructive dialogue and will welcome any one-on-one engagement or roadshow discussions, without being dissuaded by premature one-sided opinion expressed without factoring the ground realities and the actual outcomes of policy measures introduced by the Government of Sri Lanka.
Business
Cost-effective clearance of goods across borders to determine worth of Customs Paperless Declaration

By Ifham Nizam
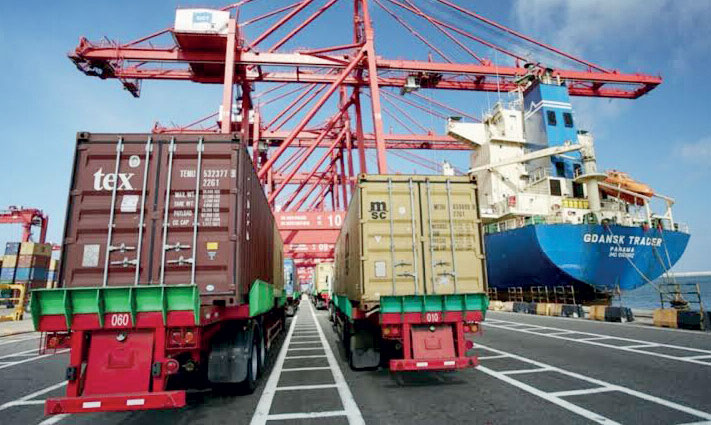
The introduction of the Customs Paperless Declaration from October 1 could mark an important step in Sri Lanka’s efforts to modernise trade, but its real value will depend on whether it reduces the time and cost of moving goods through the country’s borders, Customs House Agents & Traders Association President Mohamed Niyas said.
Niyas warned that digitising Customs declarations alone would not necessarily translate into faster cargo clearance or lower costs for businesses.
‘Expecting a dramatic improvement in clearance speed under the present conditions is like expecting Ferrari performance from a Morris Minor configuration, he said.
For importers and exporters, the issue extends well beyond paperwork. Every additional hour or day that cargo remains in the clearance chain can have wider consequences for businesses, including increased port and storage-related costs, additional working-capital requirements, uncertainty over delivery schedules and disruptions to production and distribution.
Niyas said the competitiveness of Sri Lanka’s trading sector ultimately depended on how efficiently goods could move through the country’s border-clearance system.
‘The real bottleneck is not merely the absence of paper. It is the entire clearance ecosystem—the limitations of the existing ASYCUDA World system, excessive regulatory interventions by Other
Government Agencies, multiple approvals, physical examinations, manual interventions, fragmented processes and institutional constraints, he said.
He cautioned that unless these bottlenecks were addressed, there was a risk that the paperless initiative would merely digitise existing bureaucracy.
‘If these underlying constraints remain unchanged, there is a real risk that the new paperless system could become another “copy-and-paste road show”—where an old, complex clearance process is simply transferred onto a digital screen without fundamentally changing the process itself, Niyas said.
For businesses dependent on imported raw materials, machinery, components and other inputs, clearance efficiency can directly affect the wider supply chain.
Delays at the border can create uncertainty for manufacturers, distributors and retailers, while exporters can face difficulties meeting delivery schedules when imported inputs or export consignments are held up.
Niyas therefore argued that the success of the October 1 initiative should be judged by its impact on trade flows rather than by the number of declarations processed electronically.
‘Paperless does not automatically mean faster, he said. ‘Digitising a slow process does not make the process fast. It only makes the slow process digital.’
He said Sri Lanka needed to move towards what he described as “process-less Customs”—a system in which unnecessary procedures are eliminated rather than simply converted into electronic procedures.
Among the reforms he called for are simplification of Customs declarations and approval workflows, improvements to the functionality of ASYCUDA World, greater use of risk-based inspections and better integration of Other Government Agency approvals.
Niyas also called for the elimination of repetitive document submissions and physical endorsements, greater use of pre-arrival processing, sufficient capacity for digital document uploads and clearly defined service-level timelines for Customs and OGAs.
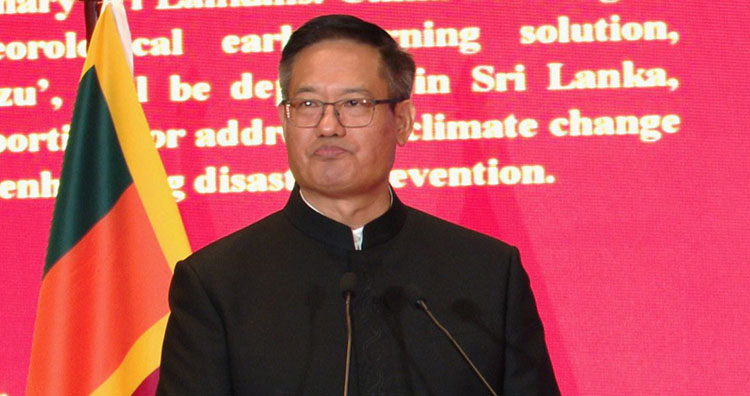
By Sanath Nanayakkare
As global attention has fixed on the high-level diplomatic choreography at the United Nations General Assembly in New York, a subtler, yet profound geopolitical signal was sent from Colombo, yesterday.
In a major address marking the founding anniversary of the People’s Republic of China, newly appointed Chinese Ambassador Wei Huaxiang chose to anchor bilateral relations not just in modern trade or infrastructure, but in a shared respect for Sri Lanka’s legacy of non-aligned independence.
By explicitly invoking Sri Lanka’s foundational role in the 1976 Non-Aligned Summit, Beijing was doing something unexpected in an era defined by fierce great-power rivalry: it was officially validating a small island nation’s right to maintain an independent foreign policy stance.
The Strategic Value of Independence
For decades, nations caught in the crosshairs of major-power competition have faced intense pressure to pick sides. Yet, Ambassador Wei’s embrace of Colombo’s non-aligned tradition signaled a different diplomatic playbook. Instead of demanding alignment, Beijing was framing its partnership as a reliable counterbalance to regional pressures. By honouring Sri Lanka’s diplomatic autonomy, China was effectively reassuring smaller economies that sovereign independence and robust economic cooperation can coexist.
Beyond Ports and Industrial Zones
This diplomatic framing reframed the narrative surrounding major collaborative ventures like the Colombo Port City and Hambantota Port. While foreign analysts often view these projects exclusively through the lens of strategic rivalry, Beijing’s diplomatic messaging tied them back to a historical ethos of solidarity—evoking memories of the 1952 Rubber-Rice Pact.
By marrying economic projects with a stated respect for non-alignment, China is positioning itself as a steadfast stakeholder that respects Sri Lanka’s internal agency during difficult economic and political seasons.
As both nations look toward major milestones in 2027—including the 70th anniversary of diplomatic ties—this nuanced diplomatic move revealed how historic traditions are being leveraged to navigate modern multipolar realities.
For global observers, the takeaway was clear: in the shifting architecture of Asian geopolitics, respecting a nation’s historical neutrality may just be the most effective way to secure a lasting partnership, a diplomatic masterclass that Ambassador Wei Huaxiang executed in style.
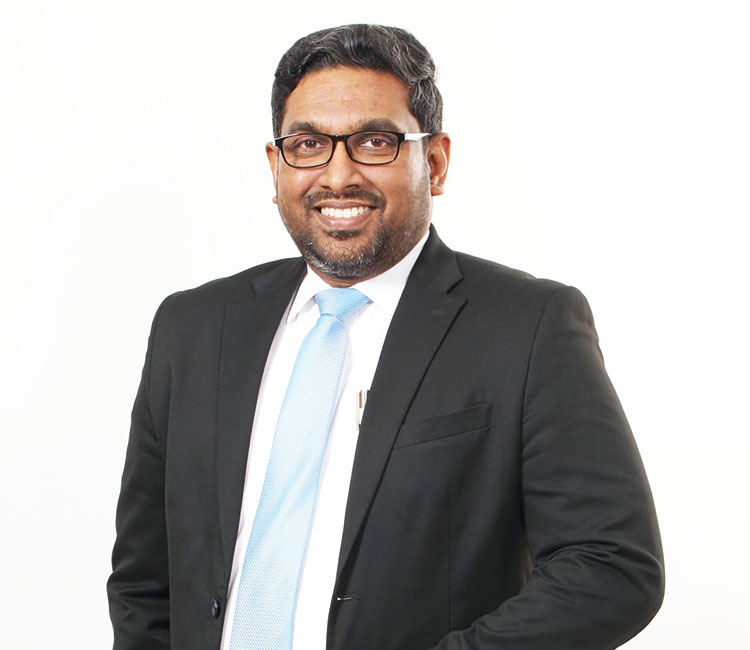
Sri Lanka Insurance Life (SLIC Life), the nation’s largest and strongest Life Insurer, is pleased to announce the appointment of Dr. Sameera Dharmasena as its new Chief Executive Officer, effective 22nd September 2026.
Dr. Dharmasena is a distinguished insurance professional with over 21 years of experience in the Sri Lankan insurance industry, having held senior leadership positions across several leading insurance companies affiliated with some of Sri Lanka’s largest business conglomerates. His extensive career spans both local and multinational insurance environments, bringing together broad industry expertise, strategic leadership and a strong commitment to the advancement of the insurance profession.

‘Vision’ Programme Marks Two Years

Costa Rica minister fired for unapproved meeting with Trump in US

At least 41 die as boat capsizes in DRC’s Lake Tanganyika

Showers will occur at times in the Western, Sabaragamuwa, Southern, Central and North-western provinces

Sajith vows to scrap 22A under future govt.

Two retired female Navy officers remanded over disappearance of two women during war

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 News6 days ago
Shanakiyan urges urgent action over reported death sentence for Lankan in Saudi Arabia
-
 News5 days ago
Namal Rajapaksa Buddhist gambit fails, bail denied
-
 Features5 days ago
Why the spelling Sri Lankan names in English vary
-
 Features5 days ago
Three bands, a new identity: Sri Lankan wolf snake recognised as distinct species
-
 Business5 days ago
SLIIT holds largest-ever convocation
-
 News5 days ago
Vehicle prices drop by up to Rs. 1 mn, says importers’ body
-
 News5 days ago
Govt monitors reported Saudi death sentence – Foreign Ministry
-
 Business5 days ago
All-new Bolero MaXX Pik-Up unveiled in Lanka