Business
Currency Board: A solution to Sri Lanka’s economic crisis?


By Dr Asanka Wijesinghe
On 08 March, Sri Lanka devalued the rupee against the US dollar, entering into a floating exchange rate regime. The Central Bank of Sri Lanka had to abandon the pegged exchange rate as defending the rupee with dwindling reserves was impossible. The inter-bank exchange rate shot up once the banks were assured that the exchange rate was floated. The initial shoot-up was followed by further rallying of the US dollar reaching close to Rs. 300 per USD. With the gradually weakening rupee, inflation is also ascending to worrisome levels calling for radical changes, including adopting a currency board. This article discusses the effectiveness and suitability of a currency board for Sri Lanka in the current macroeconomic context.
Weakening Rupee, Rising inflation, and the
Currency Board Solution
A currency board is a system that issues domestic banknotes in exchange for specific foreign currency – anchor currency like the USD which is used for trade with partner countries – at a constant rate. A cornerstone of the currency board mechanism is the authority’s ability to meet all demand for foreign currency by the holders of the domestic currency.
In Sri Lanka, even after the rupee was floated, reports suggest that an active kerb market with a significant premium above the inter-bank rate exists. While such market behaviour indicates an acute dollar shortage in the market and the equilibrium rate is further away, no official data exists on the kerb market money exchange. However, cryptocurrency platforms provide some critical insights. The Tether coin (USDT), which is closely pegged to the US dollar on a one-to-one basis, is traded for rupees on peer-to-peer (P2P) platforms as USDT is used as a medium to purchase other cryptocurrencies, including Bitcoin.
Data extracted from the P2P platform medium of Binance – a popular cryptocurrency exchange among Sri Lankans – show some supporting evidence for the continually widening gap between official and informal rates again. Significantly, the premium over the official rate plummeted once the rupee was floated, but it gradually recovered to the pre-floated period (A and B panels of Figure 1). The number of sellers and the USDT volume available for sale also went up but riveted back to the levels of the pre-floated period (C and D panels of Figure 1).
The inflationary pressure also does not show any unwinding signs, further eroding people’s purchasing power. These developments encourage the adoption of a currency board as a currency board is believed to be a solution for rising inflation. By the inner mechanics of the currency boards, the independence of discretionary monetary policy is taken away, substituting a disciplined monetary policy – a gold standard without gold – which eliminates the inflationary bias. Indeed, empirical evidence exists in favour of the anti-inflationary effect of currency boards. The inflation rate is lower under currency boards than in pegged or floating rate regimes. Moreover, economies under currency boards grew faster than the average of countries with pegged regimes. However, empirically disentangling multiple influences to pinpoint the low inflation on the currency board is an excruciating task.
Another selling point of the currency board is the fiscal discipline, as currency board regulations prohibit direct monetary financing of government expenditures. A high budget deficit in Sri Lanka and excessive government borrowings from the Central Bank make the fiscal-discipline effect of currency boards much more appealing. Empirical evidence points to low fiscal deficits or larger surpluses under currency board regimes.
Source: Author’s illustration using Binance data
Challenges in Adopting a Currency Board
A significant drawback of a currency board is the need to surrender the monetary policy independence required for managing asymmetric shocks. Such loss is costly when the anchor currency country responds to cyclical conditions, which are different from the prevailing conditions in the country operating the currency board. For example, Hong Kong’s currency board imported low-interest rates from the US in the early 1990s. Such monetary easing was appropriate for the US, but Hong Kong faced an asset price boom that called for monetary tightening. A counterargument against the negative impact of losing monetary policy is the availability of fiscal policy at the operating country’s disposal. However, the maneuverability of fiscal policy is determined by the fiscal and debt positions. In Sri Lanka’s context, the high debt to GDP ratio and fiscal deficits might restrict the use of fiscal policy for pump-priming-stimulating the economy in a recessionary period- due to the fear of losing investor confidence in debt sustainability. Thus, international evidence shows that countries with hard pegged exchange rate regimes generally tighten their fiscal policy in a recession. The Argentinian attempts to bring down the deficit in a recession in 2000 proved to be disastrous.
Sri Lanka’s high indebtedness will also challenge installing a currency board. Once a threat of a possible default looms, the interest rates soar, and refinancing debt will be increasingly difficult. In addition, the operating country needs reserves to back the monetary base in a currency board. In a currency board, the board must continually convert domestic currency for the anchor currency at a constant rate. It should be noted that the reserve level of Sri Lanka has dwindled over time in the recent past. Another drawback of currency boards is the requirement of real sector changes to compensate for the exchange rate deviations. For example, if the anchor currency appreciates against Sri Lanka’s main trading partners, wages should fall to compensate for the increase in foreign consumer prices, restoring competitiveness. Such an exercise needs greater flexibility in the labour markets. Thus, the flexibility of labour markets is a key to the sustainability of currency boards. The political feasibility of the institutional attempts to ease labour market regulations is highly doubtful.
Against this backdrop, the decision to install a currency board should be taken after a careful cost-benefit analysis. A currency board will be helpful to stabilise inflation in the short run but in the long run, Sri Lanka will be better off with a more flexible exchange rate regime. In addition, the benefits of a currency board are not exclusive. For example, fiscal discipline should be stronger in flexible exchange rate regimes as fiscal policy effects are reflected immediately and more transparently. Thus, if Sri Lanka enters into a currency board to stabilise inflation and domestic currency, it needs to contemplate an exit strategy. Generally, it is advisable to leave a currency board when the economy recovers. The requirement to surrender monetary independence and the inability to finance government expenditure under a currency board might reduce the political preference for such a system.

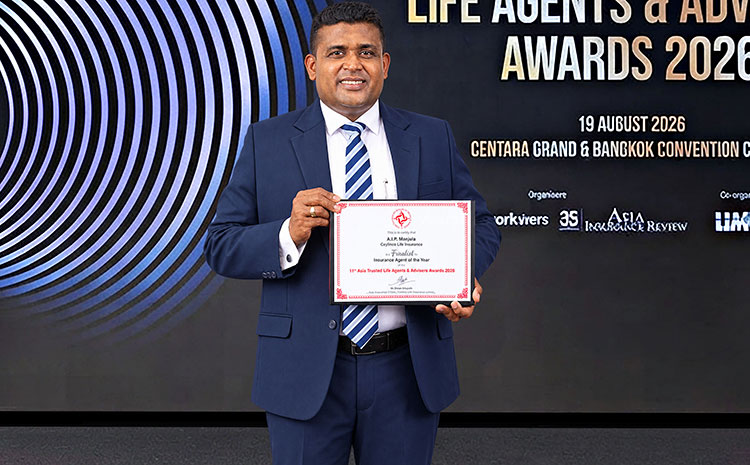
Ceylinco Life’s Ambalantota branch agent AIP Manjula has been named one of three global finalists for the prestigious Insurance Agent of the Year award at the 11th Asia Trusted Life Agents & Advisers Awards (ATLAA) 2026.
The recognition places a Sri Lankan insurance professional among the finalists in a regional field spanning South Asia, Southeast Asia, East Asia and the wider Asia-Pacific region.
Ceylinco Life said the achievement reflected the calibre and customer-focused approach of its agency force, while recognising Manjula’s professionalism and commitment to policyholders.
The award evaluates insurance agents on criteria extending beyond sales performance, including ethical conduct, client service, policy persistency, digital adoption, innovative practices and contributions to the insurance industry and community.
The awards are organised by Asia Advisers Network and Asia Insurance Review, with LIMRA as co-organiser. An independent judging and balloting process is monitored by KPMG as the official scrutineer. The judging panel comprises senior insurance executives, association presidents and industry experts from across the Asia-Pacific region.
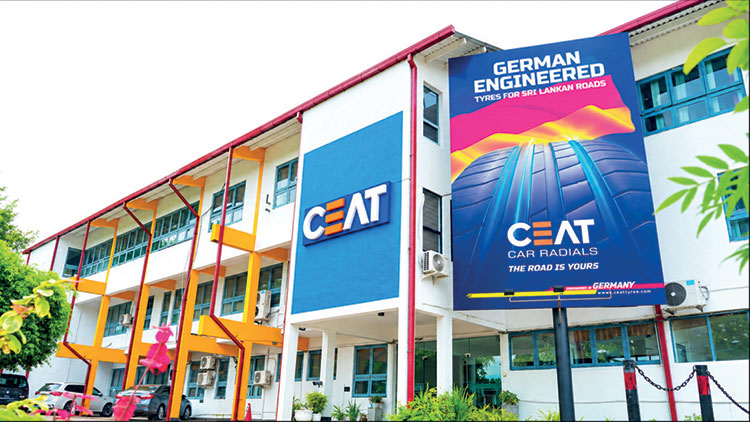
CEAT Kelani Holdings (CKH) has retained its National Long-Term Rating of ‘AA+(lka)’ with a Stable Outlook from Fitch Ratings for the sixth consecutive year, reflecting the company’s financial resilience and leading position in Sri Lanka’s pneumatic tyre market.
The ‘AA+(lka)’ rating, the second-highest on Fitch’s national scale, indicates a very strong capacity to meet financial commitments.
Fitch said CKH’s established market leadership and resilient financial profile remained key strengths, while noting its exposure to price-sensitive, cyclical and highly competitive markets.
The Stable Outlook reflects expectations that the company will maintain its market position despite rising input costs and increasing competition from imported tyres, while preserving adequate credit metrics during periods of weaker earnings and higher investment.
Fitch expects CKH’s established brand, extensive dealer network and adaptive pricing strategies to support its market position. Planned production facility upgrades are also expected to improve product quality, particularly in the radial tyre segment.
The rating agency expects near-term pressure on margins from higher raw material and energy costs but said the company’s low leverage and sound liquidity would provide a cushion.
CKH Chairman Chanaka De Silva said the rating reinforced the company’s focus on disciplined financial management, operational adaptability and long-term investment.
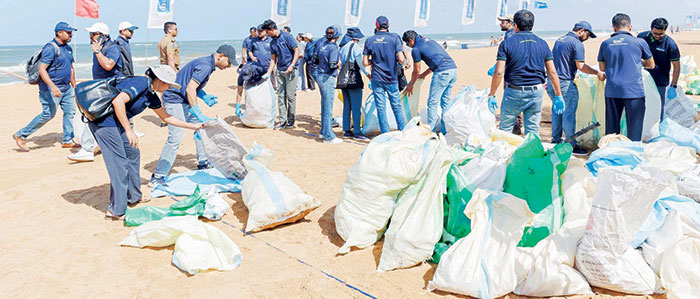
Commercial Bank of Ceylon mobilised employees, customers, volunteers and community members for a nationwide coastal and aquatic clean-up campaign across 20 locations on September 19 to mark International Coastal Cleanup Day 2026.
Conducted under the bank’s sustainability platform, themed ‘Forward Together for a Cleaner Future’, the initiative covered 16 coastal locations and four inland waterways, bringing together stakeholders for a coordinated environmental conservation effort.
The flagship programme was held at Mount Lavinia Beach, with additional activities at Wellawatte and Galle Face beaches. Similar initiatives were conducted by the bank’s regional offices at locations including Kalutara, Negombo, Trincomalee, Batticaloa, Puttalam, Jaffna, Galle, Dondra, Tangalle and along the Mahaweli River.
Employees, management, Future Force volunteers, customers and their families participated alongside the Marine Environment Protection Authority (MEPA), United Nations Global Compact Network Sri Lanka, government and local authorities, environmental organisations and community members.
The bank said the initiative reflected its commitment to water stewardship after adopting Sustainable Development Goal 6 — Clean Water and Sanitation — as a priority goal in 2025.

Buttler out of Oval decider as Lawrence earns ODI call-up

Showers will occur in the Western, Eastern, Uva and Sabaragamuwa provinces and in Galle, Matara, Kandy and Nuwara-Eliya districts.

Nor’easter brings flooding as New York and New Jersey declare emergency 2 hours ago

Trump rejects Iran deal to reopen Strait of Hormuz in seven days

Govt plans to hire 121,000 state workers, redistribute tax revenue

Parliament clears 22A amid protests

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 News5 days ago
Mastermind Naufer Moulavi among 15 found guilty
-
 News7 days ago
Hatton youth protest against reported death sentence for Lankan in Saudi Arabia
-
 News7 days ago
Mahaweli rises as heavy rain triggers flood, landslide fears
-
 News6 days ago
Protest against setting up of cement factory in highly populated area near BIA
-
 Midweek Review5 days ago
Thileepan’s fast unto death: An authentic narrative that many missed
-
 Latest News4 days ago
Showers above 100 mm are likely at some places in the Western, Sabaragamuwa, Central and North-western provinces and in Galle and Matara Districts
-
 Editorial6 days ago
Trouble beginning in earnest
-
Editorial5 days ago
Big Bad Bills