Business
Special goods and services tax: Issues and concerns

By Dr Roshan Perera & Naqiya Shiraz
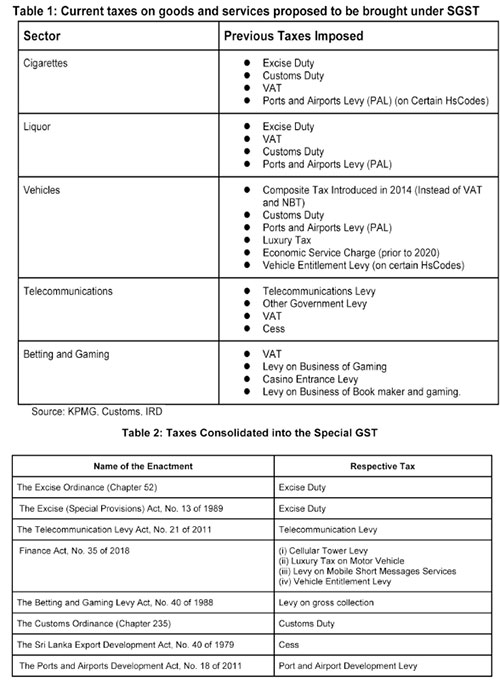
The new bill titled ‘Special Goods and Services Tax’ was published by gazette dated 07 January 2022.1 The Special Goods and Services Tax (SGST) was originally proposed in Budget speech 2021 but was not implemented. It has once again been presented in Budget 2022. The SGST aims to consolidate taxes on manufacturing and importing cigarettes, liquor, vehicles and assembly parts, while also consolidating taxes on telecommunication and betting and gaming (see table 1 for existing taxes on these products and table 2 for taxes consolidated into the SGST as per the schedule in the gazette). The rationale for this new tax as per the bill is “…to promote self-compliance in the payment of taxes in order to ensure greater efficiency in relation to the collection and administration on such taxes by avoiding the complexities associated with the application and administration of a multiple tax regime on specified goods and services.”
Given the multiplicity of taxes and the complexity of the current tax system as a whole, rationalising taxes is necessary to improve collection. However, whether the proposed SGST simplifies the tax system, while ensuring revenue neutrality or even improving revenue collection, needs to be carefully examined.
The SGST Bill is silent on the treatment of the existing VAT on these goods and services. However, according to the Value Added Tax (Amendment) Bill also gazetted on 07 January 2022,1 liquor, cigarettes and motor vehicles will be exempted from VAT while telecommunications and betting and gaming services will still be subject to VAT.
While the gazetted Bill sets out some of the features of the proposed SGST there are many important areas not covered in the Bill. These are expected to be gazetted as and when required by the Minister in charge.
Issues & Concerns
The motivation behind SGST is the simplification of the tax system. Although the objective of introducing the SGST is to improve efficiency by reducing the complexity of the tax system there are many issues and concerns with this proposed tax.
Revenue
Tax revenue which was 13% of GDP in 2010, declined to 8% in 2020. Ad hoc policy changes and weak administration contributed to the decline in tax revenue collection. This continuous decline in tax revenue has led to widening fiscal deficits and increasing debt. One of the main reasons for the current macroeconomic crisis is low tax revenue collection. Hence, any change to the existing tax system should be with the primary objective of raising more revenue.
According to the budget speech the SGST is estimated to bring in an additional Rs. 50 billion in revenue in 2022.1 Revenue from taxes proposed to be consolidated under the SGST has significantly declined over the past 3 years. Given the already difficult macroeconomic environment, along with ad hoc tax policy changes raising the additional revenue estimated at Rs. 50 billion seems a difficult task.
Tax Base and Rate
For the SGST to raise taxes in excess of what is already being collected through the existing taxes, the rate and the base for the SGST needs to be carefully and methodically calculated. Further, the existing taxes have different bases of taxation. For instance the basis of taxation of motor vehicles is both on an ad valorem1 basis and a quantity basis while the basis of taxation of cigarettes and liquor is quantity.2 In light of this, the basis of taxation on which SGST isapplied becomes an issue. Having different bases and different rates for various goods and services would complicate the implementation of the tax These issues need to be carefully considered to ensure the new tax is revenue neutral or be able to enhance revenue collection.
Efficiency
One possible revenue benefit of this proposal is the inability to claim input tax credits on the sectors exempted from VAT. However, the issue is the cascading effect that would result where there would be a tax on tax with the end consumer paying taxes on already paid taxes. If the idea was to raise additional revenue by limiting tax credits, it would have been simpler to raise the tax rates on the existing taxes rather than introduce a new tax.
4. Administration
According to the bill, SGST will now be collected through a new unit set up under the General Treasury where a Designated Officer (DO) will be in charge of the administration, collection and accountability of the tax. The existing revenue collection agencies, such as the Inland Revenue Department (IRD) or the Excise Department will not be primarily responsible for the collection of this tax. By removing the IRD and Excise Department, a parallel bureaucracy will be created, at a time when public spending needs to be carefully managed. The General Treasury also has no previous experience and expertise in direct revenue collection. Weak administration is one of the key reasons for the low tax collection and success of this tax would depend on the strength of its administration.
In addition to the above mentioned concerns, as per the Bill the minister in charge of the SGST has been vested with the power to set the rates, the base and grant exemptions. Accordingly, Parliamentary oversight over fiscal matters is weakened under this proposed Bill.
It could also lead to a time lag between the gazetting and implementing of changes to the SGST (such as the rate, base etc) and obtaining Parliamentary approval for those changes.
Dispute resolution
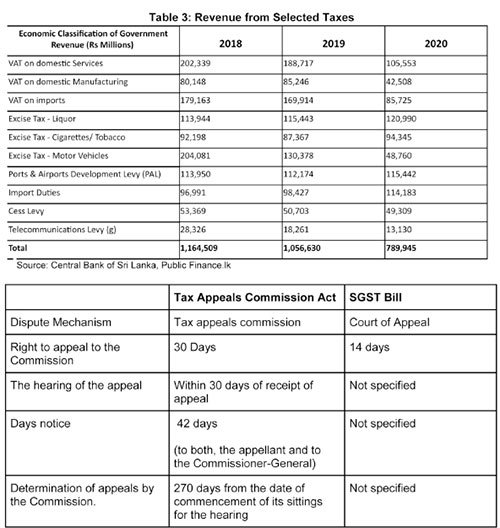
The SGST Bill also focuses on the dispute resolution mechanism. Under the present tax system, with the enactment of the Tax Appeals Commission Act, No. 23 in 2011 the Tax Appeals Commission has the “responsibility of hearing all appeals in respect of matters relating to imposition of any tax, levy or duty”.1 The most recent amendment to the Tax Appeal
Commissions act (2013)1 seeks to address the large number (495) of cases pending before the Tax Appeals Commision2 by increasing the number of panels to hear the appeals.
Under the proposed SGST disputes will be handled through the court of appeal. However, the time period by which specific actions need to be taken is not provided in the bill. In addition, disputes have to be taken to the court of appeal. Hence, the entire process will be more time consuming. This could result in revenue lags and difficulties in revenue estimation until disputes are resolved.
Additionally, in the case that no valid appeal has been lodged within 14 days, any remaining payments would be considered to be in default. Thereafter, the responsibility is shifted to the Commissioner General of the IRD to recover the dues. Given the IRD is completely removed from the normal collection process, the rationale for bringing defaults under the IRD is not clear.
III. Policy Recommendations
As discussed, the SGST Bill has several limitations and much of this is due to the ambiguities in the Bill.
If the tax is implemented, the rate and basis of taxation needs to be revenue neutral to ensure tax collection is maximised and administrative costs minimised.
The rates, basis of taxation, exemptions etc should be specified in the Bill, as done in most other Acts. This would avoid the power for discretionary changes to the tax being placed in the hands of the minister in charge.
Given the already weak tax administration, it would be more sensible to strengthen the existing revenue collecting agencies and address the weaknesses in the existing system without creating a parallel bureaucracy.
In the case where VAT is consolidated into the proposed GST, the issue of cascading effect of input tax credits needs to be addressed. This is relevant particularly in the case of capital expenditure.
Given the critical state of revenue collection in the country the question to ask is whether this is the best time to introduce a new tax. Focus should be on fixing issues in the existing tax system to ensure revenue is maximised. The VAT is the least distortionary tax and it is the easiest to administer. Given these features it can be a very efficient revenue generator for a country. Therefore instead of introducing a new tax, capitalising on systems that are already in place and amending the VAT rate, threshold and exemptions may be a more practical solution to the revenue problem that the country is currently facing.
Dr. Roshan Perera is a Senior Research Fellow at the Advocata Institute and the former Director of the Central Bank of Sri Lanka.
Naqiya Shiraz is a Research Analyst at the Advocata Institute.
The opinions expressed are the author’s own views. They may not necessarily reflect the views of the Advocata Institute, or anyone affiliated with the institute.

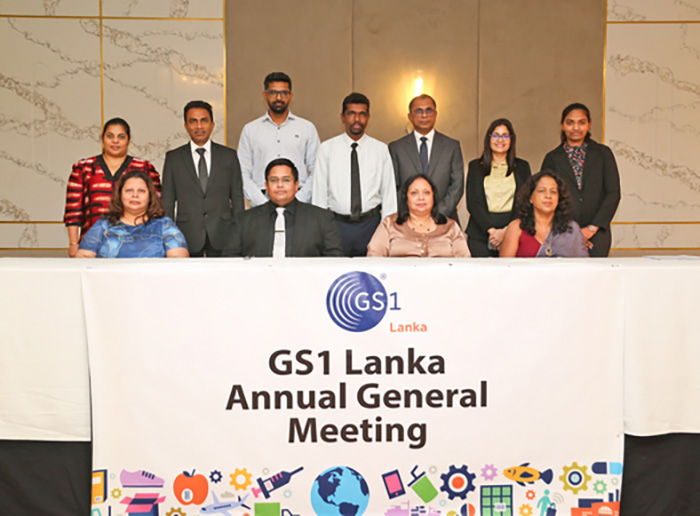
GS1 Lanka marked its 10th Annual General Meeting with a focus on the next stage of product identification in Sri Lanka, as businesses prepare for the wider adoption of 2D barcodes and the growing demand for trusted product information.
Addressing the AGM, GS1 Lanka president Revan Fernando noted that GS1 has been giving Sri Lankan products a globally recognised identity for more than 30 years. He pointed to the shift from traditional barcodes to 2D barcodes as the next major step, particularly as consumers increasingly look beyond a product’s identity to information they can trust about its origin, ingredients, authenticity and use.
GS1 Sunrise 2027 is a global industry initiative aiming to transition retail checkout systems to read 2D barcodes such as QR codes and Data Matrix codes alongside traditional 1D UPC stripes by the end of 2027
Under its Sunrise 2027 initiative, GS1 Lanka is working with the retail and healthcare sectors to prepare businesses for the transition to 2D barcodes. Unlike a conventional barcode used at checkout, a GS1 QR code can also connect consumers to a wider range of product information and support traceability and product verification through GS1 standards.
Fernando also called on brands to get involved in the transition, noting that the change will require businesses to rethink how they use the limited space on product packaging and how they communicate with consumers. GS1 Lanka will also introduce a new retail information platform to help member brands provide richer product information and improve the presentation of their products to consumers.
GS1 Lanka CEO Alikie Perera said the organisation’s work is increasingly focused on helping Sri Lankan businesses keep pace with changes in global supply chains and consumer expectations. The next phase will place greater emphasis on 2D barcodes, GS1 Digital Link, traceability and digital product information, as businesses prepare for a more connected and information-rich marketplace.
At the local level, GS1 Lanka continued its awareness programmes for entrepreneurs, SMEs, manufacturers and exporters, covering product identification, barcode standards, traceability, supply chain efficiency and market access. The organisation has also seen growing adoption of GS1 Activate and Verified by GS1, with more than 5,500 member companies registered on the platforms and over 20,000 product records uploaded.
The AGM concluded with a recognition of the contribution of GS1 Lanka’s members, partners, Board and team, while setting the direction for the organisation’s continued work to bring global standards and new product identification technologies into wider use among Sri Lankan businesses.
By Ifham Nizam
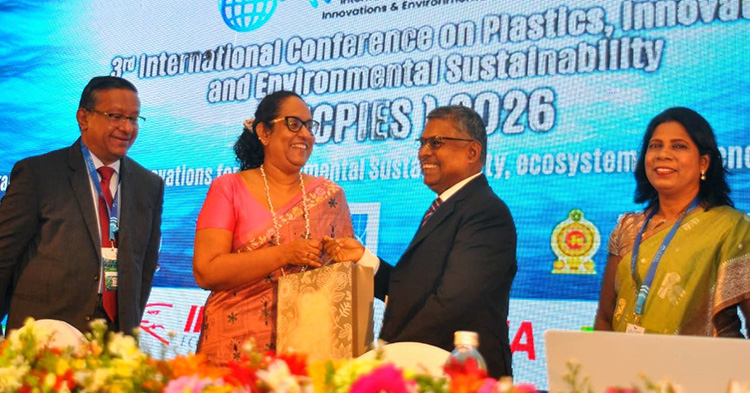
Sri Lanka’s plastic problem can no longer be treated simply as a waste-disposal issue, with the country facing mounting pressure on its coastal environment, fisheries, communities and public health, Vice Chancellor of The Open University of Sri Lanka Senior Professor P. M. C. Thilakerathne said.
The country must move beyond collecting and disposing of plastic waste and fundamentally rethink how plastics are designed, produced, consumed and recovered, Prof. Thilakerathne said, calling for a national shift towards a circular economy.
Addressing the 3rd International Conference on Plastics, Innovations and Environmental Sustainability, he said Sri Lanka’s experience, particularly the environmental fallout from the 2021 X-Press Pearl disaster, demonstrated why plastic pollution required urgent national attention.
The X-Press Pearl disaster resulted in large quantities of plastic pellets being released into Sri Lanka’s coastal waters, with impacts extending to marine biodiversity, fisheries and coastal livelihoods.
For an island nation whose economy and communities are closely connected to the sea, he said, plastic pollution could not be viewed as an environmental issue separate from national development.
” For Sri Lanka, these figures are not abstract,” Prof. Thilakerathne said, pointing to the global growth in plastic production and waste.
The world produces hundreds of millions of tonnes of plastics annually, while only a small proportion of plastic waste is recycled. A substantial amount ends up in landfills or is leaked, dumped or otherwise mismanaged.
The scale of the global problem has direct relevance to Sri Lanka, he said, because waste that is inadequately collected or managed can ultimately find its way into waterways and the ocean.
The Vice Chancellor said Sri Lanka therefore needed to strengthen not only waste collection and recycling but also the systems that determine what products enter the waste stream in the first place.
“Much of the waste problem is decided at the drawing board,” he said.
Products should be designed for reuse, recycling and disassembly, while businesses should be encouraged to adopt models based on refill, repair and reuse rather than continued dependence on single-use plastics.
He said Sri Lanka also had an opportunity to develop locally appropriate alternatives using renewable resources and agricultural residues.
The country’s coconut industry and other agricultural resources could support research into alternative materials, he said, but scientists must ensure that such substitutes were genuinely environmentally sustainable and did not simply shift the environmental burden elsewhere.
For Sri Lanka, the challenge is particularly important because plastic pollution intersects with several economic sectors.
Fishing communities depend directly on healthy marine ecosystems, while tourism depends heavily on the country’s beaches, coastal areas and natural environment.
Plastic pollution can therefore translate into economic and livelihood pressures in addition to its ecological consequences, Prof. Thilakerathne said.
He also warned that the problem extended beyond visible plastic waste.
Microplastics and nanoplastics have been detected in drinking water, food and air, while research into their potential effects on human health is continuing.
The longer-term public-health implications represented an important area for scientific research, he said.
Prof. Thilakerathne called for stronger cooperation between universities, government institutions, industry and local communities to develop solutions suited to Sri Lanka rather than relying solely on technologies or approaches developed elsewhere.
Universities, he said, had a responsibility to generate the evidence needed for national policy and to ensure that research reached the communities and industries expected to implement it.
This is where OUSL could make a particular contribution, given its nationwide network and large population of students, including working adults, teachers, professionals and learners from rural communities.
The university plans to strengthen environmental sustainability and circular-economy principles across its curriculum, expand professional education on waste management and sustainable materials, develop international research partnerships and improve sustainable practices within its own campuses and centres, he said.
Prof. Thilakerathne also called attention to the thousands of people who earn a living through informal waste collection and recycling.
Any national strategy, he said, must recognise the contribution of these workers and ensure that the transition towards a circular economy does not leave them economically vulnerable.
Sri Lanka has already introduced restrictions on a number of single-use plastic products, but the Vice Chancellor said regulations must be accompanied by enforcement, investment in recovery infrastructure, industry participation and changes in consumer behaviour.
At the international level, he said, Sri Lanka also needed to contribute actively to efforts to address plastic pollution, backed by credible national scientific research.
The global nature of the plastics trade and pollution meant that action by individual countries alone would not be sufficient.
The conference therefore provided an opportunity for Sri Lankan researchers to connect local environmental challenges with international research and technological developments, he said.
Addressing young researchers and students, Prof. Thilakerathne urged them to measure the value of their work not only by academic publications but also by its ability to produce practical change.
He encouraged researchers to work across disciplines, engage with policymakers and industry, and remain connected to communities affected by the problems they study.
“The most meaningful research is that which changes practice,” he said.
He said Sri Lanka’s plastic crisis ultimately required a change in the country’s approach to materials, consumption and waste.
“Our task is not to abandon the material that shaped the modern world but to make it compatible with the sustainable one,” Prof. Thilakerathne said.
Prepare for a theatrical experience that brings people together and celebrates life. The Peterite Arts Foundation, in proud association with World Vision Lanka, announces the showing of an amateur production arranged with Casarotto Ramsay & Associates Ltd. Every Brilliant Thing, the acclaimed solo play by Duncan Macmillan and Jonny Donahoe. Directed by Theruni Indrapala, the play’s lead is played by former Peterite Mario de Soyza. This uplifting, interactive production will run at Kamatha Studio, BMICH, Colombo, from 05 to 08 November 2026.
Every Brilliant Thing tells a deeply moving yet joyful story. At seven, the narrator begins listing everything worth living for, from ‘ice cream’ and ‘things with stripes’ to ‘rollercoasters’, hoping to help his mother through depression. Over time, the list grows to more than a million entries and becomes a lifelong source of comfort for the narrator.
What began as a short monologue in 2006 has grown into a global phenomenon, performed in more than 80 countries across five continents. Its hopeful message has reached audiences in extraordinary settings, including aboard the USS George H.W. Bush aircraft carrier. The play has also been translated into 44 languages, including Arabic and Greek, with a special Chinese adaptation titled Every Brilliant Little Thing.
The play’s need for emotional intelligence, openness and a strong connection with the audience attracted a distinguished line-up of performers. Following a successful West End run featuring Sue Perkins and Minnie Driver, the play made its Broadway debut at the Hudson Theatre, where it ran from 21 February to 9 August 2026. Tony Award winner Daniel Radcliffe opened the Broadway production, receiving critical acclaim and a Tony nomination for Best Lead Actor in a Play. Law & Order: SVU icon Mariska Hargitay then made her official Broadway debut in the role, followed by Golden Globe winner Tracee Ellis Ross, who closed the run.

Showers or thundershowers will occur at several places in the most part of the island after 1.00 p.m

Geneva takes up Sallay’s case and govt. ignores opportunity to answer accusations

Section of wartime KKS High Security Zone vacated to facilitate economic development in the area

Lawyer lodges complaint against Govt. Printer, Media Ministry Secy.

Sri Lankan troops in joint anti-terrorist exercise in Russia

Nine Indian poachers brought to KKS with their boat

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 Latest News5 days ago
Gold winner Tharanga gets brand-new Honda Vezel from SLAAJ
-
 Features5 days ago
Why Sri Lanka needs an Inclusive Civic Nationalism – urgently
-
 News4 days ago
US-assisted ‘Ice’ detection: NPC to examine IGP’s move to transfer drug-busting team
-
 Features6 days ago
Thailand’s biggest new global star …
-
 News6 days ago
First cases taken up by SC after enactment of 22A dismissed
-

 News5 days ago
Civil society activist accuses govt. of favouring Ven. Gnanasara
-
 Editorial3 days ago
Colombo Port drug bust: The plot thickens
-
 Editorial6 days ago
Aftershocks of 22A