Business
Central Bank of Sri Lanka releases Financial Stability Review for Year 2026


In terms of Section 70(1) of the Central Bank of Sri Lanka Act, No. 16 of 2023, the Central Bank of Sri Lanka released its annual Financial Stability Review (FSR) for 2026. This statutory report provides an assessment of the stability of the financial system, identifies and evaluates the associated risks and vulnerabilities, and outlines the policy measures implemented by the Central Bank and other regulatory authorities. The report generally covers data up to end June 2026. The electronic version of the publication can be accessed through the Central Bank website. (https://www.cbsl.gov.lk/en/publications/economic-and-financial-reports/financial-system-stability-review )
Summary of the FSR 2026 is given below:
Amidst multiple shocks, Sri Lanka’s financial system remained stable during the first half of 2026, supported by the continued economic recovery, sustained adequacy of capital and liquidity buffers across banks and finance companies (FCs), and improved fiscal performance. While domestic macrofinancial conditions remained stable, intensifying uncertainties in the global environment increased the risk of adverse spillovers to the domestic economy. Stability during the review period was supported by the continued recovery in economic activity, improved fiscal conditions and stronger financial sector performance. These developments provided an important cushion against heightened external uncertainties and supported the overall stability of the financial system. Nevertheless, the external environment remained challenging. Heightened geopolitical tensions, resurgent global inflationary pressures, elevated energy and commodity prices, tighter global financial conditions, growing trade fragmentation and increasing climate-related risks continued to pose potential spillovers to the domestic economy. Sri Lanka remained particularly exposed to adverse external developments, given its significant exposure through trade, tourism receipts, workers’ remittances, capital flows, external financing conditions and exchange rate dynamics. On the domestic front, credit growth, particularly in household lending including vehicle financing and gold-backed lending, continued to widen the private sector Credit Gap, signaling a potential build-up of systemic vulnerabilities. Moreover, although financial sector exposure to the public sector reduced, it remained significant, underscoring the considerable sovereign-financial sector nexus. Rising household indebtedness, volatility in collateral values with increased exposure to collateral-backed lending, the continued rise in real estate prices and inflationary pressures further highlighted emerging risks. In response to these developments, the Central Bank increased the overnight policy interest rate in May 2026 and introduced macroprudential measures, including loan-to-value (LTV) limits on vehicle and gold-backed lending, aimed at containing the build-up of vulnerabilities within the economy.
Domestic financial markets remained largely stable during the period, with the Financial Stress Index remaining at relatively low levels. Financial market conditions were shaped by heightened global uncertainty, domestic inflation concerns, and tighter monetary conditions. Equity market performance moderated amid subdued investor sentiment, while market liquidity weakened and volatility increased. Yields of Government securities increased across maturities during the review period with evolving market expectations and subsequently due to monetary policy tightening. Secondary market liquidity remained relatively subdued pointing to limited depth and trading activity in the domestic debt market. Meanwhile, foreign investor participation continued to be low despite a modest recovery towards the latter part of the reference period. The domestic foreign exchange market experienced periods of heightened pressure particularly with the escalation of tensions in the Middle East, reflecting increased demand for foreign currency arising from higher import expenditure, rising energy prices, and shifts in investor sentiment. These developments contributed to the depreciation of the Sri Lanka rupee against the US dollar. Market conditions subsequently improved, supported by policy measures and continued inflows from workers’ remittances, tourism, exports and intermittent fall in oil prices. Money market activity strengthened during the period, while overall liquidity remained in surplus and interest rates remained broadly aligned with the monetary policy stance. Payment and settlement systems continued to demonstrate operational resilience, supported by further digitalisation and improvements in settlement infrastructure. The continued expansion of digital financial services enhanced efficiency and financial inclusion, albeit increasing the financial system’s exposure to cyber, operational, and third-party risks. As digital connectivity deepens and technology evolves rapidly, ensuring adequate cyber resilience and operational preparedness remains critical to safeguarding financial stability.
Financial institutions continued to demonstrate overall resilience during the period under review, supported by the recovery in economic activity, stronger profitability and adequate capital and liquidity buffers. The banking sector credit expanded significantly amid robust private sector demand, with notable growth in consumption, trade, financial services, construction, and offshore-related lending. The decline in the Stage 3 loans ratio along with the improvement in the Stage 3 impairment coverage ratio depicted improved resilience of the banking sector. However, Stage 2 loans increased during Q2 of 2026, indicating a potential build-up of credit risk among borrowers amid elevated credit expansion. While liquidity ratios in the banking sector moderated during the review period, they remained well above regulatory thresholds. This decline primarily reflected a shift in asset allocation from high-quality liquid assets, particularly Government securities, to private sector lending. Meanwhile, short-term maturity mismatches widened, increasing potential refinancing and liquidity risks within the sector under unexpected stress conditions. Further, banking sector profitability continued to improve, although the pace of growth moderated somewhat from the levels recorded during the first half of 2025. Despite continued buildup of capital, driven by stronger profitability, the banking sector’s capital adequacy ratios declined as the growth of risk-weighted assets exceeded the pace of capital accumulation. Notwithstanding this moderation, capital buffers remained well above regulatory thresholds, providing adequate capacity to absorb potential shocks.
FCs sector witnessed a significant credit expansion driven by heightened demand for vehicle financing and gold-backed lending. Despite the improvement in the Stage 3 loans ratio, the sharp increase in Stage 2 loans indicated rising credit risks within the FCs sector. This was partly attributable to the adverse effects of Cyclone Ditwah and the Middle East conflict on affected borrowers and underscored the need for continuous monitoring of asset quality developments and the potential buildup of sectoral vulnerabilities. Moreover, the impairment coverage ratio declined, indicating a deterioration in loss absorption capacity within the sector. While liquidity buffers in the FCs sector remained adequate and well above regulatory thresholds, liquidity ratios declined amid strong credit expansion. Meanwhile, faster growth in borrowings compared to deposits highlighted the increasing interconnectedness between FCs and banks. Profits in the FCs sector continued to increase, supported by net interest income, although the rate of profit growth moderated during the first quarter of the financial year 2026/27. Capital buffers of the sector declined alongside the increase in risk-weighted assets driven by the expansion in credit. The insurance sector remained adequately capitalised, although profitability moderated. Significant claims arising from Cyclone Ditwah increased reinsurance receivables and heightened underwriting, liquidity, and counterparty risks.
Lending to both the Household and Institutional sectors increased during the first half of 2026. Although household credit growth remained elevated, a marginal moderation was observed towards the latter part of the period. The share of credit extended by Non-Bank Financial Institutions to the Household sector increased further during the first half of 2026, although the banking sector remained the primary source of formal financing for households. Moreover, risk profiles of Household borrowers, as reflected by overall credit scores, remained broadly stable during the first half of 2026. Credit to the Institutional sector also expanded at a rapid pace, with the banking sector accounting for the vast majority of lending to the sector. Meanwhile, the listed non-financial corporate (NFC) sector recorded stronger revenue growth during the first half of 2026, although aggregate profitability weakened. The decline in aggregate profits was largely attributable to higher costs of sales and operating expenses. Against this backdrop, creditworthiness of the listed NFC sector showed some signs of moderation, reflecting a slowdown in aggregate profitability and debt-servicing capacity.
In response to developments and emerging risks within the financial sector, a range of policy measures were implemented during the review period. Against the backdrop of rapid credit expansion in vehicle financing and gold-backed lending, borrower-based macroprudential measures were tightened to contain excessive leverage and mitigate emerging risks. These measures included simplification and tightening of maximum LTV limits on motor vehicle financing and the introduction of maximum LTV limits on gold-backed lending, aimed at promoting prudent lending practices and containing the buildup of systemic vulnerabilities. In addition to the LTV limits on gold-backed lending, applicable risk weights were also tightened during the review period. In response to the adverse effects of Cyclone Ditwah, the Central Bank issued circulars to both banks and FCs, requiring relief measures to be provided to affected individuals and businesses. The Directions on recovery planning for both banks and FCs were issued, alongside consolidation initiatives aimed at strengthening the resilience of the banking and FCs sectors. Amid the increasing prevalence of financial frauds and scams involving digital payment channels, the Central Bank introduced policy initiatives aimed at strengthening the security of digital payment methods and improving public awareness of related risks. Measures were also taken to strengthen the resolution framework, financial consumer protection, and Anti-Money Laundering, Countering the Financing of Terrorism and Countering Proliferation Financing (AML/CFT/CPF) framework, alongside preparations for Sri Lanka’s third Mutual Evaluation of its AML/CFT/CPF framework by the Asia Pacific Group on Money Laundering (APG) as well as initiatives aimed at improving financial inclusion.
Financial Stability Outlook
The outlook for financial stability remains broadly positive, provided that the ongoing economic recovery remains sustained, fiscal consolidation progresses, and prudent policy implementation continues. However, the outlook is contingent on external developments, including geopolitical and financial market uncertainties, as well as domestic vulnerabilities arising from any excessive expansion and sectoral concentration of credit, along with evolving cyber risks. Continued monitoring and timely policy intervention will therefore remain important in preserving financial stability. Prolonged geopolitical tensions and energy price shocks could weaken external balances and increase inflationary pressures, thereby impacting the repayment capacity of borrowers. These effects could amplify existing domestic vulnerabilities, including higher growth in collateral backed lending to households, rising Stage 2 exposures and declining liquidity and capital buffers. Financial market resilience will increasingly be shaped by the ability to strengthen investor confidence, improve market liquidity, deepen domestic capital markets, and attract a broader and more stable foreign investor base, thereby enhancing the market’s capacity to absorb shocks and support efficient price discovery. Overall, maintaining financial stability will require a well-calibrated combination of prudent monetary, macroprudential and regulatory policies, supported by sustained progress in structural reforms. Priorities of the financial sector should therefore focus on preserving strong capital and liquidity buffers across financial institutions, strengthening the management of climate-related and cyber risks, enhancing resolution and crisis-preparedness frameworks, and ensuring that credit expansion remains commensurate with underlying economic activity and risk conditions. These efforts will be essential in mitigating the buildup of systemic vulnerabilities, strengthening the financial system’s shock-absorbing capacity, and safeguarding financial stability over the medium term.

Govt. in ‘Consideration Mode’ over next IMF programme:
By Sanath Nanayakkare
President Anura Kumara Dissanayake revealed that the government remains in “consideration mode” regarding whether Sri Lanka will enter into a follow-up Extended Fund Facility (EFF) programme with the International Monetary Fund (IMF) once the active facility concludes in March 2027.
Participating in an engaging Fireside Chat at the inauguration of the Sri Lanka Economic and Investment Summit 2026, organised by the Ceylon Chamber of Commerce at the Shangri-La Colombo on October 12, the President emphasised that any future engagement with the IMF must afford adequate policy space for his administration to execute its own sovereign economic vision.
The session, moderated by Bingumal Thewarathanthri, Vice Chairperson of the Ceylon Chamber of Commerce and CEO of Standard Chartered Bank Sri Lanka, saw the Head of State outline a comprehensive roadmap spanning macro-fiscal discipline, port infrastructure expansion, energy sector restructuring, fuel pricing dynamics, and technology training.
Addressing a packed hall of top-tier business leaders, diplomats, and international investors, President Dissanayake noted that while the current IMF arrangement has proceeded without impeding the government’s core economic strategy, a prospective post-March program will undergo rigorous evaluation.
“Our foreign reserve levels are satisfactory for paying our way through the world. However, there is global uncertainty amid the current geopolitical situation. No indicators can say when the war will end or what weather-related disasters could happen,” the President remarked, referencing external vulnerabilities such as Middle Eastern tensions and local climate disruptions like Cyclone Ditwah.
He stressed that while macro-fiscal parameters – including progressive revenue targets and debt-ceiling management – remain fundamental to national stability, the government is acutely conscious of the tax burdens and social costs borne by citizens. Therefore, any future framework proposed by the IMF will be examined through the lens of domestic policy autonomy and social protection.
Turning to critical national assets, President Dissanayake announced bold restructuring plans for the Port of Colombo aimed at elevating Sri Lanka’s position as a dominant regional maritime hub.
East Container Terminal (ECT): The government intends to grant management and operating rights of the ECT to a private sector partner while retaining 100% state ownership. Operating under the Sri Lanka Ports Authority (SLPA), the terminal currently handles approximately 500,000 TEUs against a potential capacity of 3.2 million TEUs. Five to six major global shipping lines have already expressed preliminary interest.
West Container Terminal II (WCT II): A funding requirement of approximately $1.4 billion for breakwater infrastructure is being sought from multilateral development institutions. Preliminary design work, assisted by the Asian Development Bank (ADB), is slated for completion by April 2027, adding another 3.2 million TEUs in annual throughput capacity upon full buildout.
Logistics Hub & Custom Clearance: The SLPA will call fresh tenders for a dedicated logistics center within the Port of Colombo following the resolution of land disputes. Additionally, Cabinet approval has been granted for a Public-Private Partnership (PPP) to establish a 150-container examination facility in Kerawalapitiya to streamline Customs clearance.
Addressing energy security and domestic distribution, the President indicated that existing petroleum agreements with private market participants – including Lanka IOC and Sinopec – would undergo formal review involving the Attorney General.
Expressing concern over distribution bottlenecks in outstation areas where private outlets dominate, President Dissanayake called on private players to balance profit margins with social responsibility during times of price volatility. To guarantee uninterrupted national supply, the Ceylon Petroleum Corporation (CPC) plans to add 75 new filling stations across the island.
Furthermore, to enhance maritime competitiveness, the government is considering lowering the 2.5% tax/levy on bunkering services in Budget 2027 and exploring CPC-private partnerships for bunker fuel storage expansion at the JCT Oil Bank.
In renewable energy, the government will open four major grid transmission lines for private-sector participation and transition away from fixed feed-in tariffs set by the Public Utilities Commission of Sri Lanka (PUCSL) toward competitive bidding to drive down generation costs. Floating solar projects, such as the Ibbankatuwa model, will be prioritised to overcome land availability constraints.
In a bid to address structural workforce shortages in high-tech sectors, the President revealed that Sri Lanka will sign an agreement with Singapore next week to establish a specialized training institute on Wijerama Mawatha in Colombo. The center will focus on rapidly expanding local capacity in Information Communications Technology (ICT) and Artificial Intelligence (AI).
He also highlighted plans to restructure public sector remuneration for highly skilled professionals and proposed an outcome-based procurement model for international promotional campaigns, such as global tourism marketing, where agencies are compensated based on verified growth in tourist arrivals.
By Hiran H. Senewiratne
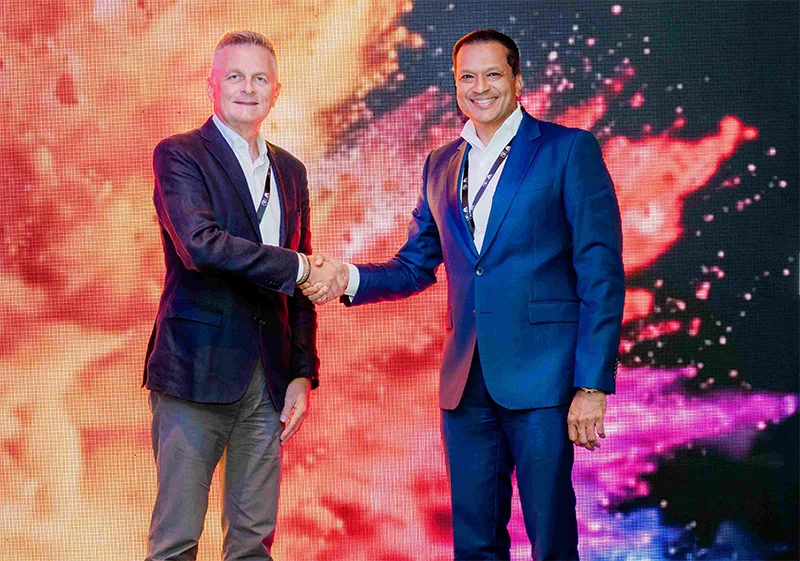
‘Sri Lanka is a top market in the South Asian region for quality powder coatings, Franck Derouen, Business Director, Industrial MEA – West & Central Asia, Axalta Coating Systems (ME) LLC, said.
‘We see significant long-term potential for powder coatings in Sri Lanka and look forward to working closely with Richardson Holdings to offer Axalta’s technology, expertise and global standards for all customers, Derouen said at a launch of the products in Sri Lanka together with Richardson Holdings recently. The event was held at the ITC Ratnadipa, Colombo.
Derouen added: ‘More than a brand transition, this appointment comes as project volumes and material demand continue to rise across Sri Lanka’s construction and property development sectors, giving developers and specifiers greater access to premium performance powder coatings at a time of renewed industry activity.
‘For architects, engineers, extruders and applicators, Axalta’s powder coatings combine UV resistance, gloss retention and corrosion protection with the technical performance expected for long-term architectural projects.’
Group Managing Director, Richardson Holdings, Nazri Nizar said, ‘A strong global brand might open the door. However long-term customer trust is built locally through dedicated support and reliable delivery. The true measure of a distributor lies in the service, care, and operational execution which follows after the product arrives.
‘Combining Axalta’s 150 years of global coating expertise with Richardson’s two decades of deep local relationships and technical know-how, we are bringing customers the best of both worlds.
‘Bridging global standards with local expertise, Richardson Projects will serve as Axalta’s trusted local powder coatings partner, combining global technology with two decades of on-the-ground experience serving Sri Lanka’s construction ecosystem.’
Pradeep Kahawalage, Chief Executive Officer, Richardson Projects, said, ‘After two decades building trust in Sri Lanka’s powder coatings industry, this marks an important new chapter for Richardson. Axalta gives us a global technology partner that matches the standards we have already built our reputation on. We are excited to bring that expertise to Sri Lanka’s construction and aluminium industries in the years ahead.
‘With a focus on sustainability, technical excellence and long-term partnership, Richardson looks forward to supporting architects, developers, fabricators and applicators throughout Sri Lanka with Axalta powder coating as the industry continues to grow.’
By Steve A. Morrell
Headquartered in Norway, Sri Lanka’s 99x office is emerging as a global leader in digital product engineering and tech solutions.
The above products and their development are prioritized in even local university level digital technology centered courses of study. Priority is increasingly attached to them in the context of career development.
Shehani Seneviratne, Chief Operating Officer of 99x Product Engineering, while reiterating the importance of these subject areas at a recent event stressed their continued centrality in degree level courses of study.
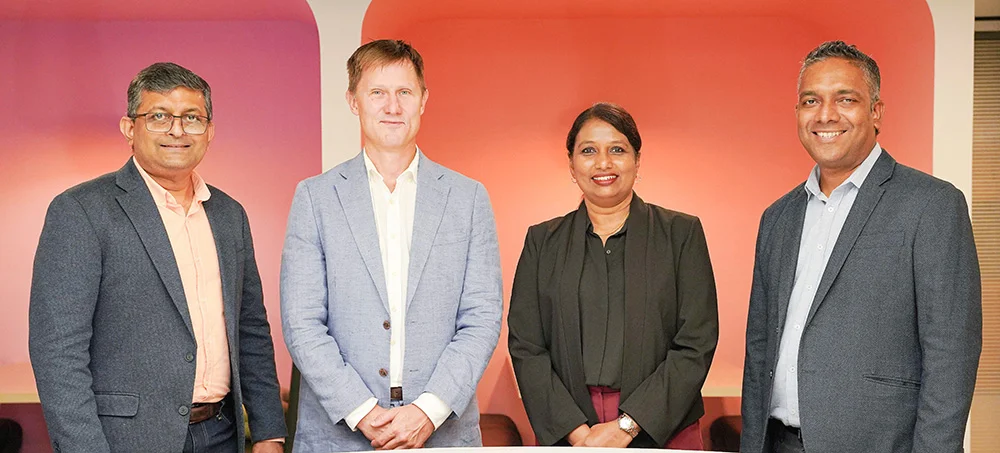
The event brought together members of the 99x leadership team including Odd-Sverre Østlie, Group CEO of 99x, Kalana Wijesekara, Chief Developer Experience Officer, Shehani Seneviratne, Chief Operating Officer, 99x Product Engineering, and Chrishan de Mel, ChiefMarketing and Corporate Affairs Officer of 99x Product Engineering.
Opening the event, Chrishan de Mel shared how 99x’s Agent Control Plane xians.ai was awarded the “Best Agentic AI Solution” at the recently concluded National AI Awards. The platform was also awarded national recognition at the SLASSCOM National Ingenuity Awards as the “Best Innovation in Internal Processes, Technology or Framework” category. Earlier this year, the 99x AI-first initiatives won the overall gold award at the Best Management Practices awards.
As 99x expands its use of AI tools and agents across engineering, support and other functions, the company recognised the need for greater visibility into how these AI-assisted workflows perform. As AI continues to reshape traditional engineering workflows, it also creates new opportunities to improve productivity, quality and speed. This need led to the development of AI Hub, 99x’s new platform for observing and measuring AI assisted workflows.
Speaking at the AI Hub launch, Kalana Wijesekere said, AI adoption is happening at a remarkable pace but adopting more tools does not automatically mean achieving better outcomes. AI Hub gives teams the visibility to understand what is happening within their AI assisted workflows and enables them to make informed decisions about how these workflows should evolve.
Sharing an update on the 99x group’s global journey and market outlook, Odd-Sverre Østlie highlighted the company’s continued expansion across Europe, the Americas and Asia, alongside growing demand from customers seeking to integrate AI into their products and operations. He stated, ‘AI is fundamentally changing the expectations our customers have from their technology partners. They want to move faster, experiment more quickly and increasingly understand how AI can create measurable business value. Our ambition is to be a long-term engineering partner that can help customers navigate this transformation. The launch of AI hub advances 99x’s AI-first strategy moving beyond the adoption of AI tools.’

Heavy showers above 100 mm are likely at some places in the Western, Sabaragamuwa, Southern, Central, and North-western provinces and in Anuradhapura district.

Sri Lanka, India caught in US-Iran ship crisis

Namal further remanded

IMF projects Lankan economic growth to moderate amidst mounting global uncertainties

Major Gen Pushpakumara assumes command of 56 Infantry Division

Dickwella axed, Bandara earns maiden Test call up

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 Features7 days ago
The Sri Lankan who made Scottish history
-
 Sports7 days ago
Nissanka absence opens door for Sri Lanka’s young guns
-
 News6 days ago
NDB fraud Rs 60mn more than reported
-
 News6 days ago
Removing monk’s robes matter for Sangha to decide: Mahanayake Theras
-
 News7 days ago
Shiranthi R remanded until 13 Oct.
-
 Features7 days ago
Future of Sri Lanka’s state university system: Should it be shut down and reopened?
-
 News4 days ago
Sri Lanka escalates anti-graft drive with Shiranthi’s jailing
-
 News5 days ago
NPP govt. reminded of its responsibilities as US warship leaves Colombo