Features
Tariffs as business deals?


From White House to Wall Street:
 I am going to examine the financial market repercussions of President Donald Trump’s 2025 tariff policies, focusing on equities, bonds, derivatives, and interest rates. It explores how asymmetric information and alleged insider trading influenced market dynamics, highlighting the challenges posed to market integrity and investor confidence.
In 2025, President Donald Trump’s administration implemented a series of tariffs targeting major trading partners, including China, Canada, and Mexico. These policies aimed to protect domestic industries but resulted in significant volatility across global financial markets. The sudden shifts in trade policy introduced uncertainty, affecting various asset classes and raising concerns about the exploitation of insider information.
In response to escalating market turmoil and international pressure, President Trump announced a 90-day deferral on certain tariffs, via social media on April 9, 2025. However, the announcement’s ambiguity led to continued market instability.
Pre-Tariff Market Conditions
(February 2025)
In February 2025, US financial markets were experiencing relative stability. The S&P 500 was trading near record highs, buoyed by strong corporate earnings and positive economic indicators. Interest rates remained steady, with the 10-year Treasury yield hovering around 3.9%, reflecting moderate inflation expectations and a balanced economic outlook. The CBOE Volatility Index (VIX), a measure of market volatility, was subdued, indicating investor confidence.
Impact on Financial Markets
Equities and Traditional Investment Strategies
The announcement of tariffs led to a sharp decline in US stock markets. Major indices, such as the Dow Jones Industrial Average and the Nasdaq Composite, experienced significant losses, with the Nasdaq entering bear market territory after a 5.82% drop. The traditional 60/40 investment strategy, allocating 60% to equities and 40% to bonds, proved ineffective during this period, as both asset classes suffered losses due to rising bond yields and falling stock prices (Figure 1).

Market Indices (S&P 500, Nasdaq, Dow Jones): Major crashes occurred on April 3–4, 2025, following the tariff imposition. Slight recovery or stabilisation followed Trump’s deferral tweet on April 9, but markets dipped sharply again on April 10 (Table 1).

Market Reaction to Tariff Imposition
(April 2–5, 2025)
* April 3, 2025: The S&P 500 plummeted by 4.88%, the Nasdaq Composite fell by 5.97%, and the Dow Jones Industrial Average declined by 3.98%. The Russell 2000 entered bear market territory, dropping over 20% from its recent peak.
* April 4, 2025: Markets continued their downward trajectory. The S&P 500 fell an additional 5.97%, the Nasdaq Composite decreased by 5.82%, and the Dow Jones Industrial Average dropped by 5.50%.
* April 5, 2025: The newly imposed tariffs officially took effect, further exacerbating market volatility and investor uncertainty.
* Over this period, US stock markets lost approximately $6.6 trillion in value, marking the largest two-day loss in history.
Market Response to Tariff Deferral
(April 9–11, 2025)
* April 10, 2025: Despite the deferral, the S&P 500 declined by approximately 15%, and long-term Treasury bonds faced significant selling pressure. The US dollar weakened, and gold prices surged as investors sought safe-haven assets.
* April 11, 2025: Consumer sentiment plummeted, with the University of Michigan Consumer Sentiment Index dropping to 50.8, the second-lowest level since records began in 1952. This decline reflected widespread economic pessimism amid the ongoing trade tensions.
Bond Market and Interest Rates
The bond market reacted to the tariffs with increased yields, reflecting investor concerns about inflation and economic growth. The US 10-year Treasury yield rose to 4.358%, indicating expectations of higher interest rates. This rise in yields contributed to the decline in bond prices, further challenging traditional investment strategies.
10-Year Treasury Yield: Climbed steadily from 3.9% to 4.358% (April 2–21), suggesting increased inflation expectations and risk premium. The bond market experienced significant fluctuations during this period. Therefore, investors demanded higher returns for perceived increased risk. This rise in yields indicated expectations of higher inflation and potential economic slowdown due to the tariffs. (Table 2).

Derivatives and Market Volatility
The derivatives market, including options and futures, experienced heightened volatility in response to tariff announcements. The CBOE Volatility Index (VIX), often referred to as “Wall Street’s fear index,” spiked to its highest level since 2020, closing at 45.31 points. This surge in volatility presented both risks and opportunities for investors, particularly those with access to timely information.
VIX Volatility Index: Rose from 19 on April 2 to a peak of 45.31 on April 4, indicating extreme market fear. The VIX spiked to 45.31, its highest level since 2020, indicating heightened market anxiety (Table 3).

Asymmetric Information and Insider Trading Allegations
Allegations of insider trading emerged during the tariff saga, highlighting concerns about asymmetric information. Congresswoman Marjorie Taylor Greene faced scrutiny for stock transactions made shortly before tariff announcements, including purchases in companies like Amazon and Tesla, and the sale of Treasury bills. While Greene denied insider knowledge, the timing of these trades raised questions about the potential exploitation of non-public information (The Times, 2025).
Additionally, unusual trading patterns in S&P 500 futures preceding major policy shifts suggested possible insider activity. Although direct evidence linking these trades to White House insiders remains inconclusive, the patterns underscore the challenges in detecting and preventing insider trading in policy-driven markets (Los Angeles Times, 2025).
Tariff Decisions as Business Deals
While tariffs are typically seen as instruments of trade policy aimed at protecting domestic industries or rebalancing trade deficits, the Trump administration’s 2025 tariff imposition and abrupt deferral appear less rooted in strategic policy and more akin to short-term market manipulations. These decisions unfolded not through institutional processes or legislative debates, but rather through presidential tweets and sudden reversals, strongly suggesting a deal-making mindset characteristic of business negotiations rather than public governance.
The Role of Asymmetric Information and Market Elites
Insider trading is traditionally associated with illegal access to non-public corporate information. However, in this case, asymmetric political information—known only to a select few close to power—may have created an opportunity to profit.
Market actors with proximity to decision-makers, or even sophisticated algorithms tied to social media monitoring, could have anticipated the tariff deferral.
Billionaire investors and influencers like Elon Musk, who maintain both financial influence and political access, are often speculated to benefit from such opaque decision-making environments. The quick reversal of tariffs led to a surge in tech stocks, many of which form the core holdings of large institutional investors, hedge funds, and elite entrepreneurs.
For example: The Nasdaq rebounded by 1.5% following the deferral tweet. Options trading volumes spiked on tech-heavy indices, indicating pre-positioning by well-informed actors. Reports from Bloomberg and Reuters noted unusual activity in Tesla call options shortly before the deferral (Reuters, 2025; Bloomberg Markets, 2025).
A Business Deal Mindset
Trump’s own language underscores the deal-making philosophy. The President tweeted that the tariffs were a “strong hand in negotiations” and “paused for talks with China”, using terms more common in corporate boardrooms than diplomatic channels. This rhetoric, combined with the lack of institutional transparency, raises serious concerns about the manipulation of public policy for private gains.
In this light, the administration’s behaviour is not reflective of classical economic policy objectives like comparative advantage or strategic protectionism. Instead, it aligns with the wealth-maximising tactics of a private enterprise, where the aim is to control narrative, timing, and volatility to benefit select stakeholders.
Conclusions
More critically, the Trump tariff saga of 2025 blurs the lines between public policy and private profit. The opacity, erratic timing, and informal communication channels—particularly via presidential tweets—suggest that these were less about coherent trade strategies and more akin to orchestrated business maneuvers. The reactive movements of major indices, coupled with unusual options trading patterns and speculative capital flows, indicate that market elites likely capitalised on volatility, benefiting from privileged access or predictive positioning based on asymmetric information.
This raises serious concerns about market integrity and the ethical boundaries between governance and profiteering. When financial markets are left vulnerable to abrupt and opaque political actions, especially ones lacking institutional oversight, the door opens to manipulation, insider trading, and erosion of public trust.
In sum, the 2025 Trump tariff episode serves as a cautionary tale—one that highlights the dangers of politicising economic policy, the vulnerabilities of global markets to personalised decision-making, and the importance of upholding the foundational principles of fairness, transparency, and accountability in modern financial systems.
(The writer, a senior Chartered Accountant and professional banker, is Professor at SLIIT University, Malabe. He is also the author of the “Doing Social Research and Publishing Results”, a Springer publication (Singapore), and “Samaja Gaveshakaya (in Sinhala). The views and opinions expressed in this article are solely those of the author and do not necessarily reflect the official policy or position of the institution he works for. He can be contacted at saliya.a@slit.lk and www.researcher.com)
by Jehan Perera
International Peace Day was observed on 21 September. It finds Sri Lanka with a genuine achievement to record and a demanding test to meet. The UN’s theme this year was “Invest in Peace: For Everyone, Everywhere, Every Day.” It also honoured the “everyday architects of peace”—people driving local action and building a lasting peace from the ground up. In the 2026 Global Peace Index, Sri Lanka rose 30 places, from 97th to 67th among 163 countries. Over the same period, global peacefulness declined for the twelfth consecutive year to its lowest level since the index began, and South Asia suffered the sharpest regional deterioration. The test is whether the government will protect the civic space in which those architects of peace work.
Sri Lanka’s improvement is real and deserves acknowledgement. In this year’s review, issued a few weeks ago, the UN High Commissioner for Human Rights acknowledged progress in the form of action against corruption, arrests and investigations linked to political killings, enforced disappearances and the 2019 Easter Sunday attacks, and continued official denunciation of racism. A ranking, however, records conditions at a particular moment. It does not guarantee that they will last. Sustainable peace will depend on three factors. These are whether the government addresses the unresolved causes of conflict, whether it strengthens accountability for past and present abuses, and whether it protects the civic space in which peace is built from below. On the first two the record is incomplete. On the third, the draft NGO law threatens to weaken the very organisations that press for the other two.
What holds Sri Lanka back from a higher place are the same things that fed the war at home and also feed international conflict that rages elsewhere in the world. These are racism or ethnic nationalism that is narrow-focused, corruption and lawlessness. Equality, accountability and the rule of law are their remedies. The present government has committed itself to these, and is a significant improvement over governments of the recent past. But these pillars are not held up by governments alone. Peace is made in villages, workplaces and university campuses. It is made by families who insist on the truth about their disappeared, by journalists and lawyers who expose abuse, and by community organisations that bring Tamils, Muslims and Sinhalese into practical cooperation.
Unfinished Work
The UN High Commissioner’s report to the current Human Rights Council session, covering October 2025 to July 2026, shows how much remains to be done. The Prevention of Terrorism Act is still being applied, producing arbitrary arrests and long detention without charge. The report calls for a moratorium pending repeal and for the release of long-term detainees. Military-occupied land has not been released, memorialisation lacks support, and tensions over land and religious sites persist. The Batticaloa district illustrates how such problems endure. In the past three years, two Presidents, Ranil Wickremesinghe and Anura Kumara Dissanayake, have visited and instructed that the dispute over grazing land in Mailaththamadu and Mathavanai be resolved. It is a dispute between Tamil cattle farmers and outside Sinhala cultivators, and it has not been resolved. When two Presidents issue instructions and nothing changes, the fault lies in the machinery of State. An unresolved dispute does not stand still. It hardens into the next grievance.
Accountability shows the same pattern. The report documents torture and deaths in custody, and surveillance and intimidation of activists, journalists and civil society. Serious cases remain stalled for years, among them the killing of seventeen aid workers of Action Contre la Faim in Muttur two decades ago. Sharper still is the case of the Eastern University refugee camp at Vantharamoolai, where in 1990 the army took away 158 persons in a single day. They were never seen again. The camp’s officer-in-charge, Dr T. Jayasingam, later Vice Chancellor of the university, identified the officers responsible. More than three decades on, those officers have not been questioned. These cases are still remembered because families, survivors and independent witnesses have refused to let them be forgotten. Meanwhile several commissions of inquiry have completed their investigations but nothing further has happened.
What South Africa, Argentina and other post-conflict societies have found indispensable are four pillars of what is called “Transitional Justice” which are truth, accountability, reparations and non-recurrence. In Sri Lanka’s circumstances, truth means credible, independent investigation of what happened to the disappeared, and support for memorialisation. Accountability means prosecuting Muttur, Vantharamoolai and comparable cases, and removing credibly accused persons from senior office. Reparations mean compensation for victims and the return of military-held land. Non-recurrence means repealing the Prevention of Terrorism Act, releasing those held under it in the meantime, and resolving local disputes such as Mailaththamadu before delay hardens them. A country that buries its past does not escape it. The past returns in the next generation.
Civil Society
It is against this background that the draft NGO law is most troubling. The proposed legislation contains sweeping provisions for State oversight and control of civil society organisations. Among these are enforcing a licensing requirement on NGOs, which is to be renewed every three years, and severe penalties for not submitting reports on time, or for spending on emergency flood relief (for instance) when the NGOs mandate is peacebuilding (as an example) with possible sanctions including deregistration and having to shut down. Civil society groups have warned that it would confer excessive discretion over their registration and operations. Officials in Sri Lanka have abused such powers in the past. Additional power without effective checks invites further abuse. Sound regulation would have clear criteria for registration, an independent registrar and a right of appeal to the courts. What cannot be justified is a regime in which registration becomes a licence to be withheld from organisations that scrutinise policy, expose abuses or advocate for the rights of citizens.
Democracy is based on checks and balances. Those who press for accountability are part of those checks. The contradiction is plain. A government that has pledged accountability, equality and the rule of law ought not to be preparing to weaken the very organisations that press for their fulfilment. The organisations most exposed are those working on disappearances, land, memorialisation and reconciliation in the North and East, where the State’s record is weakest and the need for independent witnesses greatest. Silencing them would not remove the grievances they document. It would remove the channel through which those grievances are addressed peacefully. The government appears to be relenting, which is welcome, but a pause is not a withdrawal. The bill should be withdrawn and any replacement drafted in genuine consultation with those it would govern.
Investment in peace as called for by the UN in its International Peace Day theme implies commitment over time, with returns that come slowly. Sri Lanka’s 30-place rise on the Global Peace Index is a first dividend and nothing more. It can be built upon only if the government matches its commitments with action: withdrawing or fundamentally redrafting the NGO law, repealing or suspending the Prevention of Terrorism Act, and bringing Muttur, Vantharamoolai and Mailaththamadu to resolution. A higher place in a global index is not a certificate of success. Sri Lanka’s higher ranking is an encouraging start, but it will endure only if the space in which citizens speak, question and organise is protected. Peace is built from below, and a government that is serious about it will treat civil society as a partner rather than a threat.
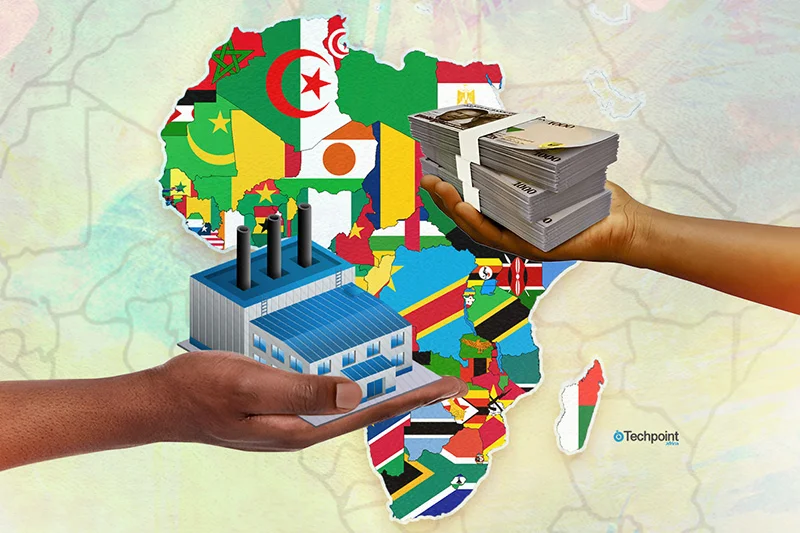
A call to Sri Lankan exporters and agencies: Can Sri Lanka compete with China and India in Africa?
By Kana V. Kananathan
Former Ambassador
Sri Lanka has spent decades concentrating its exports on traditional markets in Europe, North America and Asia. Yet across the Indian Ocean lies a rapidly expanding market that remains significantly underdeveloped by Sri Lankan exporters: Africa.
The opportunity is not theoretical. Sri Lanka already exports packaging, textiles, rubber products, pharmaceuticals, paper, machinery and electrical goods to African markets. The question is whether these modest beginnings can be transformed into a serious export strategy—and whether Sri Lanka can compete against the enormous commercial presence of China and India.
The answer is yes—but Sri Lanka must compete differently.
Kenya: Gateway to East Africa
Kenya should be the starting point.
Sri Lanka exported approximately US$32.08 million to Kenya in 2025, while importing US$11.41 million. But US$32 million is tiny compared with the opportunity: Kenya imported more than US$24 billion in 2025. Even a 1% share of that market would represent nearly US$240 million in annual exports.
And the commercial base already exists. Sri Lanka’s 2025 exports to Kenya included approximately US$9.99 million in paper and paperboard products, US$9.73 million in knitted fabrics, US$3.64 million in pharmaceuticals, US$1.24 million in rubber products and US$1.20 million in machinery.
Kenya’s import structure is equally revealing. In the third quarter of 2025, industrial supplies represented 34.4% of imports, machinery and capital equipment 19.2%, food and beverages 9.0%, and consumer goods 7.3%. The opportunity for Sri Lanka, therefore, extends well beyond consumer goods—we can become a supplier to African industry.
But competition is fierce. Asia supplied around 70% of Kenya’s imports in 2025, with imports from China rising 16.5% and those from India 11.3%.
Sri Lanka cannot challenge China and India across every product category. Nor should it try. We must target sectors where quality, specialisation, reliability, technical capability, smaller production runs and flexibility matter more than simply offering the lowest price.
Where Can Sri Lanka Compete?
Packaging is an obvious starting point. Cartons, boxes, bags and labels are already among Sri Lanka’s exports to Kenya. Importantly, some Sri Lankan companies operating in Kenya are themselves importing these products from Sri Lanka. The market already exists; the challenge is to scale it.
As Africa’s food-processing, pharmaceutical, apparel and consumer-goods industries expand, demand for sophisticated packaging will grow with them. Sri Lanka already possesses the manufacturing capability and industry experience to capture a larger share.
Industrial rubber products, tyres, gloves and specialised rubber components offer another opportunity where Sri Lanka has established manufacturing expertise.
The apparel supply chain is equally promising. Rather than competing directly with African garment factories, Sri Lanka can supply fabrics, elastics, labels, packaging and specialised textile inputs.
Some Sri Lankan apparel manufacturing and export companies already established in Kenya, Togo, Ghana and Ethiopia are importing several of these inputs from Sri Lanka. The supply chain, therefore, already exists. The next step is to move beyond supplying Sri Lankan-owned factories and become a competitive input supplier to the wider African apparel industry.
Other sectors deserving systematic market development include pharmaceuticals and medical consumables, processed foods, biscuits and confectionery, coconut products, cinnamon and spices, electrical products and cables, industrial chemicals, ceramics, light engineering, agricultural equipment and food-processing machinery.
Sri Lanka should also look beyond physical goods. IT, fintech, banking technology, engineering, healthcare, hospitality management and professional services largely escape the freight disadvantage confronting merchandise exports.
The Tariff Problem Can Become an Opportunity
Market access cannot be discussed without tariffs.The East African Community applies a Common External Tariff with bands of 0%, 10%, 25% and 35%, while certain sensitive products attract still higher protection. Simply filling containers in Colombo with finished consumer goods will therefore not always be commercially competitive.
But that obstacle points towards a bigger opportunity: manufacture in Africa.
Sri Lankan businesses could export intermediate materials while undertaking final assembly, manufacturing, processing or packaging in Kenya. Packaging companies could establish converting plants; electrical manufacturers could assemble locally; pharmaceutical companies could explore manufacturing or packaging partnerships; and food companies could undertake final processing closer to consumers.
Kenya would then become more than an export destination. It could become Sri Lanka’s manufacturing and distribution gateway into East and Central Africa.
With the East African Community now comprising eight partner states and extending geographically from the Indian Ocean towards the Atlantic, establishing a regional presence is increasingly more important than viewing each African country in isolation.
West Africa Cannot Be Ignored
Sri Lanka simultaneously needs a West African strategy.
Ghana offers potential as an English-speaking commercial gateway and host of the AfCFTA Secretariat. Nigeria, with its enormous population and consumer economy, should be approached as a major market in its own right, despite its greater regulatory, currency and operational complexity.
ECOWAS tariff bands of 0%, 5%, 10%, 20% and 35% again make product selection critical. Sri Lanka should concentrate on products with sufficient differentiation and margins to absorb freight, tariffs and distributor costs.
Pharmaceuticals demonstrate both the opportunity and the challenge. Nigeria imported approximately US$766 million in pharmaceuticals in 2025, with India supplying roughly US$394 million and China US$131 million. Ghana imported approximately US$301 million, with India supplying about US$140 million.
Sri Lanka cannot simply offer another generic product and expect to beat India on price. We must identify specialised products, reliable supply arrangements, partnerships and, where commercially justified, local production or packaging.
Stop Promoting Sectors—Identify Products
Sri Lanka now needs an Africa Export Opportunity Study based on individual products, not broad sectors.
The Export Development Board, Foreign Ministry, chambers and private sector should jointly identify 15–20 priority products. For each product, Sri Lanka should calculate the HS code, African annual import demand, principal suppliers, Chinese and Indian market shares, applicable duties, freight from Colombo, regulatory requirements, distributor margins and final landed price.
That will tell us where Sri Lanka genuinely has a competitive advantage.
The Commercial Test
Before spending resources promoting a product, apply one simple test:
African import demand + Sri Lankan production capability + tariff + freight + distributor margin + regulatory cost = final landed competitiveness against China, India and local African production.
Only products that pass this test should receive concentrated export-promotion resources.
This would move Sri Lanka away from exhibitions, delegations and general discussions towards what ultimately matters: specific products, specific buyers, specific distributors and actual export orders.
Give Our Missions Targets
Commercial diplomacy must become results-driven. The Government should set clear annual trade and investment targets for every Sri Lankan mission in Africa.
Missions should be evaluated not merely on diplomatic activity, but on buyers and distributors identified, business introductions made, investments facilitated, market barriers resolved and measurable exports generated.
In a competitive Africa, our missions must become active economic frontlines not merely diplomatic outposts.
A practical strategy could operate through three commercial gateways: Nairobi for East and Central Africa, Accra for selected West African markets and Lagos for Nigeria.
Sri Lanka’s total exports of goods and services reached approximately US$17.25 billion in 2025. Capturing even a small additional share of Africa’s enormous import market could, therefore, make a meaningful contribution to export earnings, investment and foreign-exchange generation.
Africa Will Not Wait
Sri Lankan exporters must stop looking at Africa as a distant or difficult market and start treating it as a strategic growth market.
We cannot compete with China and India on scale, but we can compete on quality, specialisation, flexibility and reliability. Exporters must identify country-specific opportunities, establish strong local distributors, build partnerships with African businesses and use Sri Lankan companies already operating on the continent as gateways into regional supply chains.
Where freight and tariffs weaken competitiveness, businesses must be prepared to move towards local assembly, joint ventures and manufacturing in Africa. Exporters cannot do it alone. They need aggressive, measurable and results-driven commercial diplomacy from Sri Lanka’s missions.
Africa is buying. Its markets are being captured now. Sri Lanka must stop watching from the sidelines. We must enter, compete, build our presence and secure our share.
(Ambassador Kana Kananathan is a businessman, Diplomat, lobbyist and an expert in African affairs, with over four decades of experience on the African continent. A long-time resident of Africa, he served as Sri Lanka’s envoy to Uganda and Kenya, with concurrent accreditation to 22 African Nations, and was the permanent representative to UN Habitat and UN environmental Programme. Over the years, he has been the Elections Monitor across the continent, working closely with African governments, and built enduring partnerships with African leaders. He also served as Economic and Investments Advisor to former President Professor Alpha Condé of the Republic of Guinea)
 The heart of a great 31st Night dance is memory, and memories come rushing back when those 70s, 80s and 90s golden oldies begin to play — those timeless tunes that make revellers, young and old, rush to the floor and dance the night away.
A perfect 31st Night is not just a party. It is a journey. A journey through time.
The music should flow like a love story. Start slow, start soft. Let couples glide into a waltz for romance. Let the floor come alive with a twist, a rock ‘n’ roll, a jive. Let nostalgia build with beautiful sing-along oldies generally associated with a New Year’s Eve dance.
This is the art that many of our entertainers seem to have forgotten.
The final hour, before midnight, is sacred. It should be collective energy at its peak. The entire crowd, on the dance floor, linking arms, swaying together, singing, at the top of their voices, those sing-along favourites.
Yes, I’m referring to those immortal, nostalgic favourites that unite the world: ‘This Land Is Your Land,’ ‘You Are My Sunshine,’ ‘When The Saints Go Marching In,’ ‘Roll Out The Barrel,’ ‘Celebration,’ ‘She’ll Be Coming Round The Mountain,’ ‘Happy Days Are Here Again,’ and so many more.
One wonders if some of our modern entertainers have even heard of these nostalgia anthems that traditionally lead up to the dawning of the New Year! This is not just music; this is ritual.
Then comes THE moment: Lights dim. Music pauses. A hush falls. The countdown begins — 10, 9, 8… — hugs, wishes, tears of joy, and then … ‘Auld Lang Syne.’ Hands crossed, voices united, bidding farewell to the old and welcoming the new. That moment makes or breaks the night.
Here is the truth that many genuine 31st Night revellers feel but hesitate to say — an overdose of baila music at New Year’s Eve events is NOT welcome.
Of course, baila is required. Baila is our Sri Lankan heartbeat! But a 31st Night dance is for everyone.
When it’s ONLY baila, the twist and rock n’ roll lovers, the waltz kings and queens feel left out. And they are the very people who MADE nostalgia! They are the die-hard revellers who have kept the 31st Night spirit alive for decades.
A family mentioned to me that they went along with friends for a 31st Night dance, in the city, to usher in 2026, and were thoroughly disappointed with the setup.
The bands in attendance, they said, failed to generate the excitement generally associated with a 31st Night event.
If given a free hand, the music at certain Colombo venues will be mostly baila, and that is going to disappoint many. Some are already worried that it will be just a baila scene this year, as well.
A memorable 31st Night respects all rhythms … yes, a waltz for romance, a twist and rock n’ roll for that 60s magic, a cha-cha, a slow foxtrot, and then the baila, after the countdown anthem.
That balance is what makes it inclusive, classy, and truly fun-filled.
Organisers, especially in Colombo, should keep this in mind: let it be 70% nostalgia – Western, and 30% baila, with the last hour left for pure baila madness, after the New Year is in!
Organisers must work out the programme for their 31st Night and instruct the entertainers to follow those instructions. The band should not dictate the night; the spirit of nostalgia should.
This New Year, let’s give Colombo what it truly wants — memories, midnight magic, and music for every soul on the floor.
Let’s dance into 2027 with class.

High Court convicts 14 over deadly Easter bombings

Mandhana, Shafali and Ghosh lead dominant India to Asian Games gold

Fatima Sana and Umm-e-Hani secure bronze for Pakistan in Asian Games

India bat first in Asian games womens cricket final

Showers about 100mm will occur in the Western, Sabaragamuwa, Central and North-western provinces and in Galle and Matara Districts

Govt. confident of 2/3 majority despite NPP split speculation

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-
 News6 days ago
US embassy won’t comment on IGP’s probe into joint drug raid
-

 News4 days ago
Shanakiyan urges urgent action over reported death sentence for Lankan in Saudi Arabia
-

 News5 days ago
Bid for Basil’s extradition nears final stage: Police
-
 Business6 days ago
All-new Bolero MaXX unveiled in Sri Lanka
-
 News3 days ago
Namal Rajapaksa Buddhist gambit fails, bail denied
-
 Opinion6 days ago
A journalist who wrote across the divide
-
 Editorial7 days ago
More fuel price shocks shrouded in secrecy
-
 Sports7 days ago
MAS Holdings, official clothing sponsor of Sri Lanka team at Aichi–Nagoya 2026 Asian Games