Business
Price hike likely of brand new vehicles – CAIA president

By Hiran H. Senewiratne
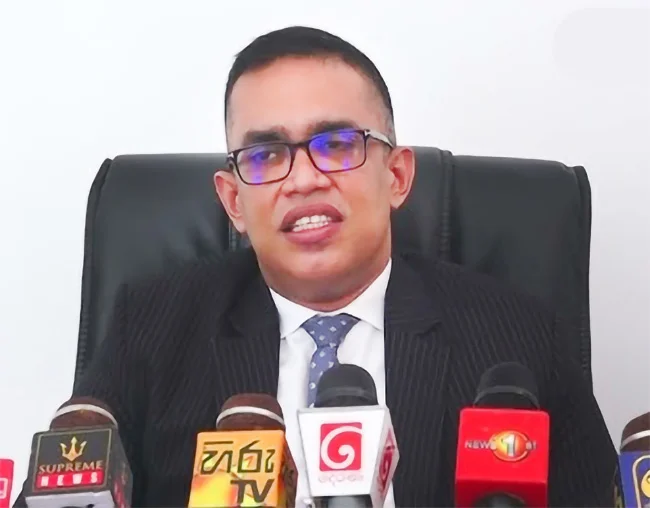
The prices of brand new imported vehicles would likely rise soon, given the global situation, president, Ceylon Automobile Importers Association (CAIA) Prasad Manage said.
‘If brand new vehicle prices move up it would badly impact especially young executives who are planning to purchase a new vehicle, Manage told The Island Financial Review. He made these observations recently at a media conference held at Shangri-la Hotel to announce the launching of ‘Motor Rally 2026’, organized by the CAIA for August 16.
Manage also highlighted that the Central Bank’s directive to the effect that leasing facilities should be limited to 40 percent of a vehicle’s value, has also had the result of reducing customers’ ability to purchase vehicles.
Manage added: ‘The government’s layered additional ad valorem taxes, including VAT and luxury taxes, on top of the specific excise duty, erase the original justification and create a severely burdensome environment.
‘Furthermore, taxing close substitutes differently heavily distorts consumption decisions and confirms the Association’s concerns over irrational categorizations and capacity-based penalties.’
Meanwhile, importers also said that beyond taxation at the border, tightening of macro-prudential measures could hinder prospective buyers. A primary hurdle is the current Loan-to-Value ratio applied to vehicle financing. Industry stakeholders pointed out that under the existing 50 percent restriction, purchasing an Rs. 18 million vehicle requires an upfront cash payment of Rs. 9 million, an impossible hurdle for most salaried professionals who rely on leasing facilities.
‘This affordability crisis has drastically shifted the aspirations of the country’s emerging workforce, importers added.
Addressing the gathering at the rally launch, Singer Finance Managing Director and Chief Executive Officer Thushan Amarasuriya emphasized how the current economic and regulatory landscape has rewritten the milestones of young professionals.
‘In the past, a young executive joining a company could buy their first car with the benefits provided by the company, but now it has become a major challenge with the surge in vehicle prices, Amarasuriya stated. Highlighting the stark reality facing the middle class today, he added, ‘Now we often see that for a young executive, a motorcycle is the first vehicle they can afford to make their vehicle dream come true.’
By Sanath Nanayakkare
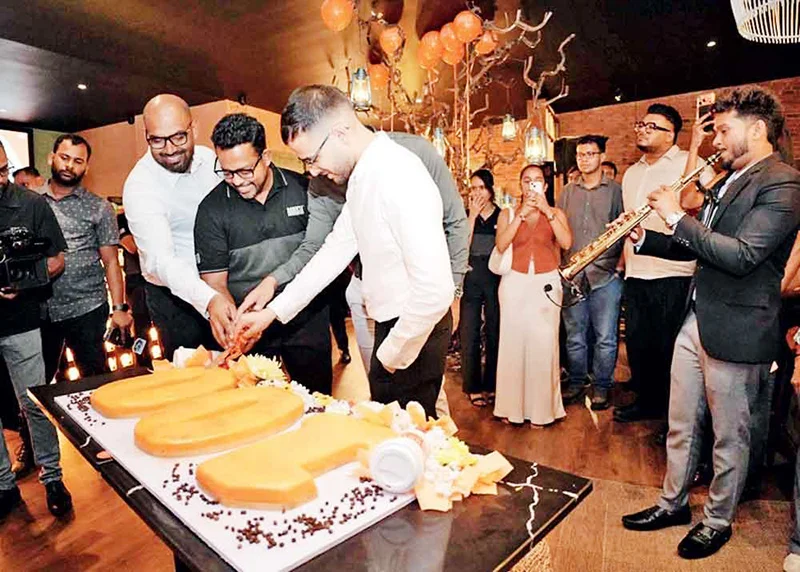
On Baseline Road in Colombo, Barista Coffee recently opened its 100th outlet. For a modern café culture spreading across shopping centers, office districts, and provincial towns, this milestone is a major commercial success. It shows a thriving urban service sector and a growing class of lifestyle consumers who use coffee shops as places to work, socialise, and meet.
This is a curious new picture emerging from Sri Lanka’s post-crisis economic recovery: the coffee cup is getting bigger, even as the household tea cup tells a very different story.
Yet, looking past the espresso machines, a different reality unfolds in the country’s kitchens.
International financial institutions note that while Sri Lanka’s macro-economy is recovering, household welfare and employment remain below pre-crisis levels. Poverty rates sit at roughly double what they were in 2019, and food prices doubled over a three-year span, forcing families to cut back on essentials.
This creates a striking local paradox, especially given Sri Lanka’s proud heritage as a global tea producer. While the world pays top dollar for Ceylon Tea, local market studies and industry reports have long pointed out an unfortunate disparity: many ordinary families find high-quality tea too expensive, often settling for lower-grade alternatives at home.
The growth of a 100-outlet coffee network does not mean prosperity has spread evenly across the island. Instead, it proves that there is a specific, well-resourced segment of consumers with the purchasing power to sustain a premium lifestyle economy, even as many other households carefully calculate the cost of everyday groceries.
Barista’s 100th store is not a bad-news story; it is a testament to acute entrepreneurial grit, shifting consumer behavior, and the vital revival of the nation’s urban service sectors. But it serves as an uncompromising reminder that macroeconomic stabilisation is not synonymous with household recovery.
As Colombo’s coffee culture looks toward its next hundred outlets, the true pulse of the nation’s economic health will not be measured by the espresso machines humming in sleek urban hubs, but by the quiet arithmetic happening in millions of kitchens beyond its doors – where the fundamental question remains whether a family can comfortably afford a better cup of Ceylon Tea.
Aitken Spence Hotel Holdings PLC announced that its maiden listed, rated, unsecured, senior
redeemable debenture issue was oversubscribed on its opening day, 15th September 2026.
The Company sought to raise Rs. 3 billion through an initial issuance of 30 million debentures at Rs.
100 each, with an option to issue a further 20 million debentures in the event of oversubscription of the initial issue, increasing the total issue size to Rs. 5 billion.
The Company said it had received applications for more than 50 million debentures, the full amount on offer, prompting the issue to close at 4:30 p.m. on the opening day (15).
The basis of allotment will be announced to the Colombo Stock Exchange as per regulatory requirements in due course.
By Ifham Nizam
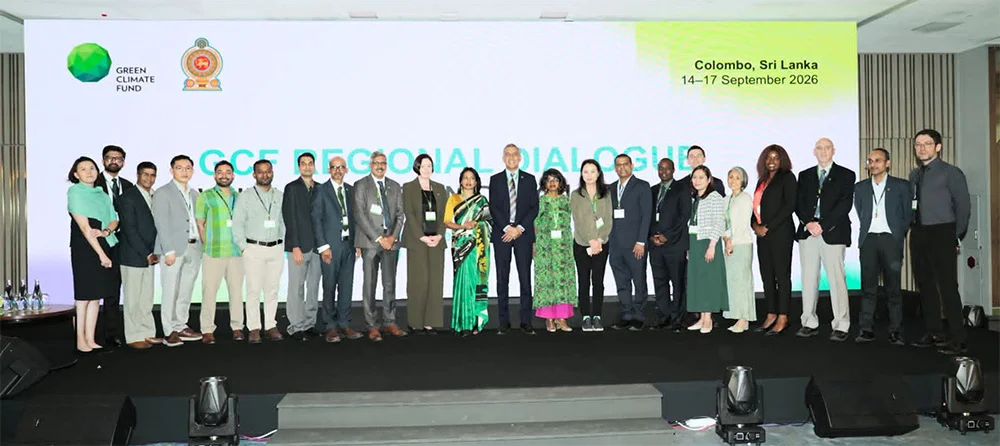
The widening gap between climate commitments and actual projects on the ground has come under the spotlight in Colombo, with the Green Climate Fund (GCF) calling for a decisive shift from pledges and plans towards implementation, investment and measurable climate impact across Asia.
Some 150 climate leaders, government representatives and development partners from East and South Asia have gathered in Colombo for the GCF’s Regional Dialogue, as developing economies across the region seek greater access to climate finance to strengthen resilience, accelerate clean investment and protect vulnerable communities from intensifying climate impacts.
The dialogue has also given Sri Lanka an important platform to highlight the financing challenge confronting a climate-vulnerable economy seeking to strengthen resilience while rebuilding economic capacity.
Opening the dialogue, Environment Minister Dr. Dammika Patabendi called for moving ‘from pledges to projects, from plans to implementation, and from ambition to impact,’ stressing that transformative climate action would require stronger partnerships, increased climate finance and greater support for adaptation.
His message carries particular significance for Sri Lanka, where climate-related disasters increasingly threaten agriculture, water resources, infrastructure, livelihoods and economic activity.
For a country with limited fiscal space, financing climate resilience entirely through domestic resources remains a major challenge. International climate finance therefore has the potential to become an important source of investment for projects designed not only to reduce emissions but also to protect communities and economic assets from increasingly severe climate shocks.
The Colombo dialogue provides an opportunity for Sri Lanka to strengthen its engagement with the GCF and other development partners while highlighting the need to convert national climate priorities into credible, investment-ready projects.
The GCF said its portfolio across Asia and the Pacific currently comprises 129 projects in 36 countries, supported by USD 5.8 billion in GCF financing. It has also approved USD 163 million in Readiness support to help countries strengthen their institutional capacity and ability to access climate finance.
These figures underline the growing scale of climate investment in the region, but they also highlight the importance of countries developing strong project pipelines capable of converting available finance into implementation.
For Sri Lanka, this is likely to be one of the most important dimensions of the current climate-finance discussion.
Projects aimed at strengthening climate-resilient agriculture, water management, disaster-risk reduction, renewable energy, resilient infrastructure and ecosystem protection require significant upfront investment.
Access to concessional and climate-focused international finance could help reduce the burden on public finances while enabling projects with long-term economic and environmental returns.
The need for adaptation finance was reinforced by the opening of the Colombo dialogue, which began with a moment of remembrance for those affected by last month’s glacial flood disaster in Nepal.
For Sri Lanka, a more country-responsive climate-finance system could be particularly valuable at a time when investment needs are high but public resources remain constrained.
As the GCF begins its third replenishment, the real measure of the next phase will therefore be whether climate finance can move faster from international commitments to national projects—and ultimately from project documents to tangible results on the ground.

Showers in most parts of the island today (17)

US embassy won’t comment on IGP’s probe into joint drug raid

Gnanasara Thera declares outside High Court that he wouldn’t flee

Namal further remanded

22A: LAWASIA questions compostion of five-judge bench

Sri Lanka’s lifestyle coffee culture boom and the two faces of its economy

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 Sports6 days ago
DDS set to lose Test captaincy
-
 News6 days ago
Sri Lanka faces new grid challenge as rooftop solar surges: former CEB GM
-
 Latest News6 days ago
Shafali, Deepti power India into sixth T20 Asia Cup final
-

 News4 days ago
Gnanasara Thero absconding after SC ruling
-
 Latest News5 days ago
Sri Lanka thwart Fatima Sana challenge to secure Asia Cup final spot
-

 News5 days ago
Ammunition cache found in old Kandy bungalow
-
 Editorial6 days ago
A flight of fancy
-

 News5 days ago
Green Climate Fund (GCF) Regional Dialogue for East and South Asia will be held from 14 to 17 September 2026 at Cinnamon Life at City of Dreams Hotel, Colombo