Features
The middle-class money trap: Why looking rich keeps Sri Lankans poor

 Every January, we make grand resolutions about our finances. We promise ourselves we’ll save more, spend less, and finally get serious about investments. By March, most of these promises were abandoned, alongside our unused gym memberships.
The problem isn’t our intentions, it’s our approach. We treat financial management as a personality flaw that needs fixing, rather than a skill that needs the right strategy. This year let’s try something different. Let’s put actual behavioural science behind how we handle our rupees.
Based on the article ‘Seven proven, realistic ways to improve your finances in 2026’ published on 1news.co.nz, I aim to adapt these recommended financial strategies to the Sri Lankan context.” Here are seven money habits that work because they’re grounded in how humans actually behave, not how we wish we would.
While these strategies offer useful direction for strengthening personal financial management, it is important to acknowledge that they may not be suitable for everyone. Many households face severe financial pressure and cannot realistically follow traditional income allocation frameworks, such as the well-known but outdated Singalovada Sutta guidelines, when even meeting daily food expenses has become a struggle. For individuals and families who are burdened by escalating costs of essentials, including electricity, water, mobile connectivity, transport, and other non-negotiable commitments, strict adherence to prescriptive models is neither practical nor fair to expect. Therefore, readers should remain mindful of their own financial realities and adapt these strategies in ways that align with their income levels, essential obligations, and broader personal circumstances.
1. Your Money Problems Aren’t Moral Failures, They’re Data Points
When every rupee misspent becomes evidence of personal failure, we stop looking for solutions. Shame is a terrible problem-solver. It makes us hide from our bank statements, avoid difficult conversations, and repeat the same mistakes because we’re too embarrassed to examine them.
Instead, try replacing judgment with curiosity. Transform “I’m terrible with money” into “That’s interesting, why did I make that choice?” Suddenly, mistakes become information rather than indictments. You might notice you overspend at Odel or high-end restaurant when stressed about work. Or that you commit to expensive plans when feeling socially pressured. Perhaps your online shopping peaks during power cuts when you’re bored and frustrated.
2. Forget the Year-Long Marathon, Focus on 90-Day Sprints
A Sri Lankan year is densely packed with financial obligations: Sinhala/Tamil Avurudu, Christmas, Vesak, and Poson celebrations; recurring school fees; seasonal festival shopping; wedding and almsgiving periods; yearend festivities; and an evergrowing list of marketing-driven occasions such as Valentine’s Day, Father’s Day, Mother’s Day, and many others. Each of these events carries its own financial weight, often placing additional pressure on already-stretched household budgets.
Research consistently shows that shorter time frames work better. Ninety days is long enough to create a meaningful change, but short enough to maintain focus and momentum. So instead of one overwhelming annual goal, give yourself four quarterly upgrades.
In the first quarter, the focus may be on organising your contributions toward key duties and responsibilities, while also ensuring that you are maximising the available benefits for your designated beneficiaries. Quarter two could be about building a small emergency fund, even Rs. 10,000 provides breathing room. Quarter three might involve auditing your bills and subscriptions to eliminate unnecessary expenses. Quarter four could be when you finally start that investment you’ve been postponing. You don’t need superhuman discipline or complicated spreadsheets, just focused attention, one quarter at a time.
3. Make One Decision That Eliminates Weekly Worry
The best money decisions are the ones you make once but benefit from repeatedly. These are decisions that permanently reduce what behavioural economists call “decision fatigue”, the mental exhaustion that comes from constantly managing money in your head. What’s one choice you could make today that would remove a recurring financial worry?
It might be setting up an automatic standing order to transfer Rs. 10,000 to savings the day your salary arrives, before you can spend it. Maybe it’s consolidating your scattered savings accounts into one that actually pays decent return.
These aren’t dramatic moves that require personality transplants. They’re structural decisions that work with your human tendency toward inertia rather than against it. Most banks now offer seamless digital automation. You can set it up once and benefit from that decision every single month without additional effort or willpower. You make the decision once. You benefit all year. That’s leveraging your energy intelligently.
4. Stop Spending on Who You Think You Should Be
Sri Lankan society comes with heavy expectations. The car you drive, the school your children attend, the hotels you patronise, the brands you wear, all communicate your worth, or so we’re told. Much of our spending isn’t about actual enjoyment. It’s about meeting unspoken expectations, keeping up appearances, or aspiring to a version of us that doesn’t actually exist.
We buy expensive saris we’ll wear once because everyone does. We maintain memberships to clubs we rarely visit because it looks good. We say yes to weekend plans at overpriced restaurants because declining feels like admitting we can’t afford it. We upgrade phones not because ours stopped working, but because others have.
Before your next purchase, ask yourself: do I actually want this, or do I want to want it? If it’s the second one, walk away. You won’t miss it. This isn’t about deprivation, it’s about precision. When you stop spending to perform and start spending to support the life you genuinely enjoy, money pressure eases dramatically. Your resources align with your actual values rather than imagined expectations.
Maybe you don’t care about fancy restaurants, but you love long drives along the southern coast. Maybe branded clothing leaves you cold, but you’d spend any amount on art supplies or books. That’s fine. Spend accordingly.
5. Break One Habit, See If You Actually Miss It
We’re creatures of routine, which serves us well until those routines outlive their usefulness. Sometimes we spend money on habits that started for good reasons but no longer serve us. Alpechchathava, in Buddha’s teaching, means living contentedly with few desires. It guides a person to manage money wisely by avoiding excess spending, unnecessary debt, and craving, and by focusing on essential needs and wholesome priorities. In this way, wealth supports mental cultivation, generosity, and spiritual progress.
The daily kottu roti that once felt like a convenient solution after working late may now have turned into an unnecessary routine. Similarly, frequent P&S or Caravan snack runs, and the habit of picking up sugary treats like cakes and sweets, are not only costly but also wellknown to be unhealthy, as nutritionists consistently point out. Beyond food, other expenses such as magazine subscriptions, the monthly coffee meetup, or weekend mall browsing often continue on autopilot without us realising how much they add up. These seemingly small, habitual expenses can quietly drain your budget while offering very little longterm value.
Try this experiment: keep a money diary for one week. Note every expense, no matter how small. Then identify one regular spend and eliminate it for the following week. If you don’t miss it? Excellent, keep it gone. If you genuinely miss it? Add it back without guilt. This isn’t about permanent sacrifice.
It’s about snapping yourself out of autopilot and checking whether your spending still reflects your current reality, priorities and purchasing power. You might discover you’re spending Rs. 15,000 monthly on things you barely notice.
6. Create Your Crisis Playbook on a Good Day
Many financial disasters don’t happen because we’re careless, they happen because we’re panicked. When crisis strikes, job loss, medical emergency, unexpected business downturn, fear hijacks our decision-making. Our rational brain exists while panic makes expensive choices: high-interest personal loans, selling investments at losses, making commitments we can’t sustain.
The solution? Make your crisis plan before the crisis arrives. On a calm day, sit down and document: If I lost my income tomorrow, what would I do first? Which expenses are truly essential? What’s the absolute minimum I need to function? Who could I call for advice? Which savings are untouchable, which could be accessed if necessary? What government support or loan restructuring options exist (Not in Sri Lanka)? This is a sort of preparation for sudden shocks.
7. Question the Money Stories You Inherited
Sometimes our biggest financial obstacles aren’t failed attempts, they’re the attempts we never make because we’ve internalised limiting stories. “Our family was never good with money.” “Investing is for rich people.” “I’m just not the type who earns more.” “Women don’t understand finance.” These narratives, absorbed from family, culture, or past experiences, become invisible fences.
Question them. Where did this belief originate? Is it actually true, or is it a story you’ve been telling yourself for so long, it feels like fact? What would happen if you tested it? Often, these stories protect us from the discomfort of trying and potentially failing. But they also protect us from the possibility of succeeding. And that’s a far costlier protection than most of us realise.
The Bottom Line
Improving your finances in 2026 doesn’t require becoming a different person. It requires understanding the person you already are, your patterns, triggers, and tendencies, and working with them rather than against them.
These aren’t magic solutions. They’re evidence-based approaches that acknowledge a simple truth: you’re not broken, and your money management doesn’t need fixing through willpower alone. It needs better systems, clearer thinking, and a lot less shame.


by Prof. C. A. Saliya
 When people picture wealth, they often imagine luxury cars, large homes and expensive holidays. But financial advisers who work with wealthy clients describe a different picture: people who spend carefully, keep cash aside, invest patiently and understand the risks they take.
A recent Research NZ report, based on interviews with financial advisers, found that many wealthy people are discreet about money. They tend to live within their means, maintain emergency savings, take calculated investment risks and pay close attention to tax and financial structures.
For Sri Lankan families facing high living costs, loan repayments and uncertainty about the future, the lesson is not that everyone must become rich overnight. It is that better financial habits can create greater security over time.
Wealth is often quiet
One of the strongest habits associated with long-term financial stability is controlled spending. Many people with high incomes do not automatically increase their lifestyle every time they earn more. Instead, they decide in advance what they can afford, save consistently and avoid treating every salary increase as permission to spend more.
This does not mean denying life’s small pleasures. It means knowing the difference between a need, a want and a purchase made only to impress others.
In Sri Lanka, where social pressure can sometimes encourage visible spending on weddings, vehicles, clothing or celebrations, this is a difficult but useful principle. A household that earns well but spends everything may look prosperous while remaining financially fragile. By contrast, a family that saves even a modest amount regularly can build options: education for children, a medical reserve, a home deposit or capital for a small business.
The Central Bank of Sri Lanka’s financial-literacy survey found that bank-account ownership is high, but financial behaviour remains a concern. Its later roadmap notes that Sri Lankans show satisfactory financial knowledge compared with other countries, while positive everyday financial behaviour still lags behind.
Knowledge, in other words, is not enough. People also need routines.
Keep an emergency fund before taking bigger risks
The wealthy people described in the RNZ article often kept readily available savings for genuine emergencies and avoided using these funds for ordinary spending.
This is perhaps the most practical lesson for an average family. An emergency fund is not money that “does nothing.” It is money that protects a household from making a desperate decision when illness, job loss, vehicle repairs or an unexpected school expense arrives.
For some, the first target may be one month of essential expenses. Over time, it can be increased. The point is not perfection; it is having a buffer.
Without one, families may turn to costly borrowing, informal lenders or repeated credit-card debt. Research on household finance shows that weak credit knowledge, cross-borrowing and reliance on informal debt can increase the risk of over-indebtedness.
Saving alone may not be enough—but investing requires care
Saving is the starting point, not always the final destination. Money kept entirely in cash or low-return accounts can lose purchasing power over time, especially when prices rise. This is why financially secure people often invest—not recklessly, but with an understanding that long-term returns usually require some level of risk.
The key phrase is calculated risk. That means asking basic questions before investing: What is the business model? Is the institution regulated? How easily can I access my money? What happens if the investment falls in value? Am I being promised unusually high returns? Do I understand where my money is going?
A proper investment plan should not depend on rumours, social-media tips or promises of “guaranteed” profits. It should be diversified where possible—spread across suitable assets rather than placed in a single company, property deal or scheme.
For a young worker, investing may begin with a small, regular contribution. For a business owner, it may mean reinvesting carefully in a viable enterprise. For a family nearing retirement, capital protection and predictable income may matter more than aggressive growth. There is no single plan for everyone.
Debt can build wealth or destroy it

The RNZ article also makes a more controversial point: wealthy people sometimes use other people’s money, through debt or outside equity, to build businesses or buy assets. When investment returns exceed borrowing costs, borrowing can magnify gains. But the reverse is equally true: when returns fall or income is interrupted, debt magnifies losses.
This distinction is crucial in Sri Lanka.
Debt used for a productive purpose—such as a well-researched business, equipment that generates income, or an asset with manageable repayments—can be different from debt used for consumption. Borrowing for status purchases, repeated expenses or a lifestyle beyond one’s income can quickly become a burden.
Before taking a loan, families should calculate the monthly repayment under difficult conditions, not only favourable ones. Could the instalment still be paid if income falls? Is the interest rate fixed or variable? Is there enough emergency savings left after the initial payment? These questions may feel cautious, but caution is often what keeps a financial setback from becoming a crisis.
Pay attention to taxes and paperwork
Another quiet habit of financially successful people is paying attention to tax. They understand that the amount earned is not the same as the amount kept. They keep records, claim lawful deductions where applicable and structure businesses or investments properly.
The quiet habits
For self-employed people and small-business owners, this can be especially important. Clear records of income, expenses, invoices and taxes are not merely administrative chores. They help owners understand whether a business is truly profitable and make it easier to obtain formal finance when needed.
This is not an argument for avoiding tax. It is an argument for understanding the rules, meeting obligations and using legitimate options available under the law. When in doubt, taxpayers should seek advice from a qualified professional.
The human side of money
The most important lesson is that wealth is rarely created by one dramatic decision. It is usually built through repeated small choices: saving before spending, avoiding unnecessary debt, learning before investing, and staying patient when others are chasing quick gains.
A literature review of household finance supports this practical view. Studies consistently associate financial literacy, planning, self-control and budgeting with better saving and investment decisions. At the same time, the research warns that financial outcomes are shaped by income, access to formal financial services and economic conditions—not simply by individual discipline.
That matters in Sri Lanka, where many households are working hard simply to meet daily needs. Advice about wealth should never become blame. Not everyone starts with the same income, family support or opportunity.
But the habits that strengthen financial resilience are available in some form to most people: keep records, build a buffer, question easy-money promises, borrow carefully and make decisions based on long-term goals rather than short-term appearances. (See table)
Wealth may not always look glamorous. Often, it looks like an emergency fund nobody sees, an investment made patiently, a loan avoided, and a family that sleeps more peacefully because it has planned ahead.
(Prof. C. A. Saliya, is a charted accountant, academic, researcher and former banker. He is the author of SAMAJA GAVESHAKAYA and Springer Publication DOING SOCIAL RESEARCH. He can be contacted at saliya.ca@gmail.com. The views expressed in this article are his own and do not necessarily represent those of the organisations with which he is affiliated.)
by Prof. Ranjith Bandara,
Emeritus Professor, University of Colombo
This article examines why community exclusion, excessive bureaucratic control, unequal distribution of conservation benefits, weak institutional accountability, and short-sighted political leadership continue to undermine wildlife conservation in Sri Lanka.
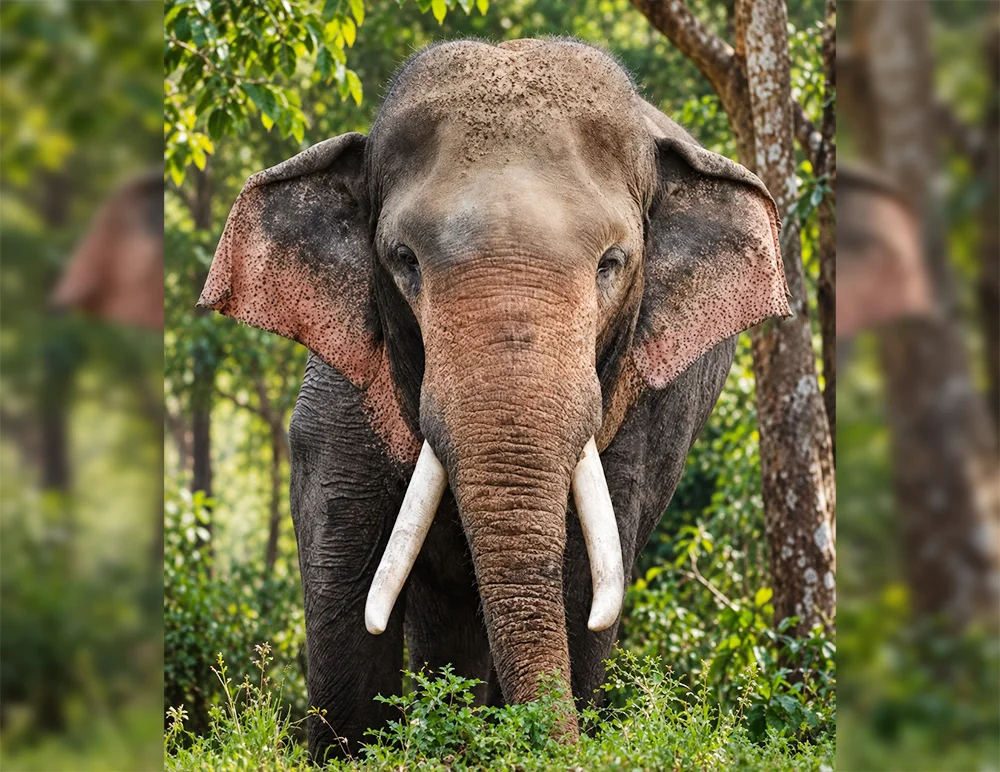
The death of Tusker Kavantissa is more than the loss of one of Sri Lanka’s most remarkable wild elephants. It exposes uncomfortable questions about how we protect our natural heritage, how conservation decisions are made, and why repeated warnings have failed to produce meaningful reforms. His death should compel us to examine not only what happened to one extraordinary animal, but also the deeper weaknesses in our wildlife conservation system.
Tusker Kavantissa, one of Sri Lanka’s most prominent wild tuskers, died on 16 October, 2026, after receiving veterinary treatment for an injury, reportedly caused by gunfire. Although the wound had shown some improvement, his health subsequently deteriorated. The precise cause of death requires confirmation through a proper post-mortem examination. Nevertheless, the circumstances raise serious questions about preventive protection, wildlife management, and institutional preparedness.
The wider picture is equally disturbing. According to recently reported figures, Sri Lanka has lost an average of approximately 402 elephants and 138 people annually, since 2019, due to human–elephant conflict. These figures reflect a continuing national tragedy affecting both wildlife and rural communities.
What Sri Lanka faces today is not merely a wildlife conservation problem. It is also a crisis of environmental governance, shaped by institutional weaknesses, political decisions, and the failure to recognise the economic and social realities of conservation.
Conservation without communities
One of the fundamental weaknesses of our conservation approach is that local communities are often treated as subjects of regulation rather than partners in conservation. They are expected to bear the risks, respect restrictions, and cooperate with government programmes, yet their influence over decisions affecting their lives remains limited.
For rural families living alongside wild elephants, conservation is not an abstract environmental objective. It directly affects their safety, agricultural income, property, and everyday lives.
Farmers frequently possess valuable knowledge about elephant movements, vulnerable locations, seasonal changes, and practical protection measures. Yet conservation interventions are sometimes designed without adequately considering this experience.
When decisions are imposed from above, communities may feel excluded from programmes they are expected to support. This weakens trust, reduces cooperation, and ultimately undermines conservation outcomes.
We must recognise that protecting elephants and protecting farmers are not conflicting objectives. Both are essential. A conservation policy that safeguards wildlife while neglecting human security cannot be considered successful.
The real challenge is to replace conservation imposed on communities with conservation undertaken alongside them. Meaningful participation requires more than consultation meetings. Communities must have a genuine role in planning, implementing, monitoring, and evaluating conservation activities.
Bureaucratic authority versus public accountability
Wildlife conservation requires strong institutions, professional expertise, and effective regulations. However, excessive bureaucratic control can become an obstacle when administrative authority takes precedence over practical outcomes.
Decision-making in Sri Lanka’s conservation system remains heavily dependent on central institutions. Administrative procedures, overlapping responsibilities, and limited coordination can delay responses to urgent problems.
More importantly, excessive centralisation can discourage local innovation and prevent communities from contributing practical solutions.
When administrative authority becomes more important than results, conservation risks becoming an exercise in controlling people rather than protecting nature.
This criticism should not be confused with questioning the dedication of frontline wildlife officers and veterinarians. Many work under difficult conditions with limited resources. The efforts undertaken to save Tusker Kavantissa deserve recognition.
However, individual commitment cannot compensate indefinitely for institutional weaknesses.
We must ask whether our conservation institutions have the capacity to identify risks early, protect vulnerable animals, coordinate emergency responses, and evaluate the effectiveness of their interventions.
Public accountability should, therefore, extend beyond compliance with administrative procedures to measurable conservation outcomes.
Who bears costs, and who receives benefits?
Perhaps the most neglected dimension of wildlife conservation in Sri Lanka is the unequal distribution of its economic costs and benefits.
Wild elephants contribute substantially to tourism, biodiversity, cultural heritage, and the country’s international image. Their conservation generates benefits enjoyed by society as a whole.
Yet the financial and personal costs are concentrated among rural communities living within elephant habitats.
A study published in 2023, involving 300 farming households in southern Sri Lanka, revealed a striking imbalance. Although these households lived near two national parks, none received economic benefits from tourism. Meanwhile, 57 percent had experienced elephant-related crop damage.
The findings raise a fundamental economic question: if the entire country benefits from elephant conservation, why should a relatively small and vulnerable section of society bear a disproportionate share of its costs?
Conservation cannot remain economically sustainable when its benefits are widely enjoyed but its costs are concentrated among those least able to bear them.
A separate study, published in 2024, involving 439 affected farming households, examined the possibility of financing compensation through tourism revenue. It demonstrated the potential for tourism-based financial mechanisms to support human–elephant coexistence.
The policy implications are significant
A proportion of wildlife tourism revenue could be directed towards affected communities through transparent benefit-sharing arrangements. Such measures could support compensation, village protection, local employment, community enterprises, and agricultural improvements.
However, financial compensation alone is insufficient. The 2023 study also indicated that fear of elephants and concerns about crop damage strongly influenced community attitudes. People must feel safe in their homes and farms, not merely receive payment after suffering losses.
Equitable benefit-sharing is, therefore, more than an act of generosity. It is an economic and social requirement for sustainable conservation.
Political decisions and absence of long-term vision
The weaknesses in wildlife conservation cannot be attributed solely to public officials. Political leadership must accept its share of responsibility.
Poor land-use planning, habitat fragmentation, obstruction of elephant movement corridors, and development decisions that inadequately consider environmental consequences have contributed to human–elephant conflict.
Political decisions made for immediate gains can create environmental and economic costs lasting for decades.
Another weakness is the preference for visible, short-term interventions.
Constructing electric fences, relocating elephants, and launching emergency operations can attract considerable publicity. However, such interventions should be evaluated according to their effectiveness, not their visibility.
Political leadership should be judged not by the number of conservation programmes announced, but by the lives protected, conflicts prevented, and long-term improvements achieved.
There is also a serious problem of policy continuity. Conservation cannot be governed according to electoral cycles or changing political priorities.
Elephant habitats, migration patterns, and ecological processes do not change with governments. Successful conservation, therefore, requires consistent national commitments extending beyond individual political administrations.
Without such continuity, public investment may be wasted while the underlying problems remain unresolved.
Problem is not always a lack of policy
Sri Lanka’s conservation crisis cannot be explained simply by a shortage of scientific knowledge or policy recommendations.
In many instances, the greater challenge lies in translating available knowledge into coordinated, adequately funded, and politically supported action.
The National Action Plan for the Mitigation of Human–Elephant Conflict, prepared in 2020, proposed a science-based approach that emphasised community participation, protection of villages and agricultural land, and more effective conflict-management strategies.
Yet an important question remains: how much of this plan has been implemented successfully?
Have implementation difficulties arisen from inadequate resources, weak institutional coordination, administrative resistance, or insufficient political commitment?
An independent assessment of the plan’s implementation would help identify these obstacles and establish clear responsibilities.
We must also recognise that a substantial proportion of Sri Lanka’s wild elephants live outside protected areas. Attempting to confine all elephants within national parks and forest reserves is, therefore, neither realistic nor sustainable.
Effective conservation requires land-use policies informed by elephant ecology, settlement patterns, agricultural needs, and the practical realities of human–wildlife coexistence.
A sound policy that remains largely unimplemented offers little protection to either elephants or people.
Towards more responsible conservation system
Sri Lanka needs a fundamental change in how wildlife conservation is governed.
Four priorities deserve immediate attention.
First, local communities must become genuine partners in conservation management, with meaningful responsibilities and decision-making opportunities.
Second, conservation benefits must be distributed more fairly. Wildlife tourism should contribute directly to protecting the livelihoods and safety of communities that bear conservation costs.
Third, existing national conservation plans should be independently reviewed to identify implementation gaps and establish a realistic timetable for corrective action.
Fourth, conservation institutions must become more accountable for measurable outcomes, including reductions in human deaths, elephant mortality, crop losses, and property damage.
These reforms require cooperation among wildlife, forestry, agriculture, land, irrigation, and local government institutions.
They also demand political leadership willing to prioritise long-term results over short-term publicity.
For exceptional animals, such as Tusker Kavantissa, improved risk monitoring, preventive protection, and timely veterinary responses are particularly important. However, conservation should not be limited to protecting a few well-known animals.
Every wild elephant has ecological value, just as every person living alongside elephants has an equal right to safety.
The objective must be a system that protects both.
Lesson tusker Kavantissa leaves behind
The death of Tusker Kavantissa should not become another moment of national sorrow that gradually fades from public memory. It should mark a turning point in how Sri Lanka approaches wildlife conservation.
A proper investigation into his death is essential. Equally important is an honest examination of the conservation system within which such tragedies continue to occur.
The real challenge is not choosing between people and elephants. It is creating a system in which both can coexist safely, and where the responsibilities, costs, and benefits of conservation are shared fairly.
This requires more than scientific expertise and stronger regulations. It demands accountable institutions, meaningful community participation, economic fairness, and political leadership guided by a clear long-term vision.
Our greatest failure would not be the loss of Tusker Kavantissa alone. It would be allowing the same weaknesses in our conservation system to claim more lives while we continue to avoid the reforms that could prevent them.

by Jehan Perera
The government appears set to overcome the first major challenge to one of its foundational principles. It has faced down demands from sections of the Buddhist clergy and opposition parties to release Ven. Galagodaatte Gnanasara from his prison sentence for contempt of court.
Ven Gnanasara is best known as the general secretary of the Bodu Bala Sena, a nationalist Sinhala grouping. The government seemed unfazed by a protest march organised by Buddhist monks and the opposition parties and its supporters organised an even bigger march to support the government’s position. It is notable that the general population did not get involved in either march in any substantial number. The issue has now become a test of whether the government will uphold its commitment to apply the law equally, irrespective of a person’s position or status, even when doing so brings it into conflict with a powerful constituency.
The case has a specific legal history. Ven. Gnanasara was sentenced to six years’ imprisonment by the Court of Appeal in 2018 for contempt of court in a case involving former military personnel where he disrupted the proceedings. The Supreme Court rejected his appeal in 2018. Former President Maithripala Sirisena subsequently granted him a presidential pardon in 2019. Last month, the Supreme Court invalidated that pardon. The initial demand by Buddhist monks and their lay supporters was that Ven. Gnanasara should be permitted to wear his Buddhist robes when appearing in public before the courts. The government has indicated its willingness to examine the procedures governing the treatment of Buddhist monks in prison, in consultation with the relevant religious authorities. However, the initial demand has now been escalated into a demand for a presidential pardon.
One of the central promises of the National People’s Power (NPP) during its election campaign two years ago was to apply the law equally to all. This commitment has shaped the government’s approach to allegations of corruption and criminality involving individuals who previously wielded political power. The NPP government was swept into power on a wave of antipathy towards those in previous governments who were perceived to have abused their positions for private gain. The economic collapse Sri Lanka experienced in 2022, and the hardships endured across society, remain vivid in the public memory. The past two years have seen the government pursuing those accused of corruption and other offences. Several high-ranking members of previous governments have faced arrest and legal proceedings and been sentenced to jail.
Religious Concerns
The ability of opposition parties to mobilise widespread resistance against proceedings involving their leaders has been limited, as much of the general population continues to favour accountability for past financial crimes. However, the case of Ven. Gnanasara is different. It does not concern allegations of financial corruption, but the relationship between religious authority, the courts and the law of the land. This is where the distinction between respecting religious traditions and upholding the law becomes crucial. There is a sense among sections of the general population that Buddhist monks should not be treated on a par with others and that requiring Ven. Gnanasara to appear in court without his robes was unjust and contrary to the national ethos. Such sentiments reflect the special place Buddhism occupies in Sri Lanka’s history and society. Sinhala Buddhist nationalism has been a potent political force throughout the country’s history, drawing on a heritage that extends back more than two millennia. The question is whether respect for Buddhism needs to also entail the exemption of individual monks from the ordinary requirements of the law and thereby treat them differently.
The challenge would be to accommodate legitimate religious concerns through rational and lawful procedures without allowing religious status to become a source of legal privilege. The government has been amenable to addressing the issue of monastic robes, but has so far resisted the demand to release Ven. Gnanasara through a new pardon. President Anura Kumara Dissanayake and government members have made it clear that the government would not bend the law to accommodate any individual. They have taken the position that any shortcomings in existing rules should be addressed by changing the rules through proper procedures, rather than by making an exception for a particular individual. If the government holds its position, it will demonstrate that its commitment to the rule of law extends even to constituencies that have historically enjoyed considerable political influence.
This is important not only for the country’s democratic institutions but also for its economic future. Sri Lanka is seeking to recover from its economic collapse and establish the foundations for sustained growth. The International Monetary Fund’s analysis of Sri Lanka’s governance weaknesses has repeatedly emphasised the economic costs of corruption and institutional deficiencies. Its 2024 analysis of governance and growth concluded that comprehensive and coherent reforms could bring significant macroeconomic benefits. The IMF’s 2025 assessment also highlighted the importance of sustained governance reforms in unlocking the country’s growth potential. Investors, both domestic and foreign, need confidence that public institutions function according to predictable rules, that contracts and property rights are protected, and that political connections or social status will not determine how the law is applied.
Sensitive Issue
Sri Lanka has long sought the leap towards prosperity that has proved elusive under successive governments. Economic reform alone will not achieve it. The connection between the rule of law and economic prosperity is direct. Businesses are more likely to invest when they can expect disputes to be resolved fairly, public resources to be managed transparently and regulatory decisions to be made on rational grounds. No country can achieve a durable economic take-off if its institutions are perceived to operate according to political favour, inherited privilege or communal pressure. Sri Lanka cannot afford to return to a political culture in which powerful interests are shielded from accountability while ordinary citizens bear the costs.
Changing a political culture that has evolved over the decades if not centuries is a difficult undertaking, particularly in a country where political leaders have long relied on religious and communal identities to consolidate their support. It requires not only firmness but also sensitivity, dialogue and a willingness to reform laws and institutions where genuine deficiencies exist. The present controversy offers an opportunity to demonstrate that these objectives need not be in conflict. The government can respect the Buddhist clergy’s concerns about the treatment of monks in prison while refusing to grant an individual an exemption from a judicial sentence. It can recognise the importance of Buddhism to the country while maintaining that no religious or political authority stands above the law.
The question is whether national traditions and ethos are interpreted in ways that strengthen justice, responsibility and social harmony, or invoked to defend privileges that undermine them. The country needs a transformation in public expectations from privilege to accountability, from communal claims to equal citizenship, and from personal discretion to institutions governed by law.
The government’s handling of the case involving Ven. Gnanasara is therefore about more than one monk or one sentence. This particular case will determine whether the government can build a system in which no government, religious authority or politically influential individuals can place themselves beyond the law. A just society must be able to honour both its traditions and its commitment to equality before the law.

Crystal Palace urged to retire bald eagle mascot

Little time to unpack as India open in Christchurch

Senior England players to miss Sri Lanka T20Is for WPL 2027

Bangladesh and Nepal to host Women’s Under-19 T20 World Cup from January 21 to February 6

Showers above 100 mm are likely at some places in the Western, Sabaragamuwa, Central, North-western, Northern and Southern provinces and in Anuradhapura district.

Low-quality coal causes power cuts: Ex-LECO Chief

‘Dates have the highest sugar content to fight Coronavirus’

Sunday Island 27 December – Headlines

#SundayIsland 17th December – Headlines

Sunday Island – 28th March

Sunday Island Headlines – 21 March

Sunday Island – 21st February – Headlines
-

 Features4 days ago
Kotahena:A Small Enclave, An Extraordinary Legacy
-
 News5 days ago
Asgiri Mahanayake calls for immediate release of Gnanasara Thera
-

 News3 days ago
Record 1,600 students take Russian Classical Ballet examination in Sri Lanka
-
 News7 days ago
AC President recuses himself from hearing prison attire case pertaining to Gnanasara Thera
-
 News6 days ago
Naval officer testifies Yoshitha received Rs. 5.15 mn in salaries during SLN service
-
 News4 days ago
Karannagoda pushed for £24,536 for Yoshitha’s UK training, Court told
-
 Editorial6 days ago
Saving Anojan: Beyond Executioner’s Blade
-
 News7 days ago
CID informs Fort Magistrate’s Court investigation into money laundering case against Namal completed